Every conversation about the artificial intelligence build-out eventually reaches the same chokepoint: power. Not processing power. Physical watts, delivered reliably, at hyperscale. Eaton Corporation (ETN) is the company that sits between the electrical grid and the server rack, and this morning it reports third-quarter results that will either confirm or complicate the best infrastructure story no one talks about in chip terms.
The Backlog Is the Business Case
Start with the numbers that actually matter. In the second quarter, Electrical Americas sales reached a record $3.951 billion, up 18% organically, while the twelve-month rolling average of orders rose 41% and total backlog finished June up 33% over the prior year. Electrical Global went further: that segment’s backlog increased 103% from the prior year, while rolling twelve-month orders rose 33% organically. Aerospace orders were up 17%, with backlog up 28%.
A book-to-bill ratio tells you whether a company is running toward demand or away from it. On a rolling twelve-month basis, the book-to-bill ratio for Eaton’s electrical businesses remained strong at 1.2, meaning orders are consistently outrunning recognized revenue. That is not a flash reading. It has been sustained across multiple quarters.
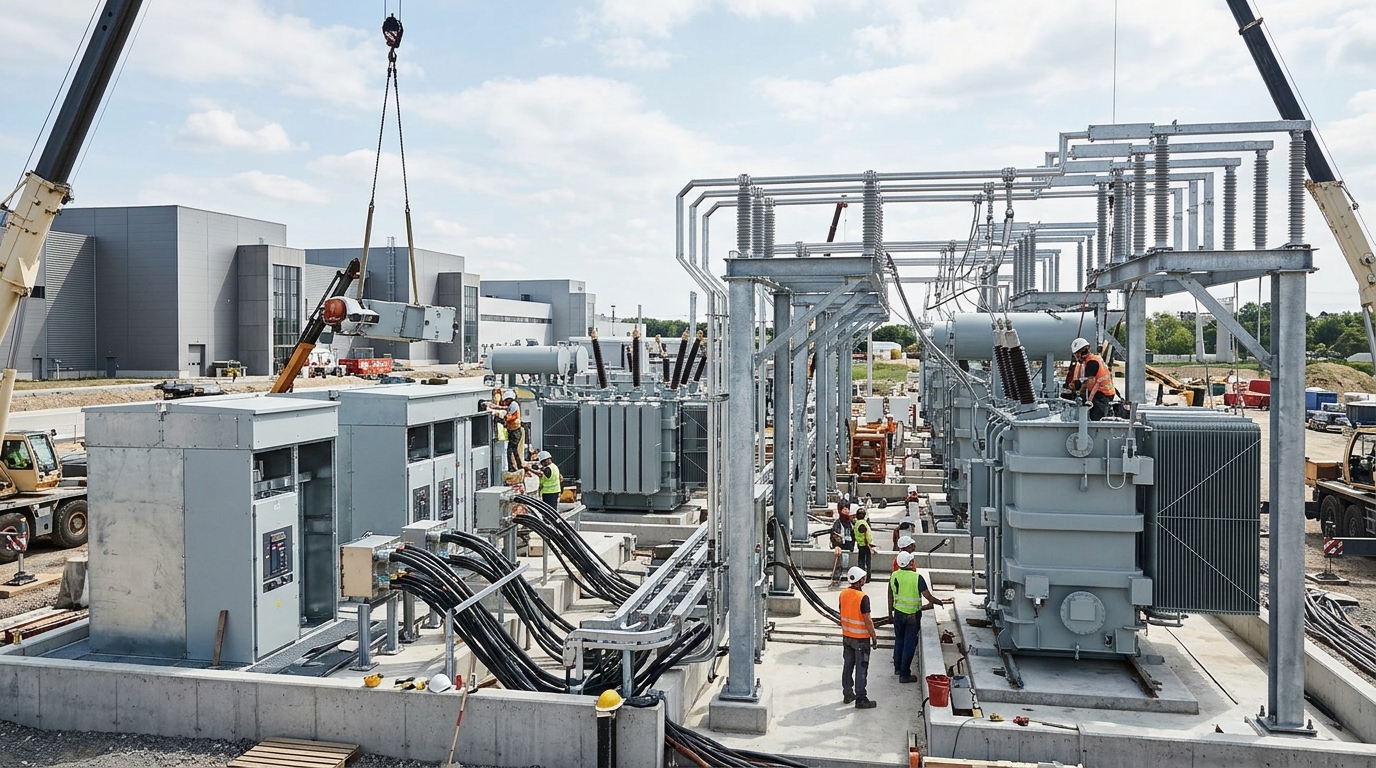
Data center capacity under construction and in the broader pipeline is being tracked by multiple industry sources, but the exact gigawatt totals vary meaningfully depending on what is counted as “planned” and how speculative projects are treated. Eaton does not make the chips that run inside those facilities. It makes the switchgear, power distribution units, uninterruptible power supplies, and modular enclosures that every data center needs before a single GPU can be turned on. That positioning is the moat.
What the Q3 Report Must Prove
For the third quarter, management guided to organic growth of 13.5 to 15.5% and adjusted earnings per share of $3.46 to $3.56. Analysts expect roughly $3.54 per share on revenue of about $8.53 billion. Eaton has beaten the consensus adjusted EPS estimate in each of its last several quarters, so the number itself is unlikely to be the story.
The real question is whether backlog is converting into revenue at a pace fast enough to justify the valuation. As of the Q2 update, management continued to emphasize that capacity is being ramped to meet demand, with some lead times still extended in parts of the portfolio. That last nuance matters. Management has said it is investing $1 billion across 24 projects in Electrical Americas to scale production output. September brought another signal of intent: Eaton announced a more than $242 million investment in a new North Little Rock, Arkansas facility, designed to double U.S. manufacturing capacity of customized electrical enclosures to meet growing demand across data center and utility markets.
The Mogul Lens
A disciplined long-term investor evaluating Eaton is not really asking about Q3 earnings per share. The question is structural: how durable is the demand, and does Eaton hold its competitive position long enough to translate backlog into compounding revenue and margin expansion?
Eaton is also sharpening its focus, having announced a Reverse Morris Trust transaction to separate its Mobility Group, combining it with Dana Incorporated in a deal that values the combined entity at over $10 billion. Shedding a lower-margin, cyclical auto business to concentrate on electrical infrastructure is exactly the kind of capital allocation decision that long-horizon investors reward over time.
The competitive risk is real. GE Vernova (GEV), Quanta Services (PWR), Vertiv (VRT), and Hubbell (HUBB) are all chasing overlapping slices of the same power infrastructure opportunity. None of them offers precisely the same grid-to-rack portfolio Eaton does, but competition for hyperscaler contracts is intensifying and lead time improvement by any one player shifts the dynamic.
The Verdict Before the Call
Management has been clear that while data centers remain a key growth driver, robust demand spans multiple end markets. That breadth is underappreciated. Utilities, industrial customers, and aerospace are all contributing to backlog growth, which means the investment case does not collapse if one hyperscaler slows its spending cycle.
The Q3 report and the 11 a.m. Eastern call will reveal whether conversion is accelerating alongside orders. If it is, Eaton’s argument as the power infrastructure compounder of the AI era gets considerably stronger. If margins slip while backlog continues to grow, the more urgent discussion becomes how long a company can sustain a 1.2 book-to-bill before execution risk becomes the lead concern. That tension is what makes today’s report worth watching closely.