October 28, 2026
Bonus Content: Stellantis Lost Money Again. Here Is What Has to Change.
Dear Reader,
Marc Chaikin just shared a chilling AI prediction.
And we strongly urge you to pay attention if you have even a cent in the market.
Because Marc says this ONE secret explains why stocks like Micron Technology (MU) just crashed, and the industry where you’ll find AI’s next winners…
Why listen to 60-year Wall Street legend, Marc?
Marc developed one of Wall Street’s most famous indicators, which appears on every Bloomberg and Reuters terminal in the world.
An indicator that helped him navigate nine bear markets successfully…
And create his proprietary stock rating system, the Power Gauge.
This award-winning system was built to predict the behavior of stocks three to six months in the future.
It flashed BULLISH on all of the “Magnificent Seven” stocks in early 2023…
And last year, it flashed BULLISH on virtually all the market’s top 50 stocks.
But today, Marc’s system shows money is leaving companies like Micron and flooding into an entirely unexpected corner of the market.
Make no mistake.
Marc says one secret explains why money is fleeing certain stocks and moving to the industry AI companies will need NEXT…
It’s the chance to own multiple winners of 100%, 300%, 500%, even 1,000%… all at once.
But the stocks that benefit next will NOT be the names most folks are watching today.
Marc reveals all the details for free in this brand-new presentation.
But please be warned: this is extremely time-sensitive information.
And with many AI stocks already plummeting…
This briefing could be your last chance to understand the secret Marc is relying on to guide his followers through what comes next.
Click here to see the details while you still can.
Good investing,
Vic Lederman
Publisher, Chaikin Analytics
P.S. Marc is also sharing the name and ticker of a stock at the center of this major AI story. It’s 100% free, right here.
Stellantis Lost Money Again. Here Is What Has to Change.
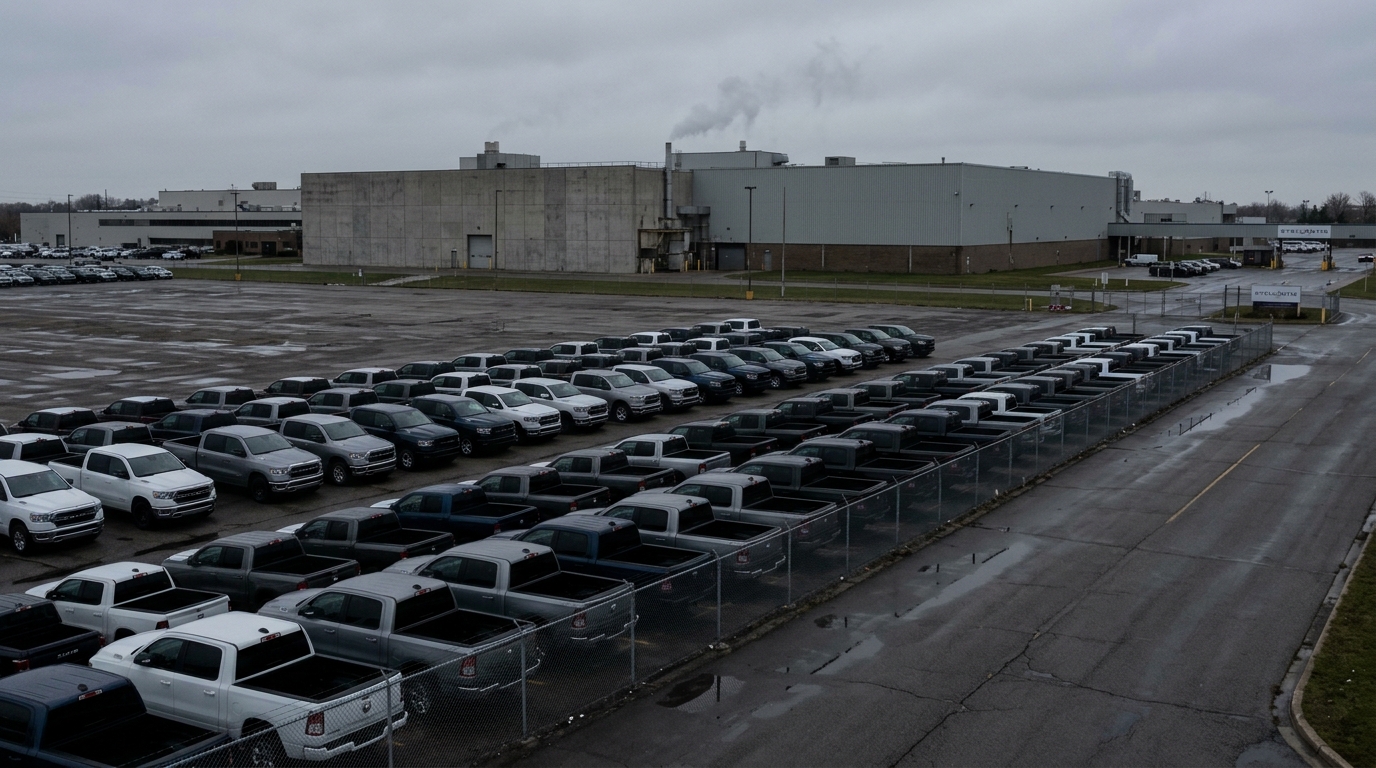
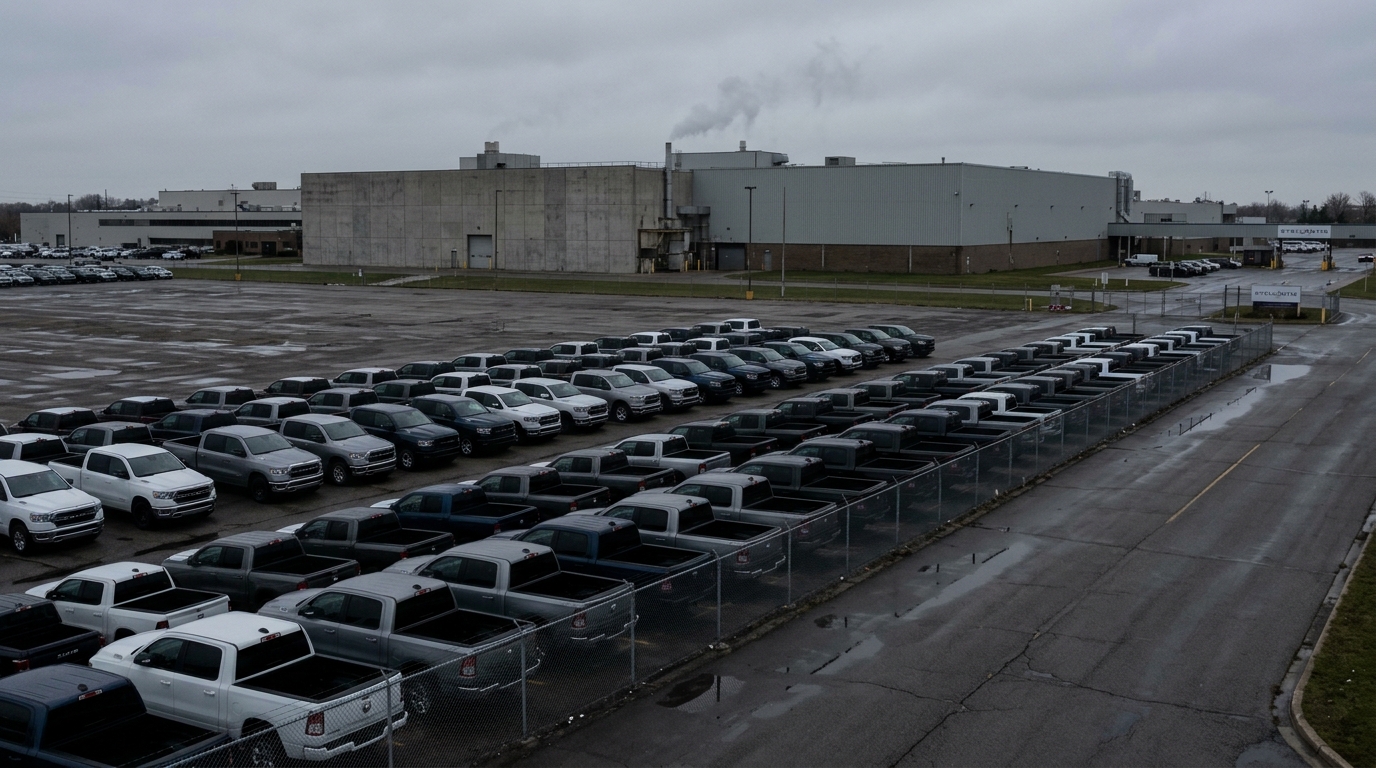
Hey there, bargain hunter. Stellantis trades at 0.06x sales. Ford trades at roughly 0.26x. General Motors sits near 0.4x. By that measure, Stellantis is the cheapest large automaker on the planet. It also just posted its second consecutive quarterly net loss. Cheap and value are not the same word, and today’s numbers make that distinction uncomfortably clear.
Scoreboard
Q3 2026 net revenues: €37.6bn, up 1% year over year. Nine-month revenues: €119.2bn, up 7%. Net loss: €453 million, a 90% improvement on the prior-year period. Adjusted operating income: €256 million, AOI margin of 0.7%. Industrial free cash flow: negative €4.0 billion. Shipments: 1.286 million units, down 1% year over year.
What Actually Happened
Europe carried the quarter. Enlarged Europe shipments rose 10%, driven by BEV growth through Stellantis brands and its Leapmotor partnership. South America contributed a 3% revenue gain. Then North America showed up with a 12% shipment decline, dragging the consolidated number into near-flat territory.
Management’s explanation: planned summer production shutdowns, particularly on Jeep Grand Cherokee and Compass lines. Ram partially offset the damage, adding roughly 17,000 units on the back of expanded powertrain offerings and the new Ram 1500 TRX. But North America is where Stellantis has historically made almost all its money. A 12% volume drop there is not a rounding error.
Regulatory tailwinds are also shifting the cost structure for truck-heavy lineups. The SAFE III rollback resets compliance economics for automakers whose profits depend on large SUVs and pickups.
The cash picture is the harder read. Industrial free cash flow came in at negative €4.0 billion for the quarter, an improvement of roughly €0.3 billion versus Q3 2025 but still a significant drain. The company held €42.7bn in industrial available liquidity, equal to 26% of trailing 12-month revenues, sitting inside its stated 25-30% target band.
The Business in Brief
Stellantis runs 14 brands across five continents: Jeep, Ram, Peugeot, Fiat, Citroën, Opel, Maserati, and more. North America has historically generated the bulk of profit, largely from high-margin trucks and SUVs. Europe matters for volume and is becoming more important for BEV compliance. The company’s FaSTLAne 2030 strategic plan targets a gradual sequential improvement in revenues, margins, and cash generation through the decade.
North America truck profitability is the shared pressure point across the sector. Ford’s billion-dollar Kentucky Truck Plant commitment shows how dependent legacy automakers remain on high-margin North American truck volume.
Is It Cheap?
On price-to-sales, STLA at 0.06x makes Ford at 0.26x look expensive. Price-to-book sits at 0.20x, the lowest among its listed peers. Analyst consensus price target is around $7 per share, roughly 70% above the pre-results quote near $4.14. The GF Score flags it as a possible value trap, and that label is doing real work here.
Full-year guidance holds: mid-single-digit revenue growth and a low-single-digit AOI margin. The company also reaffirmed that industrial free cash flow will be positive in 2027. Those are the two targets that matter most.
Bull / Base / Bear
- Bull: North America production restarts in Q4 following the planned shutdowns. A stronger second half closes the cash gap, guidance proves conservative, and the stock re-rates toward peers.
- Base: Q4 shipments recover modestly. Full-year AOI margin lands at the low end of low-single-digit. Free cash flow stays negative for 2026 but narrows. The 2027 positive cash flow target survives.
- Bear: North America demand proves weaker than the shutdown story suggests. Pricing pressure intensifies amid a softening US market. The cash burn continues past 2026, guidance gets revised lower, and the stock finds a new floor.
Action Plan
Do not chase this today. The Q4 North America restart is the next real test. If shipments in North America recover toward 400,000 units and AOI margin breaks above 1% for the full year, the bull case gains traction. Scale into a starter position only if both conditions are tracking by the February 2027 full-year results. Use €42.7bn in liquidity as your backstop signal: if that number deteriorates toward 20% of trailing revenues, the bear case is accelerating.
Cheap Investor Checklist
- North America Q4 shipment recovery above 400k units
- Full-year AOI margin confirmed above 1%
- Industrial free cash flow turning positive by mid-2027
- Industrial liquidity holding above 25% of trailing revenues
- Enlarged Europe BEV growth sustaining double-digit momentum
- Net loss eliminated on a quarterly basis by Q2 2027
Bottom Line
If North America volumes recover in Q4 and the 2027 free cash flow pledge holds, STLA at 0.06x sales is a genuine mispricing. If North America weakness is structural rather than seasonal, the cheapness is a warning, not an invitation. Wait for the Q4 data before sizing up.