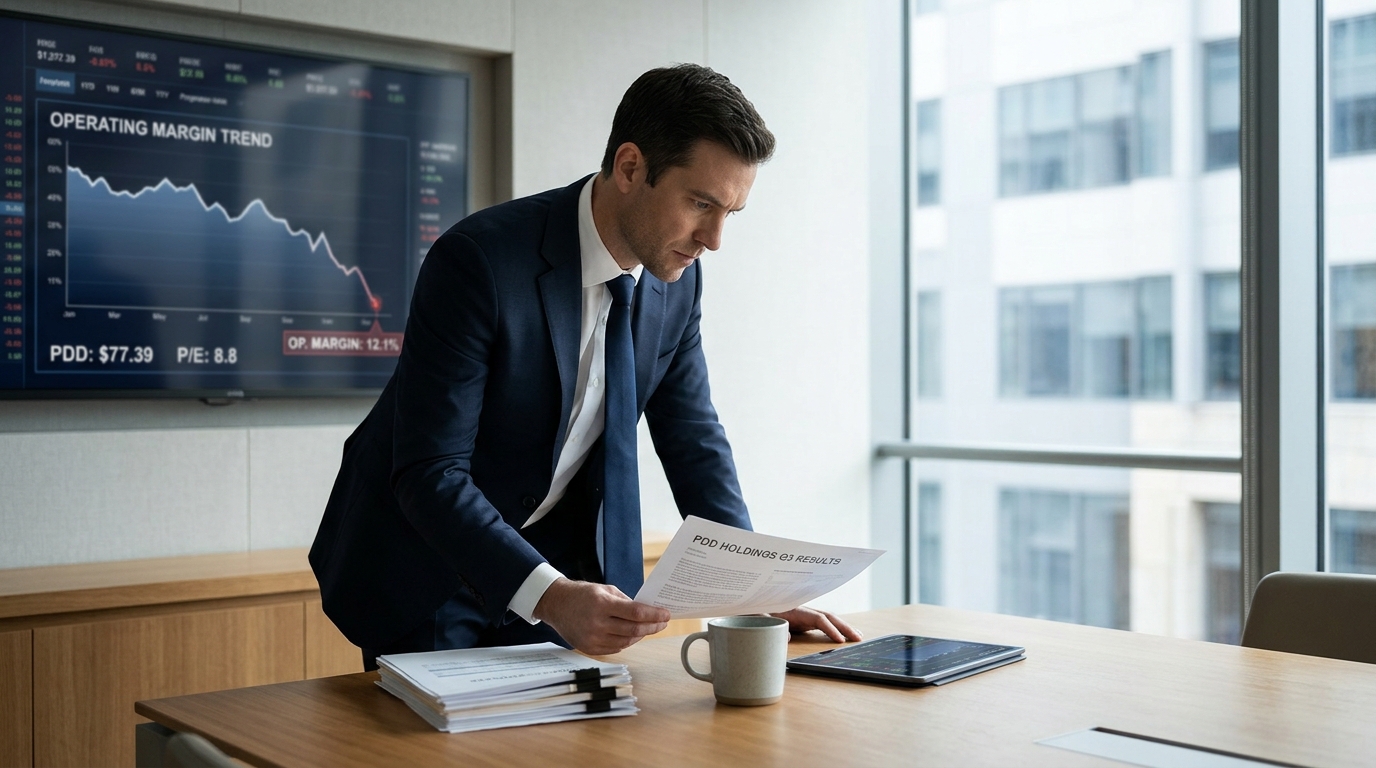
Hey there, bargain hunter. PDD Holdings drops its third-quarter results before the US open today, November 19. The stock closed Tuesday at $77.39, sitting closer to its 52-week low of $71.94 than its high of $139. That is a headline number worth pausing on. But the number that actually drove this stock into the ground is not the share price. It is the operating margin.
Scoreboard
PDD trades around 8x trailing earnings with a market cap near $110 billion. Consensus for Q3 revenue sits at roughly RMB115.5 billion, up about 7% year over year. Analysts forecast adjusted net profit of approximately RMB27.3 billion, down about 13% from last year’s RMB29.3 billion in the same quarter. EPS consensus is around $2.77 to $2.79, against last year’s $3.16. This is not a growth story anymore. It is a margin story.
What Actually Happened Getting Here
The operating margin compression has been systematic. In Q4 2025, revenue grew 12% but costs of revenue rose 15%. In Q1 2026, operating expenses climbed and adjusted net income fell 17%. In Q2 2026, operating expenses jumped 13% to RMB36.6 billion while revenue grew only 8%, and net income fell another 12% to RMB27.2 billion.
The bright spot: gross margin widened to roughly 57.3% in Q2, up from 55.9% a year earlier. The operating margin in the first half of 2026 was 22.4%, up from 22.0% a year earlier. That is what makes today interesting. Stabilization at a lower level is not the same as deterioration, but it is not the expansion investors originally priced in.
Margin stabilization alone may not be enough to re-rate the stock while the broader China equity market remains under structural pressure. Forward valuations across Chinese equities have compressed sharply, raising the question of whether cheap is a signal or a warning.
The Real Reason the Stock Is Here
Temu is expensive to run. Online marketing services revenue grew just 3.5% in Q2, a near-stall in PDD’s domestic ad engine. Transaction services picked up the slack with 13% growth, but that revenue line carries heavier fulfillment and logistics costs. Then comes the new variable: Europe started charging a €3 duty per item in consignments under €150 on July 1, 2026. Q3 is the first full quarter carrying that cost. In October, Temu also settled a $3 million data and product safety dispute with Texas. Neither is fatal. Together, they represent the kind of recurring friction that chips at a margin line that is already under pressure.
Chinese internet advertising is under pressure across the board, not just inside PDD. Tencent’s own advertising acceleration faces the same Chinese consumer weakness that stalled PDD’s domestic ad engine.
Is It Cheap?
The valuation says yes. PDD trades at roughly 8.5x trailing earnings and around 7x forward. The 35 Wall Street analysts covering the stock have an average price target near $113, implying 45% upside from current levels. JD.com’s Q2 net margin was 2.1%; PDD’s was 24.2%. The gap is enormous and gives PDD room other Chinese e-commerce names simply do not have.
But cheap relative to peers and cheap in absolute terms are different arguments. EPS is forecast to fall 5% in 2026 before recovering 20% in 2027. If that recovery materializes, the stock looks very mispriced here. If costs keep outrunning revenue, the discount is deserved.
Bull / Base / Bear
- Bull: Gross margin holds near 57% in Q3, online marketing revenue reaccelerates from its Q2 stall, and Temu absorbs the EU duty without further margin damage. Market re-rates a business earning 24% net margins at more than 8x.
- Base: Revenue meets consensus at ~RMB115.5bn, net income comes in around RMB27bn, margin stabilizes. The stock drifts sideways as investors wait for 2027 EPS recovery proof.
- Bear: Operating expenses grow faster than revenue again, Temu volumes are visibly lower due to EU friction, and guidance language turns cautious. The stock retests $71.94.
Action Plan
Do not buy the ticker because it looks cheap. Buy it because the margin floor is confirmed. Watch Q3 gross margin versus Q2’s 57.3%. Watch online marketing revenue growth: anything above Q2’s 3.5% signals the domestic ad engine is not broken. Watch operating cash flow against last year’s RMB45.7 billion. If two of those three show improvement, the discount looks too steep. If all three disappoint, the floor may not be $71.
Cheap Investor Checklist
- Q3 gross margin: does it hold near 57%?
- Online marketing revenue growth: above or below Q2’s 3.5%?
- Operating expenses growth rate vs. revenue growth rate: is the gap narrowing?
- Net income vs. prior year RMB29.3 billion: how far does it land?
- Operating cash flow direction versus Q3 2025’s RMB45.7 billion
- Any guidance language on Temu EU duty absorption
- Forward P/E stays below 8x even after results: valuation buffer intact?
Bottom Line
If Q3 gross margin holds and online marketing reaccelerates even modestly, PDD at 7x forward earnings is one of the stranger discounts in large-cap tech. If costs bite again and Temu volumes show EU friction, that cheap price tag has earned its discount. The report lands this morning. The margin line, not the revenue line, is the verdict.