November 5, 2026
Bonus Content: Qualcomm Beat Earnings. Then Fell 8% After Hours.
Dear Reader,
What happens when the government can see every single dollar you spend and decide where you can spend it?
Bank of America said the digital dollar is “inevitable.”
Ray Dalio, who predicted the 2008 crisis, didn’t mince words:
“There will be no privacy. It’s a very effective controlling mechanism by the government. You could be shut off if you were politically disfavored.”
Most people don’t know FedNow is already live.
It’s not the digital dollar yet, but it looks like the rails the digital dollar could run through.
1,400+ banks are using the infrastructure right now. It’s all detailed in Federal Reserve Docket OP1670.
Once your money runs through their system, they can see everything…
Freeze it…
Decide what you’re allowed to buy…
China already did this.
Nigeria already did this.
But there’s a way to protect your assets from this system before it’s fully implemented.
I’m Tan Gera, CFA© Charterholder and ex-Wall Street banker.
I just recorded a presentation showing exactly how to opt out of a potential digital dollar while it’s still possible.
Watch how to opt out before the window closes →
Once CBDCs go live, your financial privacy is gone forever.
To your freedom,
Tan Gera, CFA©
Co-Founder | Decentralized Masters
P.S. Ray Dalio said “You could be shut off if you were politically disfavored.” Bank of America says it’s inevitable. Learn how to protect yourself before it’s too late →
Qualcomm Beat Earnings. Then Fell 8% After Hours.
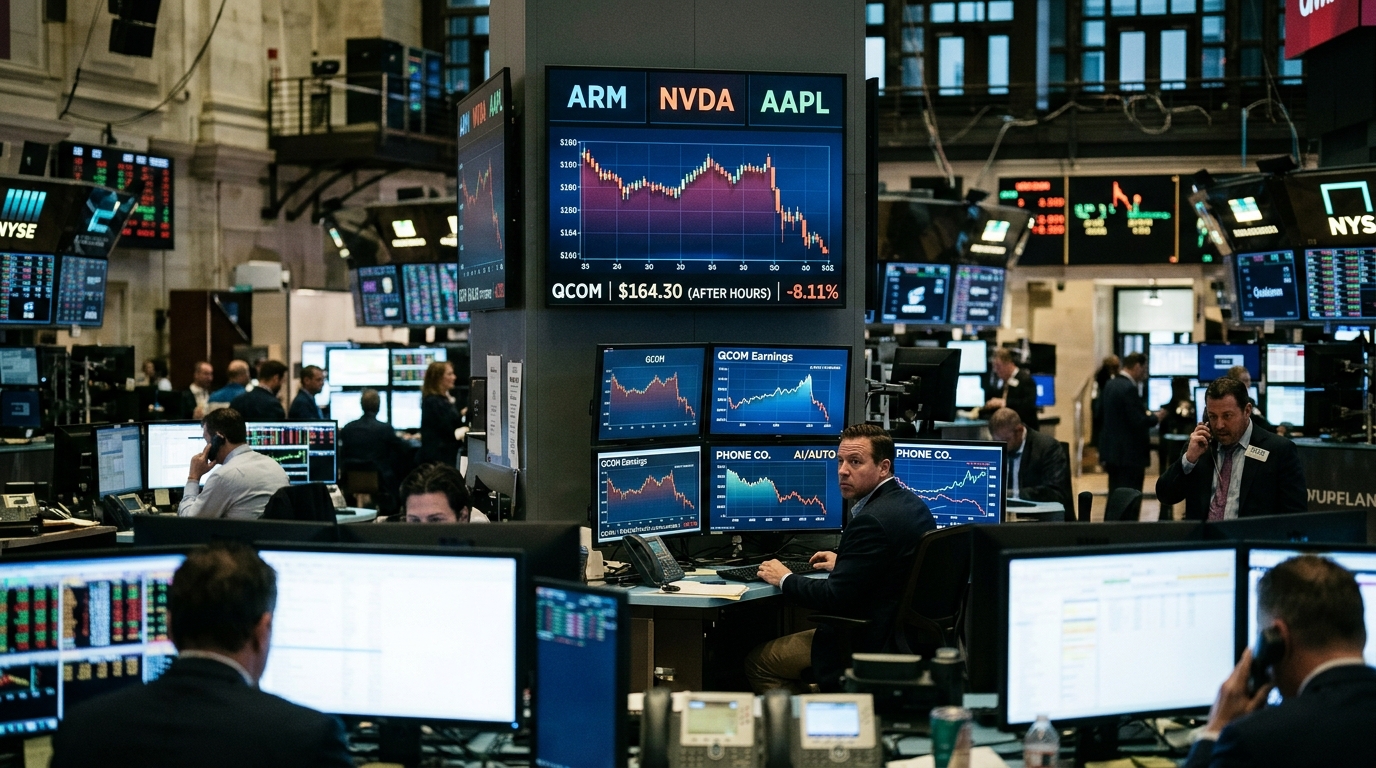
Hey there, bargain hunter. Qualcomm just handed you a beat, a bullish revenue guide, record automotive numbers, and a data center ramp that management won’t stop talking about. The stock rewarded all of that by closing up 5.3% on Wednesday, then giving it all back after hours.
Scoreboard
Fiscal Q4 non-GAAP revenue landed at $10.4 billion, above the $10.14 billion consensus. EPS came in at $2.17, right on the nose. QCT chip revenue hit $9.0 billion, up 6% sequentially and at the high end of guidance. Automotive posted its first-ever $2 billion quarter, up 89% year over year. For the full fiscal year, non-GAAP revenue was $43.2 billion, with automotive and IoT combined growing 24%.
Then management guided Q1 FY2027 revenue of $10.4 to $11.2 billion, a midpoint of $10.8 billion that beat the $10.48 billion consensus. The EPS midpoint of $2.15 missed the $2.32 Wall Street wanted. Chip-design margins are guided to 20-22%, down from 24%, because folding the new data center segment into QCT drags on near-term profitability. QCOM dropped 8% after hours.
What Actually Happened
The market priced in a clean guide and got a revenue beat paired with an EPS miss. Handset revenue fell 26% year over year in Q4, Apple revenue is now fully out of the model, and the data center business is real but front-loaded with costs. That margin drag from data center investment hit the consensus EPS number, and sellers didn’t wait to hear the explanation.
The long-term QCT margin target of 30% is unchanged. Supply, not demand, is the stated constraint on data center upside beyond $5 billion in FY2027. The selloff is a reaction to a one-quarter margin line, not a verdict on the business.
What the Business Actually Is Now
Qualcomm runs two machines. QCT designs chips: Snapdragon processors for phones, custom silicon for data centers, automotive compute platforms, and IoT modules. QTL licenses its wireless patent portfolio to nearly every phone manufacturer on earth, collecting royalties on each device sold regardless of whose chip is inside.
The royalty business is high-margin and sticky. The chip business is diversifying fast. Management’s own target: by the end of FY2027, non-handset revenue, covering automotive, IoT, and data center, will represent more than 50% of QCT revenue and will grow more than 60% year over year. Automotive alone exited FY2026 at an $8 billion annualized run rate, $1 billion ahead of guidance. Data center is guiding $650 million or more in Q1, scaling to a $7 billion annualized run rate by the end of FY2027, and targeting more than $15 billion by FY2029.
Key Metrics
- FY2026 non-GAAP revenue: $43.2 billion
- Q4 automotive revenue: about $2.0 billion, up 89% YoY; first $2 billion quarter
- Q1 FY2027 data center guidance: greater than $650 million
- FY2027 data center target: $5 billion
- FY2029 data center target: more than $15 billion
Is It Cheap?
This is the whole argument. QCOM trades at roughly 19x trailing earnings and a forward P/E in the high teens. Arm Holdings carries a forward P/E of approximately 86x. Broadcom sits at roughly 17-19x forward earnings, but Broadcom’s AI chip revenue grew 143% year over year in Q2 and the market has bid that multiple accordingly.
Qualcomm, by contrast, is priced as though the handset business is all it has. That multiple made sense a year ago. It makes less sense when non-handset revenue is about to cross 50% of QCT revenue and automotive is compounding at nearly 90%. The bear case is that the data center margin math is ugly and the Apple modem exit is a permanent hole in revenue. The bull case is that you are buying a chip company with an $8 billion automotive run rate and a $5 billion data center business at the price of a sleepy royalty licensor.
Bull / Base / Bear
Bull: Data center scales to $7 billion exit run rate on schedule. Non-handset revenue exceeds 60% growth in FY2027. The market re-rates QCOM toward 25x as the handset label no longer fits. Stock recovers toward the $200 analyst mean target.
Base: Data center ramps but margin pressure persists through FY2027. Handset weakness offsets gains. Stock grinds sideways in the $160-180 range, supported by buybacks and the 2.2% dividend.
Bear: Data center customers reduce custom silicon orders or push timelines. Supply constraints become a demand excuse. Margin guide stays below 22%. Stock retests the 52-week low near $122.
Action Plan
The after-hours drop into the $158-160 range makes this more interesting, not less. The revenue guide beat. The EPS miss was mechanical, driven by segment reclassification and front-loaded data center investment, not a deteriorating business. For a cost-conscious buyer, consider a first tranche near current levels, with a second add if the stock tests the $150 area on broader market weakness.
Cheap Investor Checklist
- Data center revenue exceeds $650 million in Q1 FY2027: watch the December quarter report
- Non-handset QCT revenue crosses 50% of total QCT in FY2027: on track per guidance
- Automotive annualized run rate holds at or above $8 billion
- QCT margin recovers toward the long-term target as data center ramp costs plateau
- No further Apple revenue in model: already baked in, not an incremental risk
- Data center hyperscaler customer count expands beyond two confirmed accounts
- FY2029 data center target of more than $15 billion remains intact on each earnings call
Bottom Line
If data center and automotive deliver what management guided, QCOM at 19x forward earnings is significantly mispriced. If the ramp stalls and handset weakness deepens, the discount is earned. The Q1 FY2027 print in February is the first real test: watch whether data center revenue clears $650 million and whether QCT margins stabilize. Until then, the stock offers a dividend to pay you to wait for the market to notice Qualcomm is no longer a phone company.