October 13, 2026
Bonus Content: Ramp Is Worth $60 Billion. Here Is What You Can Buy Instead.
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Hi, James Altucher here.
I’m reaching out today to relay epic three words, recently spoken by Elon Musk.
Infinite.
Money.
Glitch.
It sounds insane…
But that’s what Elon is calling a groundbreaking new class of technology about to take the world by storm.
I have put together a short presentation on what it is and why I believe this could be the biggest wealth event of our lifetime.
[ → Watch the presentation by October 21 ]
James Altucher
PS: I’m giving away a free report to anyone who watches this presentation today. It details Elon’s Musk’s unprecedented trillion-dollar compensation package and identifies the companies he NEEDS to hit his incentives. Just click here to watch the free video, and I’ll show you how to claim it. No credit card needed.
Ramp Is Worth $60 Billion. Here Is What You Can Buy Instead.
Hey there, bargain hunter. A startup that did not exist eight years ago just got handed a valuation larger than every publicly traded financial technology company except a handful of giants. That is the news. The question you should be asking is not whether Ramp deserves it. The question is: who gets hurt if it does not?
Scoreboard
Bloomberg reported Friday, October 9, that Ramp closed roughly $1.85 billion in new funding at a $60 billion pre-money valuation, led by Dragoneer and Thrive Capital, with Founders Fund writing a large check alongside them. Four months ago, in its June Series F, Ramp raised $750 million at $44 billion. That is a $16 billion markup in one summer, a 36% re-rate with no public financial update to explain it.
The Real Reason
Ramp’s pitch is not just corporate cards anymore. The 2026 investor deck is built around AI inside finance workflows: an August product called Router.com that the company says cuts AI costs by roughly 30% internally, and a June launch called Ramp Stack aimed at accounting firms. Ramp has said it now serves more than 70,000 organizations, and it said in June that annualized revenue was over $1 billion, with positive free cash flow. The growth is real. The valuation math is where it gets uncomfortable.
The Multiple Problem
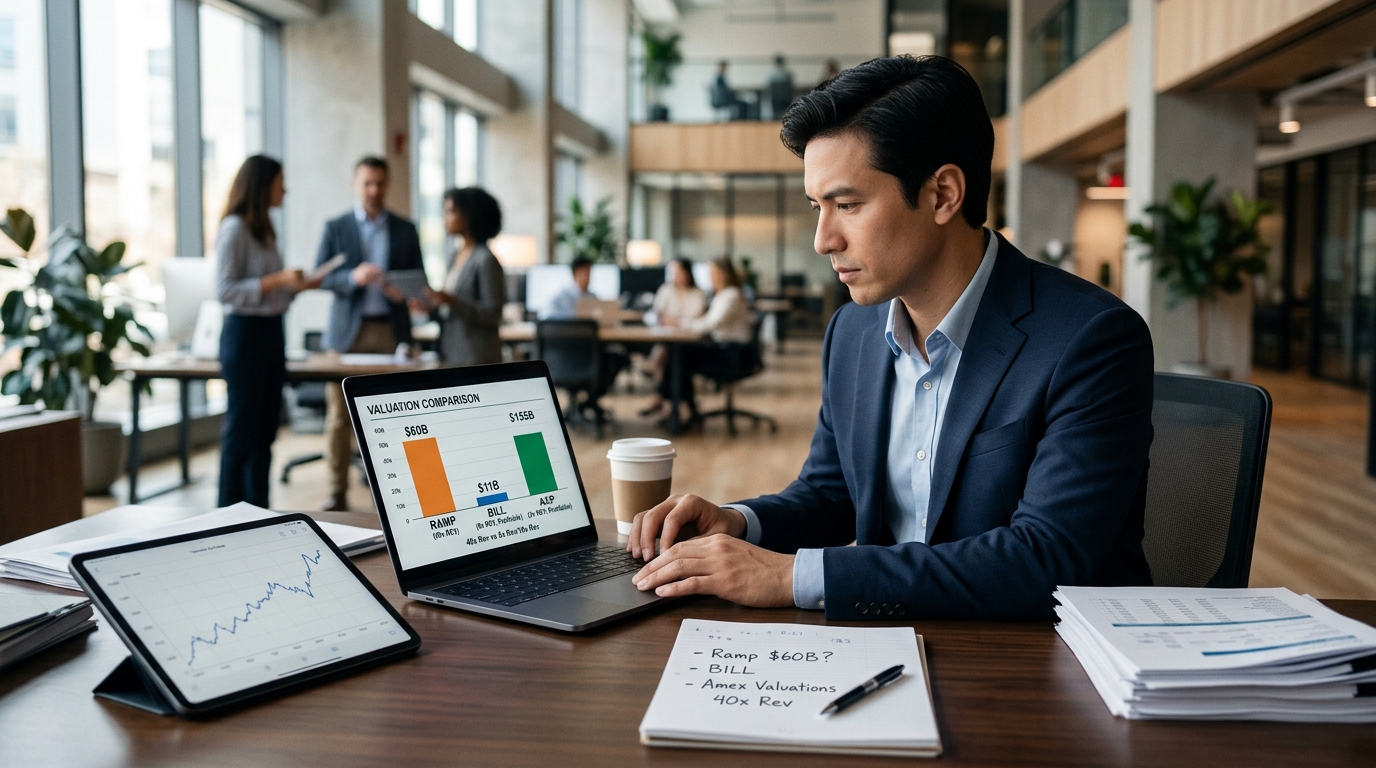
At $60 billion on roughly $1.5 billion in annualized revenue, Ramp is priced at about 40 times revenue. That is not a fintech multiple. That is a frontier-AI multiple applied to a payments-and-expense business whose core economics still depend on interchange fees and software subscriptions.
Now pan the camera left.
- BILL Holdings (BILL): Fiscal year 2026 total revenue of $1.65 billion, 13% growth year-over-year, 81.7% non-GAAP gross margin in Q4, and non-GAAP net income of $314.8 million for the full year. Market cap today: roughly $5.1 billion. That is approximately 3.1 times trailing revenue. BILL says it processes about 1% of U.S. GDP annually through its platform.
- American Express (AXP): Q2 2026 revenue of $19.6 billion, up 10%. The company raised its full-year revenue growth guidance to 10%, with EPS guidance of $17.30 to $17.90. Market cap: around $209 billion, at roughly 19x earnings.
Ramp at $60 billion is valued at about 12 times BILL’s entire market cap, for a business with similar scale revenue and no public profitability disclosure.
What the Competitive Map Looks Like
Ramp’s closest rival, Brex, exited the independent-company race entirely. Capital One completed its acquisition of Brex in April 2026 in a deal valued at about $5.15 billion at signing. That deal closed less than six months ago. Brex, which once dreamed of its own nine-figure valuation, landed at roughly $5.15 billion. Ramp is now priced at about 12 times that outcome.
The gap is not necessarily irrational: Ramp’s payment volume growth and revenue scale are meaningfully larger. But the Brex exit is a useful anchor for what a strategic buyer actually paid for a direct competitor, with full information, just months ago.
Bull / Base / Bear
Bull: Ramp converts its AI tooling into a durable cost advantage, moves upmarket into enterprise, and eventually monetizes at margins that justify a software-style multiple. An IPO at 20x-plus forward revenue is not impossible in a hot window.
Base: Ramp grows into its valuation over four to five years, goes public at a meaningful discount to today’s private mark, and early-round investors do fine. Late-round investors at $60 billion wait a long time.
Bear: Payment volume growth decelerates as the SMB market tightens. Interchange economics compress under regulation. AmEx and Capital One’s Brex unit use balance-sheet advantages to undercut on price. The $60 billion becomes a ceiling, not a floor.
Action Plan
You cannot buy Ramp. You can buy BILL at about 3.1x trailing revenue with 80%-plus non-GAAP gross margins, a $1 billion share repurchase authorization, and earnings next on October 29. You can buy AXP at about 19x earnings, with total billed business up 9% year-over-year in Q2 and a dividend that rose 16% this year.
Neither is a screaming bargain today. But both are priced in the universe where multiples are governed by something other than momentum. That matters when the private market’s enthusiasm eventually meets the public market’s patience.
Cheap Investor Checklist
- Ramp annualized revenue: reported above $1 billion as of June 2026
- Ramp revenue multiple at $60 billion: approximately 40x
- BILL revenue multiple at current market cap: approximately 3.1x trailing
- BILL Q4 FY26 non-GAAP gross margin: 81.7%
- BILL non-GAAP net income FY26: $314.8 million
- AXP P/E at current price: approximately 19x
- AXP 2026 full-year revenue growth guidance: 10%
- Brex acquisition value (Capital One, deal announced January 2026; closed April 2026): about $5.15 billion
- Ramp total equity raised through the June 2026 Series F: more than $3 billion
- BILL next earnings date: October 29, 2026
Bottom Line
If Ramp’s AI products genuinely transform business finance, the $60 billion is the beginning of the story. If they do not, that multiple has a very long way to fall. The bargain hunter does not need to bet on which outcome is right. The public alternatives are already priced for much lower expectations, they are profitable, and you can buy them this afternoon.