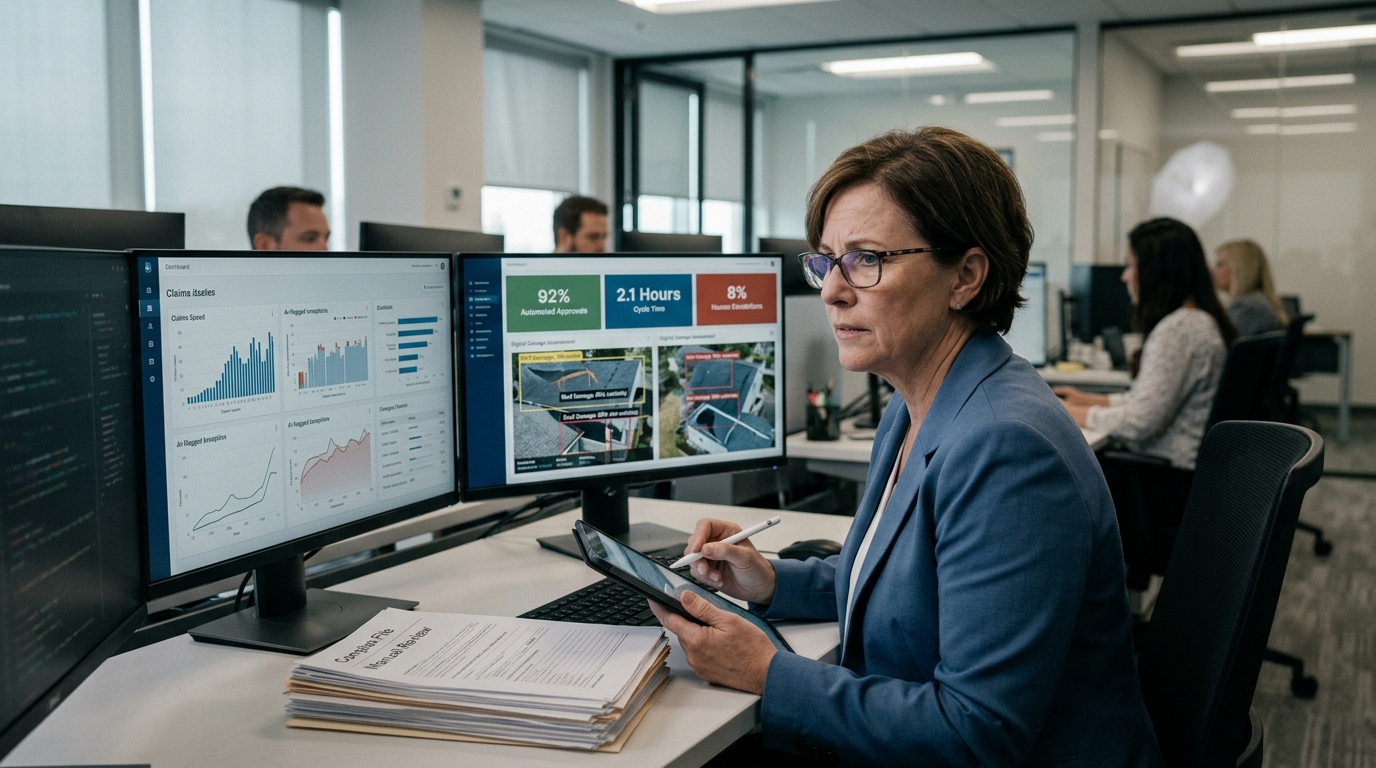
The shift in insurance claims is no longer a pilot program. It is a production reality generating material savings, and the economics are forcing every mid-market carrier to decide whether it moves now or gets priced out of competitive loss ratios.
Where the numbers actually sit:
- Insurers deploying claims automation are reporting materially faster cycle times and lower handling costs, but results vary widely by line of business, claim complexity, and how much of the workflow is truly straight-through versus routed to humans.
- Claims vendors and insurer case studies often cite single-digit-dollar marginal costs for highly automated, high-volume workflows. However, there is no widely accepted 2026 cross-industry benchmark showing property and casualty per-claim processing costs compressing from $15–$22 to $3–$5 across carriers on an apples-to-apples basis.
- Aviva has described deploying dozens of AI models across parts of claims with its partners, including QuantumBlack. Specific figures such as “23 fewer days,” “30% better routing accuracy,” “65% drop in complaints,” and “more than £60 million in 2024 alone” are not corroborated in broadly accessible Aviva primary disclosures, so treat those as directional rather than settled fact.
- Tractable has reported processing claims for major carriers including AXA and Ageas. Public market trackers and company coverage put its total funding at roughly $185 million following its July 2023 round.
- Lemonade has publicly highlighted a world-record claim settlement time measured in seconds for a small, qualifying claim handled end-to-end by its “AI Jim” flow. The widely reported record is three seconds, and more recent promotional references cite two seconds, but this is not representative of typical property claims.
- Missed subrogation opportunities have been estimated at roughly $15 billion annually in industry research cited in NAIC-affiliated publications. Vendor-reported lifts and cost reductions vary, and should be treated as vendor claims unless tied to audited carrier outcomes.
- Market-size projections for “AI in insurance” vary by firm and definition. Some research firms project the category growing from around $10–$13 billion in the mid-2020s to roughly $150 billion-plus in the 2030s, but those figures are not a single consensus and the timing differs by source.
The Real Angle: It Is a Profit Transfer, Not a Cost Story
Most coverage frames this as an operational efficiency play. That framing is too narrow. McKinsey has argued that AI leaders in insurance have produced about six times the total shareholder returns of AI-laggard peers over a five-year window. That is not just an efficiency gap. It is a compounding competitive moat.
Deep learning models trained on large image sets can assess damage severity and estimate repair costs by integrating with estimating and parts and labor databases, feeding a preliminary assessment into downstream business rules within seconds. For defined low-severity segments, some carriers report majority-straight-through handling, but 60% or more should be read as a top-end outcome, not an industry baseline.
The subrogation angle is where the least-covered money sits. Automated subrogation can identify, score, and pursue third-party recovery, and NAIC-linked research has cited estimates that missed subrogation opportunities may cost the industry roughly $15 billion annually. Vendors often report meaningful pursuit-cost reductions, but the realized lift depends on claims mix, documentation quality, and recovery partner execution.
The Workforce Question Is More Nuanced Than It Looks
At carriers that have rolled out AI across parts of claims, the common pattern is not full elimination of adjusters. The work shifts away from data assembly and routine routing toward complex, contested, and emotionally charged cases where human judgment genuinely matters. Claims involving bodily injury typically default to human review by design.
That restructuring does not mean headcount is stable industry-wide. Junior adjuster roles handling routine intake and valuation face direct substitution pressure. Senior roles overseeing complex liability and fraud investigation are gaining leverage.
Trading Framework
The public market exposure here is indirect but real. Carriers posting weak underwriting economics are the most motivated buyers of claims automation platforms. Verisk benefits from higher claims data throughput across the ecosystem. Guidewire’s cloud platform underpins many workflow modernization efforts that carriers and systems integrators are tying into AI-assisted triage and decisioning.
Preparation, not prediction, is the discipline. Watch Q3 earnings from Travelers, Allstate, and Progressive for explicit combined ratio improvement attributed to claims technology and severity management. Any carrier posting a meaningful year-over-year drop in loss adjustment expense as a percentage of earned premium deserves a closer look at whether that compression is structural or cyclical.