October 7, 2026
They called it a premium. Public shareholders called it a panic. Here’s who was right.
Hey there, bargain hunter. Option Care Health spent most of 2026 being ignored. The stock hit $36.80 in January, got crushed about 24% on a weak Q1 earnings report in April, spent the summer drifting in the low $20s, and closed October 5 at $23.37. Then Tuesday morning arrived.
World’s Largest Investors Are Moving Their Money (Not Into AI)
While the media distracts you with stories about the next big AI IPO… The world’s largest investors are moving their money into one asset – at the fastest pace in a generation. This asset has crushed the S&P 500’s return over the past 12 months… More than TRIPLED the S&P 500’s return in 2025… and has outperformed the S&P 500 over the past 25 years by more than 1,100 percentage points. According to one Wall Street veteran, with over 40 years of professional investing experience… the biggest gains could be still ahead. That’s why he’s urging you to make one money move now.
Scoreboard
OPCH surged 34% intraday after CD&R and McKesson announced a definitive agreement to acquire the company for $32.05 per share in cash, implying a total enterprise value of approximately $5.8 billion including debt. The offer represents a 37% premium to OPCH’s October 5 closing price. Shares settled near $31 by end of day. McKesson will invest roughly $1.4 billion for a 49% stake, with CD&R holding the majority 51%. Closing is expected in the first half of 2027, pending shareholder and regulatory approvals.
The Real Reason
The 37% premium sounds generous until you remember where OPCH was trading nine months ago. At $32.05, CD&R and McKesson are paying $4.75 below the 52-week high of $36.80, set in January. Public shareholders who panicked after the Q1 miss and sold in the low $20s handed this deal to two sophisticated buyers at a steep discount to where the stock had been, and arguably where the business was heading anyway.
The Q1 miss was real: revenue of $1.35 billion grew just 1.3% year over year, while adjusted EBITDA dropped 6% to $104.8 million on headwinds from the chronic inflammatory disease portfolio. Management cut full-year revenue guidance from a range of $5.8 billion to $6.0 billion to $5.675 billion to $5.775 billion. The market punished the stock by about 24% in a single session. That punishment is what created this deal.
What the Business Actually Does
Option Care Health is the nation’s largest independent provider of home and alternate-site infusion services, operating through 87 full-service pharmacies and 109 stand-alone ambulatory infusion suites. It administers complex therapies, including anti-infectives, immunoglobulin, nutrition support, and specialty biologics, outside hospital settings. Revenue has grown from about $3.0 billion in 2020 to $5.65 billion in 2025.
5 Little-Known Stocks Behind Today’s Defense Tech Shift
Behind the headlines, a major transformation is underway.
Modern warfare is being driven by AI, autonomous systems, and next generation technology. A handful of lesser known companies are helping power this shift.
This report uncovers five stocks quietly playing a critical role in the future of defense.
For McKesson, this is a strategic expansion into specialty pharmaceutical delivery beyond the distributor role. The deal gives McKesson a national clinical platform for rare disease and orphan drug therapies. The transaction also establishes a framework for McKesson to eventually acquire CD&R’s 51% stake outright, subject to conditions and regulatory approval. Day one, McKesson accounts for the investment under the equity method. Full consolidation comes later, if it comes at all.
Data Check
- Q2 2026 revenue: $1.44 billion, up 1.9% year over year; adjusted EBITDA of $117.5 million, up 3%
- Full-year 2026 guidance (withdrawn upon deal announcement): revenue of $5.675 to $5.775 billion; adjusted EBITDA of $480 to $495 million
- Q2 operating cash flow: $184 million; net debt to EBITDA: not disclosed in the earnings release
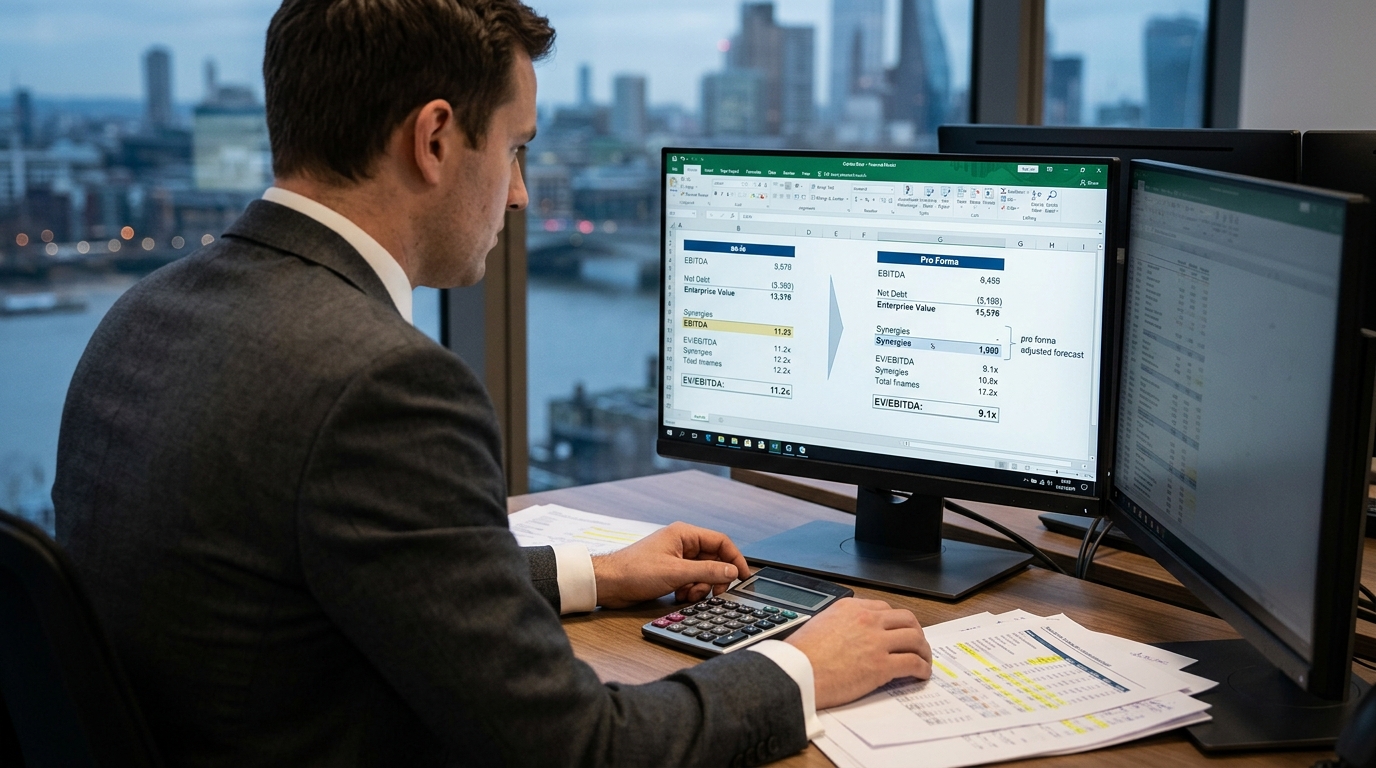
- $32.05 acquisition price represents roughly 11.8x the midpoint of 2026 EBITDA guidance
- Deal financing committed by Bank of America, Barclays, Goldman Sachs, Jefferies, and Wells Fargo
Is It Cheap?
At roughly 11.8x EBITDA, this is not an expensive deal for a business guiding to $480 million or more in annual adjusted EBITDA with cash flow from operations of at least $320 million. Home infusion is a durable, recurring-revenue model with demographic tailwinds. The CID headwinds that cratered the stock were real but arguably temporary, linked to patient census resets and therapy mix shifts rather than structural demand destruction. CD&R and McKesson are buying at a moment of maximum pessimism from public holders. That is not an accident.
Bull / Base / Bear
Bull: McKesson eventually acquires CD&R’s stake at a premium to $32.05, making the takeout price look conservative in hindsight. Home infusion volumes recover, EBITDA approaches $500 million, and the strategic value justifies a higher full buyout.
Base: Deal closes in H1 2027 at $32.05 as agreed. OPCH shareholders collect their cash and redeploy elsewhere. McKesson builds out the platform quietly before deciding on full consolidation.
Nuclear Energy’s Comeback Could Spark Before 2026
Global energy demand is surging and one overlooked power source is quietly returning to the spotlight. New policy support and supply constraints are setting the stage for a surprising shift in the energy markets.
Bear: Regulatory friction or a shareholder vote rejection delays or derails the deal. Shares revert toward pre-announcement levels in the low $20s. At that point the business fundamentals, not the deal, have to carry the load.
Action Plan
OPCH is now essentially a closed arbitrage. Shares are trading near $31, against a deal price of $32.05 with an expected close in H1 2027. That spread implies a modest annualized return, appropriate only for investors with tolerance for deal-break risk. There is no compelling reason to buy here unless you are running a merger-arb book. For everyone else, the trade was in the $20s, and that window closed Tuesday morning.
Cheap Investor Checklist
- Deal price vs. 52-week high: $32.05 vs. $36.80. Sellers left money on the table.
- EBITDA multiple: approximately 11.8x. Reasonable for a durable, recurring-revenue healthcare platform.
- McKesson buyout framework: optionality for full consolidation embedded in the structure.
- Financing: five major banks committed. Execution risk is low.
- Q2 momentum: revenue, EBITDA, and EPS all beat estimates after the Q1 miss. The business was stabilizing.
- Regulatory risk: specialty pharma distribution plus home infusion under one roof may attract scrutiny.
- Shareholder vote: unanimously approved by OPCH board. No activist opposition yet.
- Timeline: H1 2027 close expected. Roughly six to nine months of hold for arb players.
Bottom Line
If the deal closes at $32.05, CD&R and McKesson bought one of healthcare’s most durable recurring-revenue platforms at a price that public shareholders had already seen at $36.80 earlier this year. The 37% premium felt generous to a market that panicked in April. In two or three years, if McKesson exercises its option to take the rest, $32.05 will probably look like the real bargain in this transaction.