September 22, 2026
Bonus Content: Oura’s IPO Math: Who Actually Gets the $2.2 Billion
Marvel was valued at $54 billion. Star Wars at $181 billion. And Pokemon at $115 billion.
What do they have in common? IP with a passionate fanbase.
And that’s great news for companies like Skybound Entertainment.
Skybound is one of the few companies that have successfully struck deals with major streamers and studios while keeping 250 of their own IP properties and the profits across gaming, merchandise, and licensing.
The opportunity to own a piece of it closes soon.
Here’s how they use that IP to create global franchises: They create the comics, where audience response helps shape their next breakout hits, then scale the strongest stories through TV and film, and monetize through releasing games, merchandise, and more. The Walking Dead and Invincible are just two big names in their portfolio.
Now you can own a piece of what’s next. Final days to invest before the opportunity ends.
Oura’s IPO Math: Who Actually Gets the $2.2 Billion
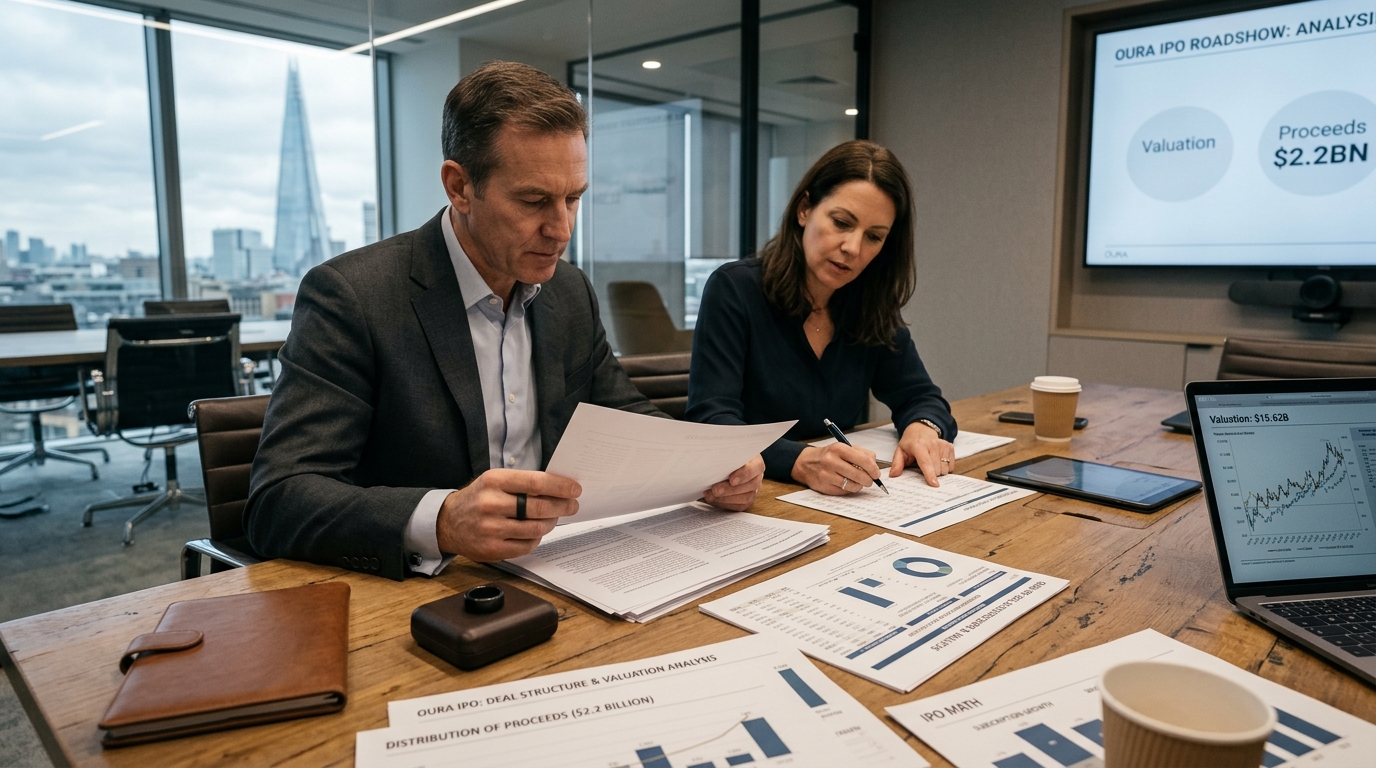
Hey there, bargain hunter. A Finnish-American ring company just kicked off autumn’s most closely watched IPO roadshow, and the headline figure deserves a closer look before you reach for the buy button.
Scoreboard
Oura launched its roadshow Monday, targeting a fully diluted valuation of $15.62 billion through the sale of 50 million shares priced between $40 and $44, which would raise as much as $2.2 billion. Cornerstone demand is already visible: Eli Lilly has signaled interest in up to $100 million worth of shares and Dragoneer up to $300 million. Pricing is expected during the week of Monday, September 28, 2026.
What Actually Happened
Read the deal structure before you read the growth rate. Of the 50 million shares on offer, Oura is selling only 13.5 million new shares. Existing shareholders are offloading the remaining 36.5 million. At the $42 midpoint, that translates to roughly $1.53 billion for the selling shareholders and $567 million for the company, before fees.
Then it gets tighter. Oura says it intends to use approximately $526.4 million of its net proceeds to satisfy anticipated tax withholding and remittance obligations tied to RSUs that vest at the time of the IPO, with the remainder for general corporate purposes. That means the “general use” slice is modest unless the offering terms change.
Forerunner Ventures, Oura’s second-largest shareholder, plans to sell its entire 9.3% stake of roughly 28.7 million shares for approximately $1.20 billion, assuming the IPO prices at the midpoint. Forerunner first backed Oura in the company’s 2020 Series B. Good for them. Less relevant to you.
The Business Behind the Ring
The Oura Ring is a sensor-equipped device worn on the finger. Optical sensors read blood flow, heart rate, body temperature and movement through the night, and the app converts those readings into sleep, activity and readiness scores. Buyers own the hardware outright, but the full app sits behind a paid membership, meaning each ring can earn revenue twice.
Data Section
- Revenue for the nine months ended June 30, 2026: $1.2145 billion, up 74% from $697.6 million in the prior-year period.
- Hardware accounted for about 80% of revenue; membership subscriptions contributed about 20%.
- Membership revenue reached $240.5 million, a 121% increase, with paid members doubling to 5.0 million.
- Membership gross margin was 89%. Historically, over 94% of ring activations convert to paid members and weighted-average 12-month paid member retention is approximately 85%.
- Net income was $60.8 million for the nine months ended June 30, 2026, versus $12,000 for fiscal 2025.
- Cash and cash equivalents were $371.8 million as of June 30, 2026.
- Oura expects to end fiscal 2026 with approximately 5.7 million paid members, representing 96% year-over-year growth.
Is It Cheap?
Oura’s projected $2 billion in 2026 sales imply an estimated 8x forward revenue multiple at the $15.62 billion valuation. That is a software-style multiple on a business that is still about 80% hardware by revenue. The subscription layer earns it some of that premium: 89% gross margins, about 85% 12-month retention, and historically over 94% activation-to-paid conversion. Those numbers are genuinely strong.
The peer set is thin. Whoop, the closest rival in screen-free wearables, raised $575 million in a March 2026 Series G at a $10.1 billion valuation, but has not yet tested that number in public markets. Samsung’s Galaxy Ring is a direct competitor that does not require a subscription fee for its core experience, which applies ceiling pressure on what Oura’s $5.99-per-month plan can sustainably charge. Garmin and Apple report wearable revenue inside larger segments, making a clean multiple comparison difficult.
Bull / Base / Bear
Bull: Subscriptions grow faster than hardware, pulling revenue mix toward 89%-margin software. The 5.7 million member target proves out, international expansion adds a second growth leg, and Eli Lilly’s $100 million cornerstone interest signals healthcare system integration ahead.
Base: Oura prices at or near $42, trades in a tight range, and becomes a watch-and-wait for the first quarterly report as a public company. Growth decelerates modestly from the 74% pace as the addressable base matures.
Bear: Samsung’s subscription-free Galaxy Ring raises the feature-parity question: if consumers can get comparable biometric tracking at no monthly cost, what is Oura’s $5.99 plan actually worth? Add a jittery macro backdrop, and 8x forward revenue leaves little room for a miss.
Action Plan
Do not chase the open. Markets have been sensitive to bond yields and the path of Federal Reserve policy, and the heavily secondary nature of this deal means many of the people who know this company best are the ones selling. Wait for the first post-IPO quarter. A confirmed acceleration in subscription mix toward 25% or more of revenue, at the current margins, changes the valuation math meaningfully. If that report comes and the stock has not moved far above the offering price, that is the entry point worth sizing.
Cheap Investor Checklist
- Subscription revenue as a percentage of total: watch for sustained move above 20%
- 12-month paid member retention: holding at or above 85%
- Hardware-to-paid-member conversion rate: any slip below 90% is a warning
- Paid member count vs. guidance of 5.7 million by fiscal year-end
- Samsung Galaxy Ring churn data: any evidence of competitive substitution
- International revenue share: currently under 20%, expansion is the bull case
- Post-IPO operating expense growth vs. subscription revenue growth
- First public-market gross margin disclosure: membership line must hold near 89%
Bottom Line
If Oura’s subscription mix reaches 30% of revenue within two years and retention stays above 80%, the 8x forward multiple looks defensible. If Samsung’s free alternative slows member growth and the revenue split stays stuck at 80/20, you are paying a software price for a hardware business. The IPO itself tells you something: most of the proceeds flow to the sellers, and the company’s intended use of proceeds is dominated by IPO-related employee tax withholding rather than growth spending. That is not a reason to avoid the stock long-term. It is a reason to let them finish selling first.