Something strange is happening to your money.
It wasn’t voted on. It wasn’t debated in the Senate. And most Americans have no idea it’s even taking place but…
President Trump is replacing the U.S. dollar.
Not with crypto. Not with a digital currency. Something far bigger than that – and it’s already been signed and sealed in the back rooms of D.C., ready to be issued by the U.S. Treasury.
Bypassing every legal and political channel under the guise of “national security,” Trump has enacted this total money reset using a landmark executive order (1421).
Whether you’re a Democrat or Republican, whether you support this new money or not, it doesn’t matter.
Soon, every U.S. citizen will be forced to use Trump’s New Dollar to fill their gas tank, buy groceries, and pay medical bills.
Which is why I’ve produced a critical new documentary laying out exactly what Trump’s New Dollar means for your savings, your investments, and your family’s financial future.
Detailing three important steps you can take today to prepare – including the name of a core band of assets connected to Trump’s initiative that could surge as a result.
As you’ll see in my briefing, the last time America reset its money like this – under Richard Nixon’s presidency in the 1970s – it created one of the greatest wealth divides in the history of our nation.
On one side, it minted an average of 1,300 new millionaires a day for over half a century. And on the other… the folks left behind, drowning in debt, with no idea how to use America’s new money to create wealth.
As Trump rolls out his new dollar, the question is:
Good investing,
Porter Stansberry
PS. If you’re wondering what Trump’s new money will look like, when it will be issued, what it means for your investments and why it could be front page news on December 14 – all of those questions are answered in my briefing.
Ford’s 5% Dividend Yield Looks Cheap. Here Is What Has to Hold on Wednesday.
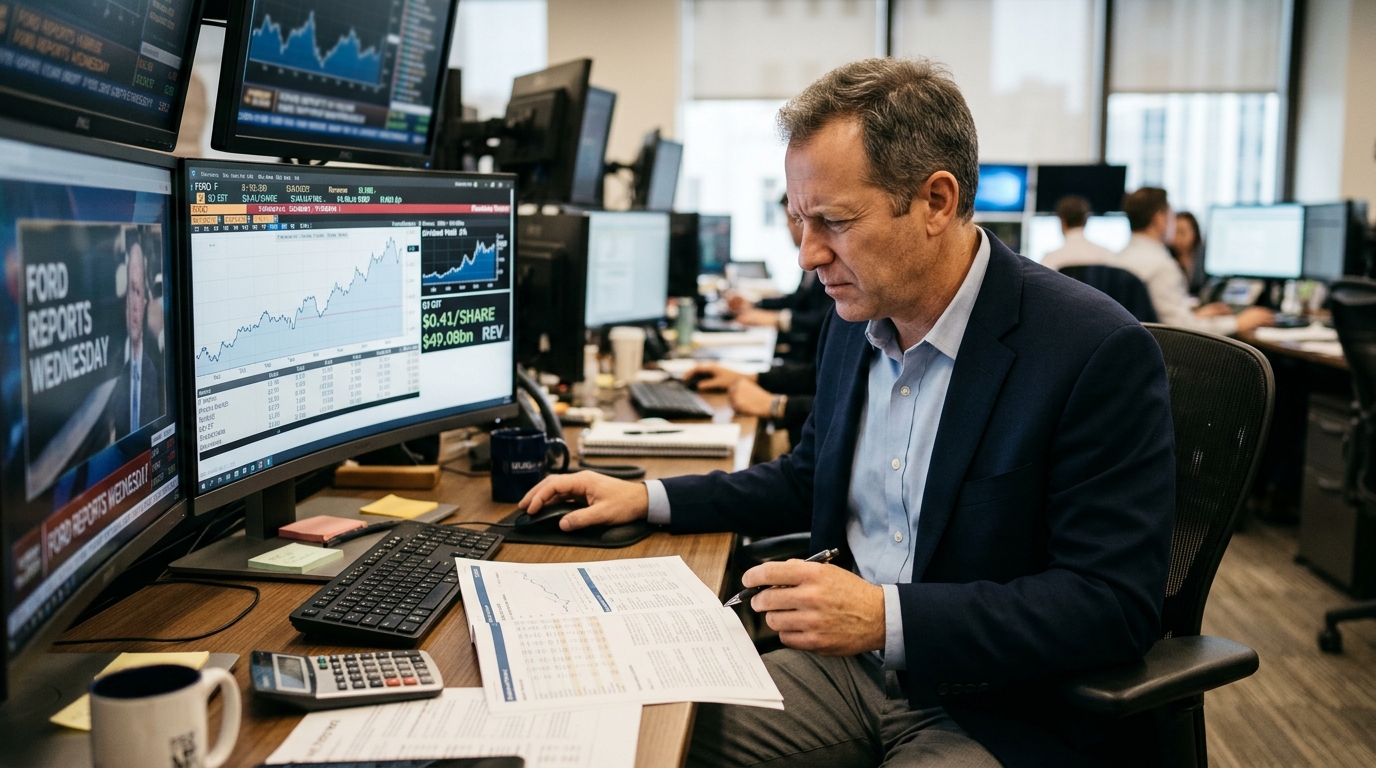
Hey there, bargain hunter. Ford reports Wednesday after the close, and the yield on your screen says 5%. The stock is off nearly 9% year to date and sitting around $11.56. That looks like a discount. But before you call it a gift, let’s run the numbers that actually matter.
Scoreboard
Analysts are forecasting earnings of approximately $0.41 per share and revenue of $49.08 billion for Q3. That compares with $0.45 a share a year ago, a 10% year-over-year decline. Ford already walked through a rough second quarter: Ford Pro generated $1.7 billion of EBIT on $17.8 billion of revenue, down about $600 million year-over-year, as it recovered from temporary Novelis-related aluminum supply constraints. Management raised full-year guidance anyway. They lifted adjusted EBIT guidance to $10.0 billion to $11.0 billion, up from $8.5 billion to $10.5 billion.
The Real Reason This Number Is Complicated
GM just showed you what happens when you beat and still disappoint. Despite raising free cash flow expectations and announcing a $20 billion buyback authorization, GM stock still fell about 7% the day it reported. The read-across is not comforting: before the report, analysts were already looking for roughly $13.4 a share for GM’s full year, slightly above the company’s updated $13.25 midpoint. A guidance miss at the midpoint was enough to wipe out a strong quarter. Ford cannot afford to repeat that.
There is also the October surprise to absorb. F-150 production was affected by a short-term supplier issue at the end of September, unrelated to aluminum, though Ford says the expected financial impact is containable within the $10.0-11.0 billion EBIT guidance. Containable is doing heavy lifting there. It needs to stay that way.
What the Business Actually Looks Like
Strip the company into its three segments and the picture sharpens fast. Full-year guidance calls for Ford Pro EBIT of $7.0 to $7.5 billion, Ford Blue EBIT of $5.0 to $5.5 billion, and a Model e EBIT loss of approximately $4.0 billion, with Ford Credit earnings before taxes above $2.5 billion.
Ford Pro is the engine. Super Duty production reached a 19-year high of 110,275 units in Q3, up 4.4% year over year, while total F-Series production climbed 4.5% to 266,777 units. Software is growing too: active paid subscriptions surpassed 1.7 million through September, up more than 40% year over year.
Ford Pro’s Super Duty volumes are the load-bearing wall of the entire investment case. Ford’s $1 billion commitment to the Kentucky Truck Plant that builds those Super Duty trucks carries its own set of unresolved questions for shareholders.
Model e is the hole in the bucket. The EBIT margin for Model e was -89.6% in Q2, meaning for every dollar of EV revenue Ford brought in, it lost about ninety cents. That is not a rounding error. It is a structural drag on every consolidated metric Ford publishes.
Is the Dividend Actually Safe?
This is the real question, and the answer is more nuanced than the GAAP loss suggests. Ford raised its 2026 adjusted free cash flow guidance to $6 billion to $7 billion, and the regular dividend costs about $2.4 billion a year, so guidance covers it roughly 2.5 to 3.0 times. Ford also holds $22.3 billion in cash and $43.4 billion in total liquidity.
Cash is fine, as long as the guided range holds. The risk is the gap between adjusted free cash flow and what actually flows to equity holders once Ford Credit’s capital requirements, capex, and working capital swings are accounted for. Ford Credit is profitable, but it runs its own balance sheet and its distributions to the parent are not guaranteed at any fixed level. Debt-to-equity stands at 4.66 and interest coverage at just 2.02, which is thin margin for a cyclical business in a rising-cost environment.
Bull / Base / Bear
- Bull: Ford Pro recovery accelerates in H2 as Novelis normalizes, Q3 EBIT beats $0.41 consensus, and management holds the $10-11bn guide with conviction. Stock re-rates toward $14-15.
- Base: Q3 comes in near consensus, guidance midpoint holds but raises no further, dividend stays at $0.15 quarterly. Stock grinds sideways, yield compensates patient holders.
- Bear: A second supplier disruption or weaker truck pricing forces a guidance cut. Model e losses do not narrow in Q3. The dividend gets questioned. Stock revisits the 52-week low near $11.11.
Cheap Investor Checklist
- Does Q3 adjusted EBIT exceed $2.5 billion, consistent with a $10-11bn full-year pace?
- Does Ford Pro show sequential EBIT recovery from Q2’s $1.7 billion?
- Is the October F-150 supplier issue fully quantified and confirmed as contained?
- Does Model e loss stay near the $4.0 billion full-year guide or widen?
- Does management reaffirm, raise, or cut the $6-7 billion free cash flow range?
- Is Ford Credit EBT tracking above $2.5 billion for the year?
- Any language on the special dividend, or silence that signals none is coming?
Action Plan
At roughly 6 times forward earnings and a 5% yield covered nearly three times by guided free cash flow, Ford is priced for pessimism. That is not the same as priced to buy. The stock is down 10% over the past month, so even a modest beat could shift sentiment quickly. The GM read-across says a beat is necessary but not sufficient: guidance has to meet or exceed what the market already priced in.
For conservative bargain hunters: wait for Wednesday’s call. If Ford holds the $10-11bn EBIT range and reaffirms free cash flow above $6 billion, the dividend is defensible and the stock has room. Scale in on confirmation, not ahead of it. Trim if guidance gets cut at the midpoint. That is the same trade that burned GM holders this week, and there is no reason to stand in front of it twice.
Bottom Line
Ford’s 5% yield is real, and the cash flow behind it is real. The $10-11bn EBIT promise is also real, but it requires Ford Pro to recover, Model e losses to stay contained, and one more supplier issue to be as minor as management says. If all three hold on Wednesday, the yield is worth collecting. If any one cracks, the GM precedent shows the market will not wait for an explanation.