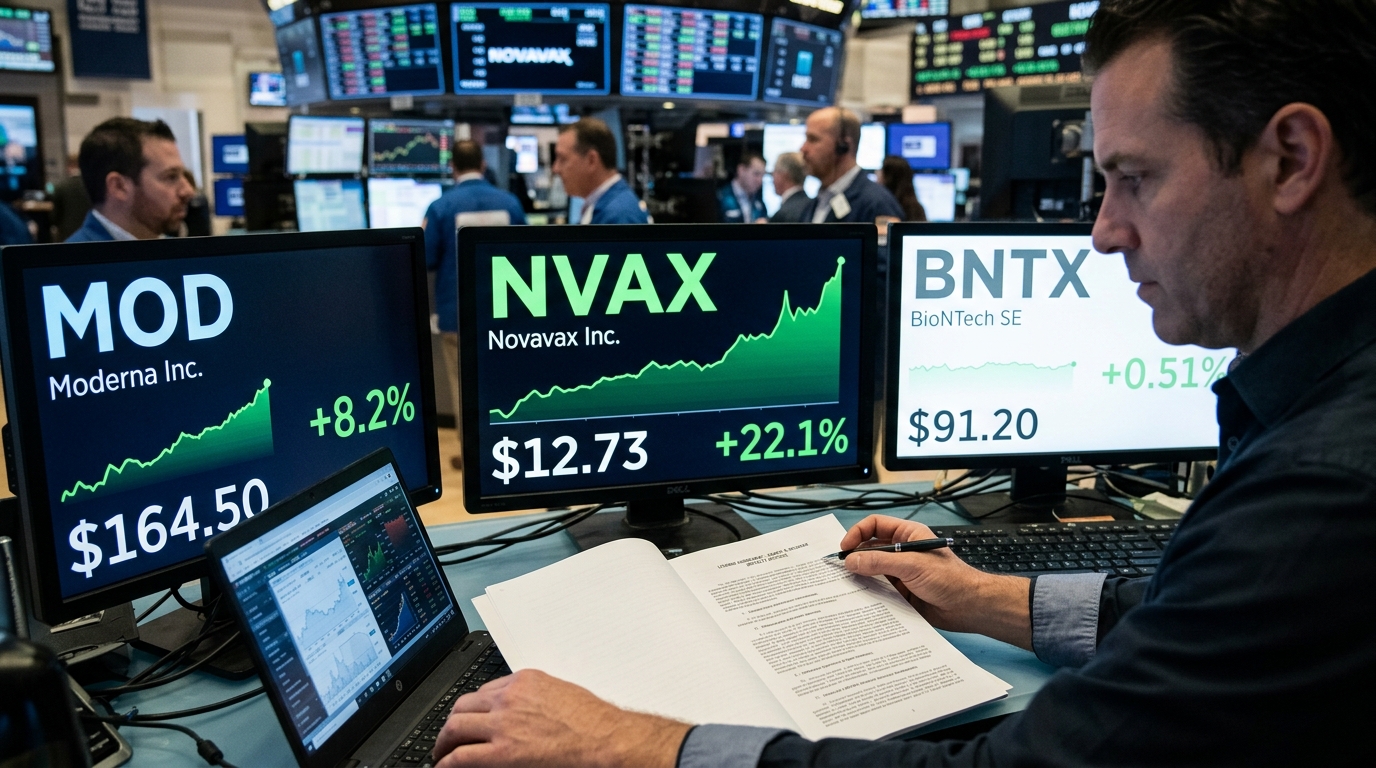
Hey there, bargain hunter. Novavax jumped 22% on Monday and the headline writes itself: Sanofi is expanding Nuvaxovid availability beyond the U.S. to additional markets including the UK, Germany, and Canada, and the licensor is getting paid. The stock hit $12.73 in afternoon trading. Moderna added roughly 8% on its own cancer pipeline news. BioNTech barely moved, up about half a percent. That divergence matters: this was not a sector bid. It was one name, one contract, one season.
Before you chase it, understand what you are actually buying.
What Novavax Actually Is Now
Novavax is no longer a vaccine company in the conventional sense. Novavax transitioned lead commercial responsibility of Nuvaxovid to Sanofi beginning with the 2025-2026 COVID-19 vaccination season for select markets. Sanofi runs the sales operation. Sanofi sets the distribution. Novavax collects a royalty on what Sanofi sells.
Sanofi leads commercial activities for the 2026-2027 COVID-19 vaccination season in select markets, including the US, and Novavax is eligible to receive royalties in the high teens to low twenties percent on Sanofi global net sales. That is the number that determines the actual cash flowing into Novavax this autumn, not the stock price move. High teens to low twenties on an uncertain volume, in a market where COVID vaccine uptake has been declining for years.
The Numbers on the Board
In Q2 2026, when the royalty engine had already been running for a full season, here is what came through: Novavax reported $36 million of revenue in the quarter under the Sanofi line item, and the company describes that category as including upfront payments, milestones, royalties, and transition services reimbursement. That is the royalty model producing a number, but the quarter’s Sanofi-related revenue was not presented as a clean royalty-only figure.
Novavax does not provide guidance on Sanofi supply sales, Sanofi royalties, or Sanofi milestones, citing reliance on partner forecasts. So the market is pricing a 22% move on a revenue line the company cannot even guide to.
The full-year 2026 framework tells a similar story. Novavax’s adjusted total revenue guidance for 2026 sits between $235 million and $275 million, with Nuvaxovid product sales expected at $35 to $45 million. Sanofi supply sales, Sanofi royalties, and Sanofi milestones are excluded from that framework.
Bull / Base / Bear
- Bull: Sanofi’s expanded rollout across four major markets drives meaningful dose volume this season, royalties land well above last season’s baseline, and the flu-COVID combination milestone pipeline adds a $225 million payment upon first commercial sale of a Sanofi combination product.
- Base: COVID vaccine uptake stays sluggish, royalty revenue is incremental rather than transformative, and the stock drifts back toward the $10 range after the seasonal excitement fades.
- Bear: Unlike Moderna and BioNTech, Novavax earns royalties from Sanofi’s sales rather than direct revenue, which limits both risk and reward. If Sanofi’s campaign disappoints in any of the four markets, Novavax has no lever to pull. The stock was below $11 last week.
Is It Cheap?
At $12.73 post-spike, Novavax trades at roughly 4 to 5 times its guided adjusted revenue. That sounds modest until you remember the company deliberately excludes Sanofi supply sales, royalties, and milestones from its own guidance, because it cannot forecast them. You are paying for upside you cannot model. That is a speculation, not a value position.
As of June 30, 2026, Novavax remains eligible to receive additional development, technology transfer, launch, and sales milestone payments totaling up to $425 million from Sanofi. That is a real option. It is also contingent on Sanofi hitting clinical and commercial gates that have not yet been cleared.
Cheap Investor Checklist
- Royalty rate confirmed: high teens to low twenties percent on Sanofi global net sales
- Q2 2026 Sanofi line item: $36 million (includes upfront, milestones, royalties, and transition services reimbursement)
- 2026 adjusted revenue framework: $235M to $275M, excluding Sanofi supply sales, royalties, and milestones
- Milestone pipeline still outstanding: up to $425M from Sanofi, including $75M manufacturing technology transfer milestone expected in mid-2027
- Markets covered: US plus additional markets including the UK, Germany, and Canada for the 2026-2027 season
- Peer move check: Moderna +8% on separate catalyst, BioNTech about +0.5%; Novavax move was company-specific
- Guidance transparency: Novavax provides no guidance for Sanofi supply sales, royalties, or milestones due to partner-forecast dependency
Bottom Line
If Sanofi moves real volume across four markets this autumn and royalty dollars show up in the Q3 report, the rally has a foundation. If uptake disappoints, the 22% is borrowed from a future that does not arrive. Buy only if you can size a position that survives a return to $10, treat it as a royalty stub with option value attached, and set a firm watch on the Q3 earnings line where Sanofi-linked revenue will finally show its hand.