Hi, Tim Plaehn here.
Nvidia is one of the biggest winners of the AI boom.
But if you bought it for income…
You’d collect a dividend yield of about 0.5% a year.
I found another way to collect income from AI stocks like Nvidia…
Using one small fund that pays investors every single Thursday.
Its annualized distribution rate has been 34%.
And it could deliver up to $1,051 in a single month.
To your income,
Tim Plaehn
Chief Income Strategist
Investors Alley
Ford’s $17.7B Warranty Reserve Is the Number Wall Street Keeps Glossing Over
Hey there, bargain hunter. Ford just beat Q3 earnings estimates and raised the low end of its full-year guidance. The stock traded higher. Most of the coverage moved on. You should not.
Scoreboard
Ford generated $2.7 billion in Q3 adjusted EBIT and narrowed its 2026 guidance to $10.5 billion to $11 billion, up from a prior range of $10 billion to $11 billion. That is a real improvement. But underneath it sits a balance sheet item that keeps growing quietly.
The Number That Deserves More Attention
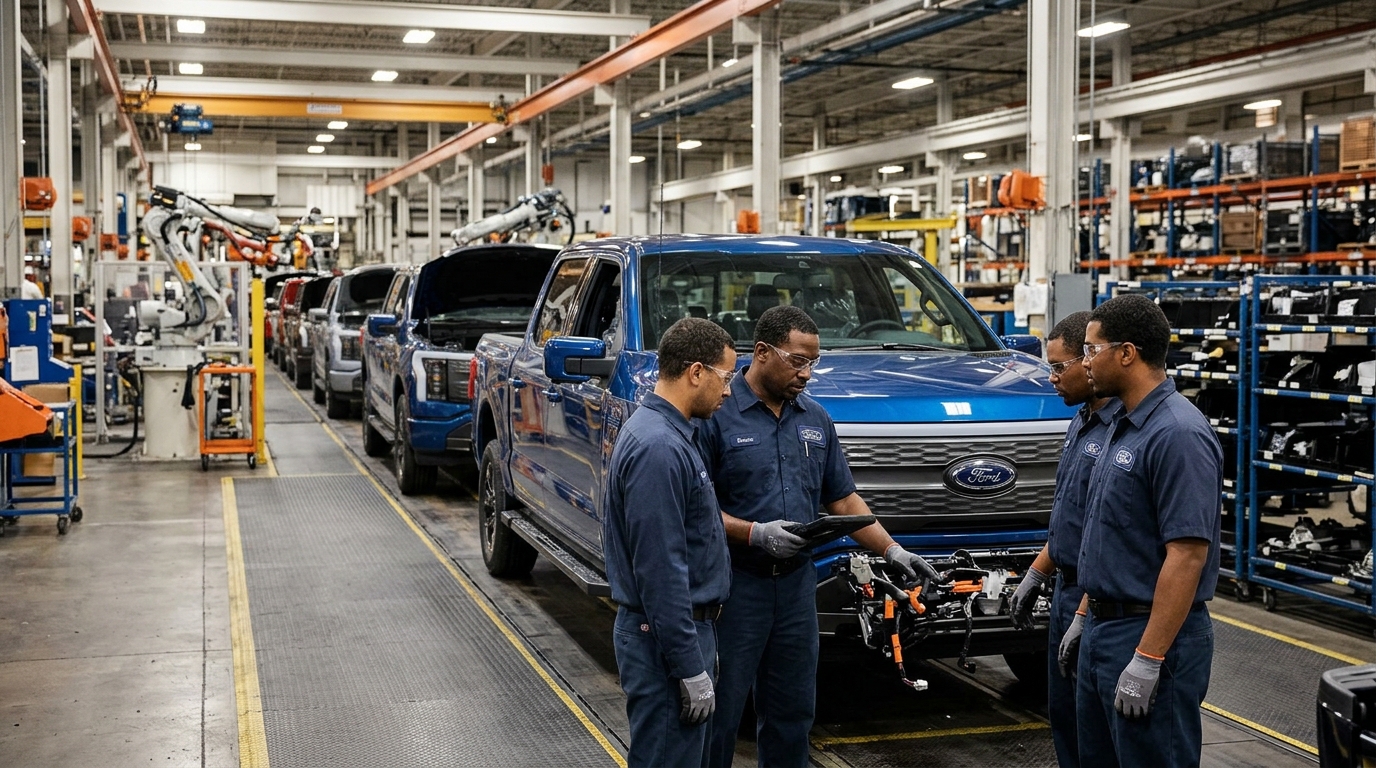
Warranty and field service action reserves rose to about $17.7 billion as of September 30, 2026, from about $17.2 billion at year-end 2025. That is not a rounding error. It is roughly a $500 million increase over the first nine months, on top of a reserve base that was already historically elevated. The company also flags reasonably possible additional costs of up to about $1.8 billion beyond what is already accrued.
Ford is not the only legacy automaker where a low headline multiple masks a more complicated story underneath. Stellantis trades near ten-year lows at roughly 5-6x forward earnings, yet AOI margins of 1.8% raise the same cheap-versus-value-trap question.
Ford has promised $1 billion in combined material and warranty savings in 2026. The warranty accrual line for pre-existing issues did fall, from $1,586 million in the first half of 2025 to $475 million in the first half of 2026, which suggests progress. But reserves still climbed. New claims are replenishing the pool faster than old ones drain it.
The EV Side Is Messier Than the Headlines
Model e posted a $1,058 million EBIT loss in Q3 2026, with an EBIT margin of negative 86.5%. Wholesale units fell 31% year over year, primarily reflecting the discontinuation of the current-generation F-150 Lightning and right-sizing of Mustang Mach-E production. Ford projects Model e will lose about $4 billion for the full year. That is capital permanently spent on a segment still bleeding at nearly 87 cents on every revenue dollar.
Where Ford Actually Makes Money
Ford Pro is guiding to $7 billion in EBIT for the full year, and Ford Blue to $5.5 billion. Those two segments are carrying everything. The F-Series is doing the heavy lifting: it captured the highest retail share among full-size truck brands and is on pace for its 50th straight year as America’s best-selling truck. Software and parts revenue hit a record in Q3, which adds a recurring-revenue layer the market is only beginning to price.
Bull / Base / Bear
- Bull: Warranty costs genuinely stabilize in 2027, the Universal EV platform ramps with better margins, and Ford Pro stays above $7 billion annually. The stock re-rates toward the analyst consensus target near $15.
- Base: EV losses hold near $4 billion through 2027 while warranty reserves creep higher. Management has said it expects 2027 core profitability to be roughly in line with 2026, which is not a growth story.
- Bear: The $1.8 billion in flagged additional warranty risk materializes, commodity costs rise, and Ford Pro margins compress. At that point a 5% dividend yield becomes the thing you are clinging to, not the catalyst.
Cheap Investor Scorecard
- Warranty reserves: watch for any quarter where the balance falls, not just accrual rates
- Model e EBIT margin: needs to move from -87% toward -50% before 2028 to validate the investment thesis
- Ford Pro EBIT: the $7 billion target is the floor; anything below is a warning
- Free cash flow: Ford maintained its adjusted free cash flow guidance of $6 billion to $7 billion, which still covers the dividend with room
- 2027 guidance: flat is not cheap enough to ignore the risks above
Bottom Line
If warranty costs stabilize and Ford Pro holds $7 billion, this stock is underpriced at roughly 10 times earnings. If the $1.8 billion in flagged additional warranty risk lands and EV losses persist through 2028, that discount is earned. The Q3 beat was real. So is the reserve pile. Watch the balance sheet, not just the adjusted number.
The regulatory backdrop also matters for how Ford allocates capital between its EV and ICE segments going forward. Washington’s rollback of fuel economy standards to model year 2022 levels reshapes the compliance math for every automaker still deciding how fast to electrify.