October 5, 2026
Bonus Content: AkzoNobel Sold Its Southeast Asia Paints Business for $1.35bn. Was That the Right Price?
Patriots’ Most Trusted Gold Company
Since 2000, Gold Is Up 1,395%. The S&P Is Up 425%.
For U.S. savers age 55+ with $50,000 or more in an IRA, 401(k) or savings. Free of charge, no obligation to buy anything.
Same twenty-six years. Same two dot-com and 2008 collapses. Two very different lines on the chart.1,2 Most Americans have never seen them put side by side – and almost nobody was told they are allowed to hold the better-performing one inside a retirement account.
Two lines on the same chart
In December 1999 gold traded near $290 an ounce and the S&P 500 closed the year at 1,469. Since then gold has multiplied roughly fifteen times over. The S&P has multiplied about five.1,2
Be fair about the comparison: that S&P figure is the price index and does not include reinvested dividends, which would lift it meaningfully.2 Even allowing for that, the gap over a quarter century is not a rounding error.
The reason has less to do with gold than with the dollar. Over those same twenty-six years the money supply expanded, two crises were met with emergency printing, and the national debt crossed $40 trillion. Gold did not get more valuable so much as dollars got less so – and gold is the one asset that cannot be issued by anybody.
Right now gold sits below its January 2026 peak while the world’s central banks keep adding more than a thousand tons a year, and published bank targets still run from roughly $4,900 to $6,300.3,4 Those are opinions, not promises. But a quiet stretch is a better time to read up than a panic. Get the free 2026 Gold IRA Guide.
The free 2026 Gold IRA Guide walks through exactly how a rollover from an IRA, 401(k) or TSP works, which metals the IRS allows, how insured depository storage works, and the mistakes that cost retirees the most. It is free and it takes about thirty seconds to request.
Claim Your Free 2026 Gold IRA Guide →
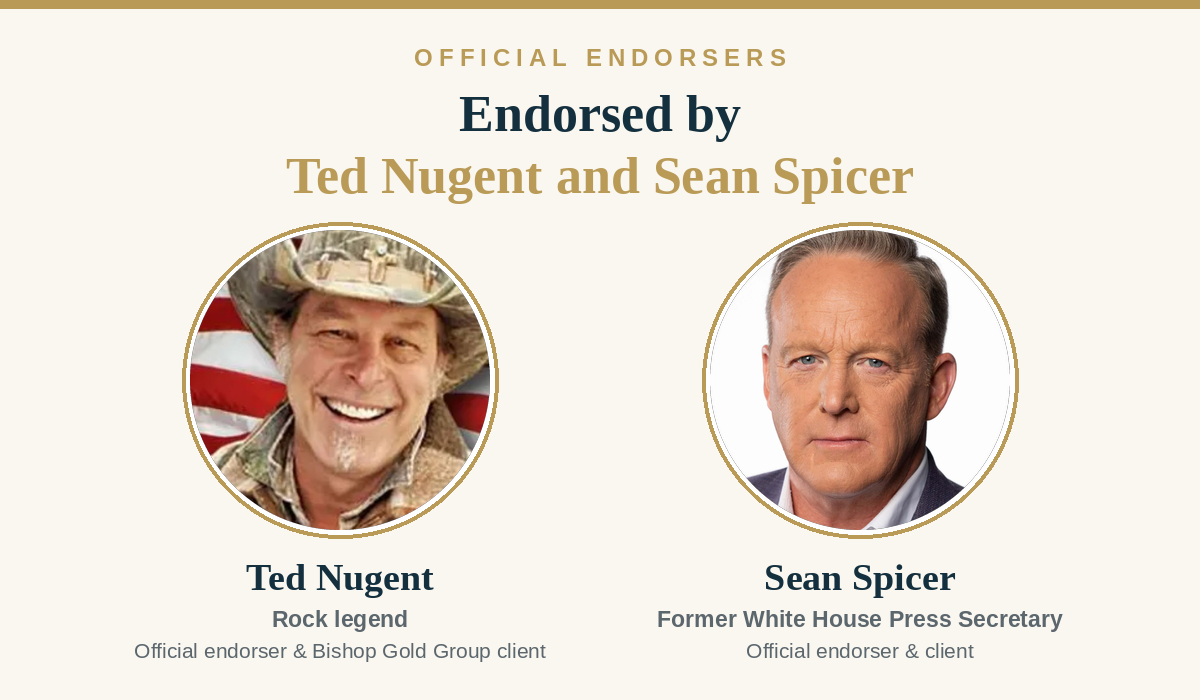
Rock legend Ted Nugent and former White House Press Secretary Sean Spicer are official endorsers and clients of Bishop Gold Group. 10 years in business ⢠5-star rated on Trustpilot and Google ⢠Mint Authorized Dealer
Prefer to speak to someone? U.S.–based specialists, no pressure, no jargon.
Mon-Fri ⢠7am-5pm PT
Sources
1 LBMA gold price, 31 December 1999 ($290.25/oz) to September 2026. Past performance is not a guarantee of future results.
2 S&P 500 price index, 1,469.25 close on 31 December 1999 to 7,707 in September 2026 – a price-only comparison that excludes reinvested dividends, which would raise the S&P figure materially.
3 Published year-end gold price forecasts as reported 2026: Goldman Sachs, J.P. Morgan, UBS and Bank of America, spanning roughly $4,900–$6,300/oz. Analyst forecasts are opinions, not guarantees.
4 World Gold Council, Gold Demand Trends, annual central bank net purchases 2022-2024.
Past performance is not a guarantee of future results. Precious metals are volatile and can decline in value. This comparison is historical and is not a prediction or a recommendation to buy or sell any asset.
AkzoNobel Sold Its Southeast Asia Paints Business for $1.35bn. Was That the Right Price?
Hey there, bargain hunter. Here is today’s arithmetic problem: Nippon Paint spent the better part of 2026 trying to buy a specific set of AkzoNobel paint businesses, first by bidding €7.5 billion for the whole decorative paints division in July, and before that by joining Sherwin-Williams on a €12.5 billion all-company offer in April. AkzoNobel said no, twice. Today, Nippon Paint signed a deal to buy a regional slice of that same division for $1.35 billion. That is a different number. The question worth asking: who blinked?
Scoreboard
The deal announced Monday covers AkzoNobel’s decorative paints operations in Vietnam, Indonesia, Malaysia, Thailand, Singapore, Papua New Guinea, and Australia, seven markets, one price tag. At $1.35 billion enterprise value, AkzoNobel expects roughly $1 billion in net cash proceeds after taxes and minority partner payments. Nippon Paint is funding the purchase through bank borrowings and existing cash, with no new share issuance planned. The Indonesian portion closes in late 2026; the remaining six countries complete by mid-2027. AkzoNobel shares traded higher in Amsterdam. Nippon Paint traded higher in Tokyo.
What Actually Happened
The target businesses generated $291 million in revenue in 2025, down from a year earlier. EBITDA came in at $65 million in 2025, also down year-over-year, implying an EBITDA margin of roughly 22%. AkzoNobel is valuing the transaction at about 21 times FY25 EBITDA. Nippon Paint has described it as about 16 times projected 2026 EBITDA. That is not a fire-sale multiple for assets posting declining revenue.
For context on the rejected bids: AkzoNobel turned down €7.5 billion for its entire global decorative paints division, calling the offer a significant undervaluation. It is now selling seven-country operations that generated $291 million in annual revenue in 2025 for $1.35 billion. That tells you the whole division was enormous by comparison and that AkzoNobel was not wrong to reject the partial valuation, but it also tells you Nippon Paint found a price that worked without needing to fight for every market at once.
The Business and Why It Matters
AkzoNobel runs two segments: decorative paints and performance coatings. The decorative side includes the Dulux brand and architectural coatings sold to consumers and contractors. The performance side includes automotive refinish, aerospace, and marine coatings. Full-year 2025 revenue was €10.158 billion.
The Axalta merger, announced on November 18, 2025 as an all-stock deal and approved by Axalta shareholders on August 5, 2026, is the real strategic driver here. The combined entity is targeting approximately $600 million in annual run-rate cost synergies and expects to close in late 2026 to early 2027. Selling the Southeast Asia decorative operations cleans up the portfolio ahead of that closing and generates roughly $1 billion in net cash, which reduces complexity and feeds the special €2.5 billion dividend AkzoNobel has committed to paying shareholders before completion, net of 2026 regular dividends.
Is the Remaining AkzoNobel Cheaper Now, or Just Slower?
This is the real question. AkzoNobel’s current enterprise value sits around €13.5 billion at a trailing EV/EBITDA near 8 times, not expensive on a headline basis versus peers. PPG trades at roughly 11-12 times EBITDA. Sherwin-Williams trades at a premium that requires a long and confident growth view. AkzoNobel at 8 times, pre-Axalta merger close, looks accessible. But with revenue declining year-over-year and the Southeast Asia growth markets now exiting the portfolio, the remaining business skews heavier toward Europe, Middle East, and the Americas, which together made up a little over half of 2025 revenue. That is a slower-growth geographic mix.
Bull / Base / Bear
- Bull: Axalta merger closes on schedule, synergies arrive faster than expected, and the $1 billion in net proceeds from this deal accelerates deleveraging. The combined company trades up to peer multiples.
- Base: Merger closes by early 2027, synergies take two to three years to fully materialize, and the post-sale AkzoNobel trades sideways at current multiples while investors wait for proof.
- Bear: Regulatory delays slow the Axalta closing, Europe-heavy revenue continues to shrink, and the divestiture of Southeast Asia growth assets leaves investors holding a low-growth, high-integration-risk business at a multiple that has nowhere to go.
Action Plan
For Nippon Paint (4612.T), this is a cleaner entry than anything that was on the table six months ago. The company gets established Dulux distribution, production sites, an R&D center in Malaysia, and brand equity across fast-growing markets, funded without diluting shareholders. The accretion case is straightforward at a 16x EBITDA multiple when the buyer already has procurement and logistics infrastructure across Asia.
For AkzoNobel (AKZA.AS), the stock at around 1 times sales and 8 times EBITDA is not obviously expensive. But bargain hunters should wait for Axalta merger close before sizing up, and should watch for any slippage in the late-2026 to early-2027 closing window. The roughly $1 billion in net proceeds is real and accretive to the balance sheet. The growth story got a little shorter.
Cheap Investor Checklist
- Axalta merger regulatory approval status: any delays widen the risk window
- Net cash proceeds timing: Indonesia close in late 2026, rest by mid-2027
- AkzoNobel EBITDA margin trend: H1 2026 adjusted margin at 14.9%, watch for improvement
- Special dividend of €2.5 billion (net of 2026 regular dividends): confirm it survives intact through close
- Nippon Paint leverage post-deal: funded by debt, watch net debt-to-EBITDA after close
- AkzoNobel revenue growth ex-divestitures: is the underlying business stabilizing?
- Southeast Asia decorative paints market growth rate: validates the 16x EBITDA multiple Nippon paid
Bottom Line
If the Axalta merger closes on time and the special dividend lands, AkzoNobel at current levels offers a credible value case with a clear catalyst. If it slips, you are holding a declining-revenue coatings business at a multiple that does not compensate for the wait. Nippon Paint traded a €7.5 billion ambition for a $1.35 billion beachhead. That is discipline, not defeat, and it may prove to be the smarter sequence.