September 18, 2026
Bonus Content: Raiffeisen Fell 9% on a Short-Seller’s Russia Allegations. Here Is What That Actually Costs.
Editor’s Note: For nearly two decades, Whitney Tilson managed money for wealthy investors – growing a hedge fund launched from his spare bedroom into a firm running more than $200 million. Today, at least five billionaires follow his daily research notes. Now, he’s revealing what he believes is Warren Buffett’s final “hidden” legacy move – and three ways to get in early before a newly-IPO’d power company lights the blue touchpaper. See below for the details…
Dear Reader,
I think we can all agree Warren Buffett is one of the greatest investors who ever lived.
He compounded his money at around 20% a year for six decades…
By turning a dying textile mill into the most famous holding company on Earth – one valued at $1 trillion today.
But hardly anyone is paying attention to what I believe is his final – and least understood – bet in the market.
The details are all laid bare in a story ex $200M hedge fund firm manager Whitney Tilson calls “Project Vulcan”… and what it says about Buffett’s last bet is truly astonishing.
For years, Berkshire has been quietly building a dominant position in a niche type of energy production to fuel the AI build-out…
A fuel source The Economist says is “better than nuclear.”
And one the International Energy Authority predicts could be flooded with over $2.5 trillion of investment in the next decade.
It’s been overlooked by mainstream investors for years.
But an imminent power station switch-on – slated for this October – could be about to light the blue touchpaper in this sector.
And now Whitney is sharing all the details on this story… including three ways you could potentially profit before the big money piles in.
Get the full details on Whitney’s 3 “Project Vulcan” plays now.

Sincerely,
Matt Weinshenck
Publisher and Director of Research, Stansberry Research
P.S. The clock started ticking on this opportunity the moment Buffett handed the keys to his empire over to his hand-picked CEO. Watch my presentation now so you don’t get left behind.
Raiffeisen Fell 9% on a Short-Seller’s Russia Allegations. Here Is What That Actually Costs.
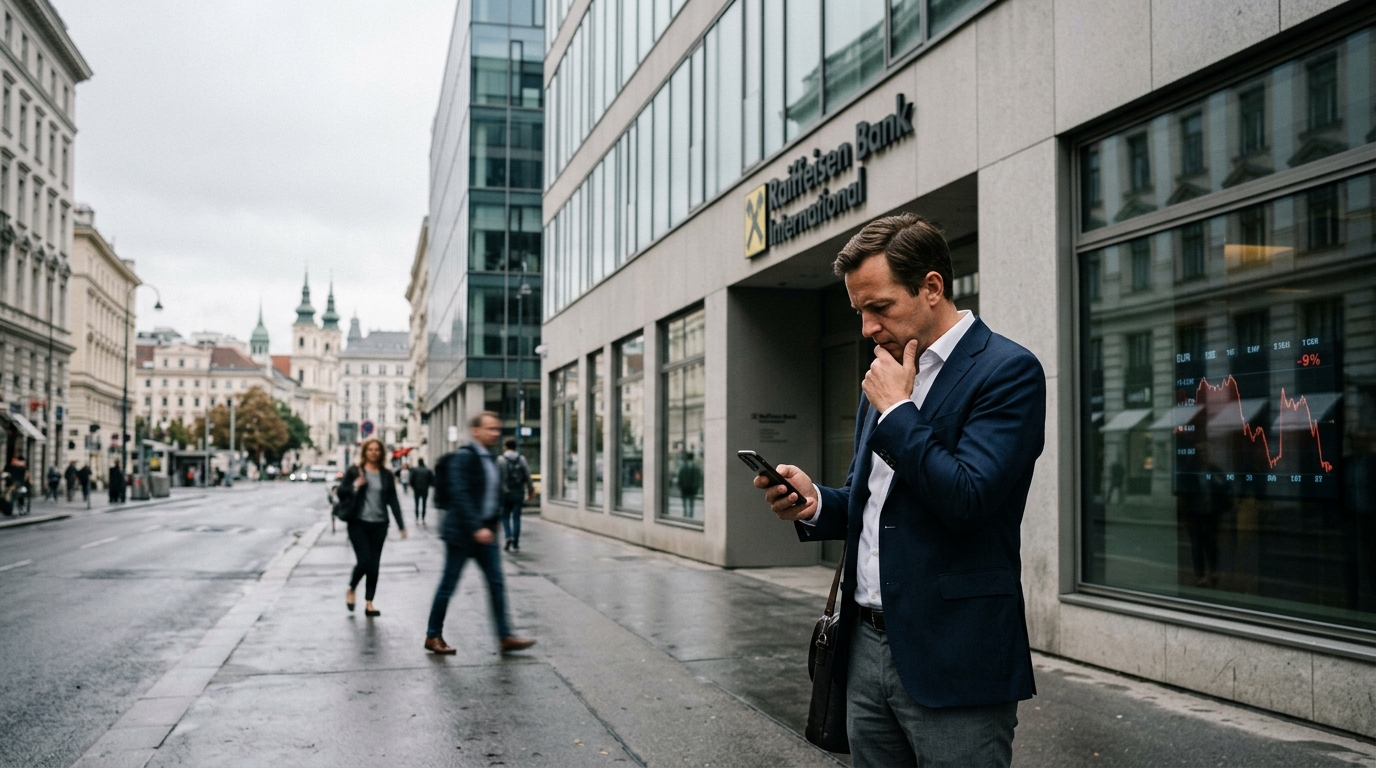
Hey there, bargain hunter. Yesterday a U.S. short-seller named Grizzly Research dropped a report accusing Raiffeisen Bank International of being a conduit for more than a billion dollars in Russian trade tied to Western sanctions. Shares fell as much as 9% in Vienna. By close on Sept. 17, 2026, the stock was trading at 60.95 EUR after pulling back from near an 18-year high reached earlier this month. That kind of single-day drop on a major European bank demands a cold look at numbers, not headlines.
Scoreboard
Grizzly alleges that RBI’s Moscow-based subsidiary, AO Raiffeisenbank, is linked to $1.19 billion in trade in goods that matched sanctions and export-control restriction criteria at the time, under EU, U.S., UK, and Swiss regimes. The report also flags $106.75 million in goods on the Common High Priority List, items associated with Russia’s weapons systems. Grizzly further claims about €12.6 billion in Russian cash and central bank placements is effectively trapped inside Russia’s borders, while RBI has disclosed €735 million in legally restricted cash. RBI called the report misleading, said it contained factual errors, and stated that its compliance systems have been audited repeatedly. Bloomberg Intelligence analysts suggested Grizzly may be exaggerating the sanctions risk.
What Actually Happened
This is not a new story. RBI has been the largest Western bank still operating in Russia since the 2022 invasion. In May 2024, Reuters reported that the U.S. Treasury warned RBI in writing that its access to the U.S. financial system could be curbed over its Russia dealings, a risk described by people familiar with the situation as potentially fatal to the institution. Washington never pulled the trigger. Russian authorities have meanwhile blocked every exit attempt RBI has made, because Moscow wants to keep the bank as a payments channel to Europe. RBI is not stuck in Russia by choice. It is stuck because Russian law will not let it leave.
The Business, Briefly
Strip Russia out and you have a solid Central and Eastern European franchise. RBI reported H1 2026 consolidated profit of €708 million excluding Russia, up 25% year-over-year, and said its CET1 ratio excluding Russia stood at 15.5% as of June 30. The operational picture is still that the core CEE bank is earning money and carrying capital, while Russia remains the headline risk.
Is It Cheap?
At roughly 60.95 EUR, RBI trades at a price-to-book ratio that is around book value based on June 30, 2026 balance sheet figures, depending on how you treat Russia and other adjustments. The European bank peer average sits meaningfully above 1x. The P/E on a trailing basis is under 10x, and peers are generally higher. Even after yesterday’s drop the stock had been approaching an 18-year high, with a 52-week range of 28.02 EUR to 66.75 EUR. The discount investors assign is real and has been there for years, almost entirely because of the Russia overhang. That overhang got louder Thursday.
Bull / Base / Bear
- Bull: Grizzly’s allegations are overstated, regulators take no new action, the CEE franchise continues compounding at a healthy ex-Russia ROE, and the Russia discount eventually narrows as the bank de-consolidates its subsidiary.
- Base: RBI faces a fresh round of regulatory inquiries. Exit from Russia stays blocked. The stock gives back some of its 2026 rally and trades sideways while the bank demonstrates compliance.
- Bear: A sanctions enforcement action materializes, or U.S. dollar access is genuinely threatened. That scenario, described by people close to RBI’s management as existential, is low probability but not zero.
Action Plan
Do not chase the dip today. The Grizzly report is unverified, but it introduces a real regulatory catalyst risk that takes weeks, not days, to price properly. If you want exposure to undervalued CEE banking, a small starter position at current levels is defensible only if you can stomach a further 15 to 20% drawdown in a bad-news scenario. Size accordingly. A full position makes no sense until regulators respond or RBI publishes a point-by-point rebuttal backed by documentation.
Cheap Investor Checklist
- Did RBI publish a detailed written rebuttal to Grizzly’s customs-record claims? (Not yet as of Sept. 18)
- Has any EU or U.S. regulator opened a formal inquiry? (Watch for ECB or OFAC statements)
- Is the €12.6 billion trapped-cash figure confirmed or denied in an official filing?
- CET1 ex-Russia: stays above 14.3% through year-end as guided?
- 2026 NII guidance: still around €4.4 billion?
- Does RBI’s stock recover above 64 EUR within 30 days, signaling market dismissal of the allegations?
- Any new U.S. Treasury communication about dollar access?
Bottom Line
If Grizzly’s core claims are fabricated or legally unsupportable, RBI with a growing CEE franchise can look genuinely cheap. If even a fraction of the sanctions exposure proves actionable, the discount to book is not a floor. It is a warning. Watch what regulators do, not what short-sellers say. That is what moves the stock from here.