October 11, 2026
Here is what the stocks are actually worth without that tailwind
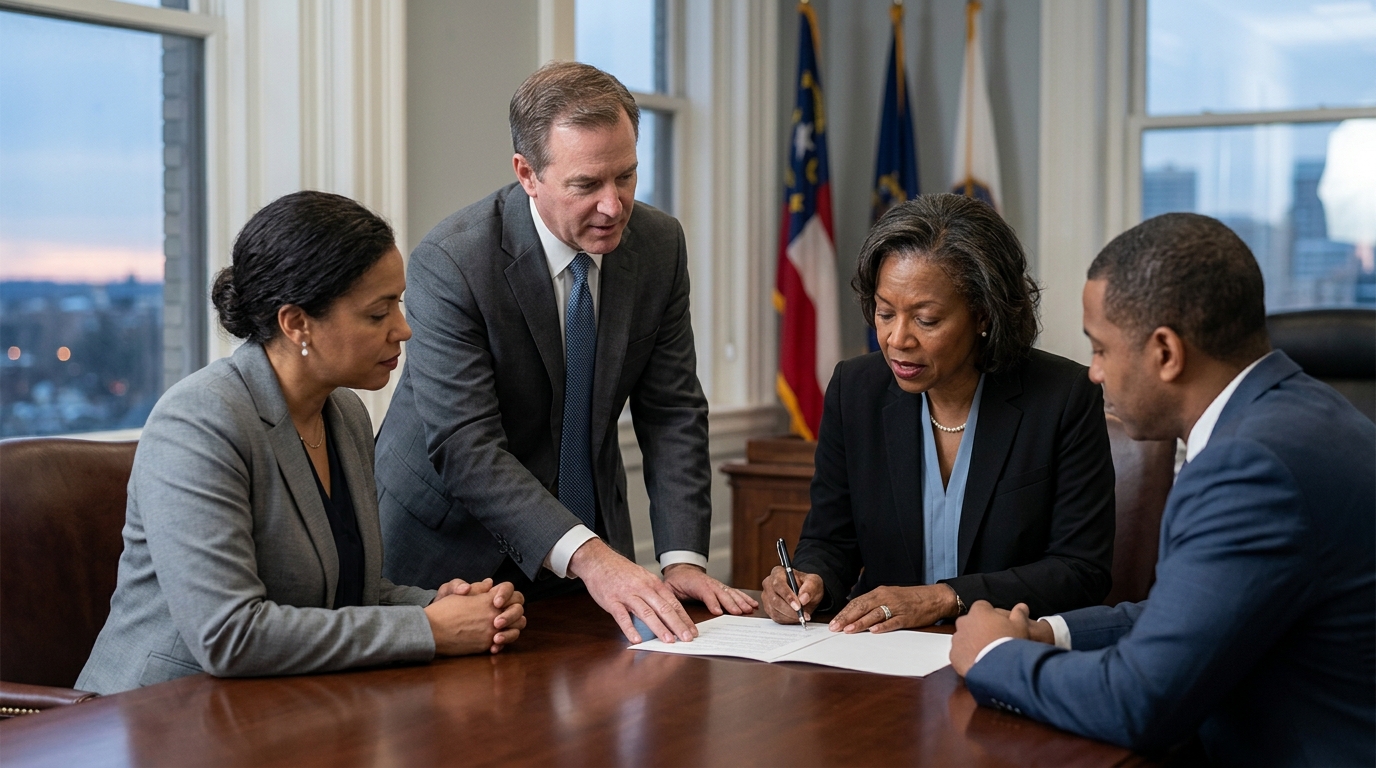
Hey there, bargain hunter. Last Thursday in Chicago, thirteen governors and the mayor of Washington, D.C., did something rare: they signed a piece of paper together. The document formally established the PJM Governors’ Collaborative, a bipartisan coalition that includes Democratic governors from New Jersey, Pennsylvania, Illinois, and Maryland alongside Republican governors from Indiana, Ohio, Virginia, and other states. Their shared complaint is a grid operator they say has been unaccountable, expensive, and slow.
The Energy Stock Trump Once Called “A Big Mistake” to Mess With
When a U.S. ally tried to tax ONE American energy company…
Trump didn’t hesitate to issue a direct warning.
Now this same company is generating over $3 billion in operating income…
And partnering with the hottest AI stock on Wall Street.
Out of 23,281 publicly traded stocks, this is the ONLY one that meets all the “unicorn” criteria.
Scoreboard
The coalition’s founding document cites an 833% increase in PJM capacity auction prices for the 2025-26 delivery year compared with the prior auction. That number is not a typo. Capacity cleared at $28.92 per megawatt-day in 2024-25, then jumped to $269.92 for 2025-26. The 2026-27 auction hit the federally approved cap at $329.17 per MW-day, and the 2027-28 auction hit its cap at $333.44 per MW-day. The 2028-29 auction settled at the $325 per MW-day cap. Three consecutive auctions at their ceiling. Meanwhile, CEG, VST, and TLN all rallied double digits just last Tuesday on a Google power deal. The stocks are pricing in more of the same.
What Actually Happened
The governors are not reacting to a single data point. The coalition has been forming for over a year, with states pressing FERC and PJM for price constraints that were applied in recent auctions. Now they have formalized their structure with a memorandum of understanding, development of joint positions, shared technical expertise, and coordinated advocacy before FERC and Congress. The timing, 24 days before midterms where electricity bills and data centers are central issues, is not accidental.
Illinois Governor JB Pritzker, who hosted the summit, framed it plainly: states want a seat at the table where decisions affecting residents are being made. Maryland Governor Wes Moore said PJM and its members had prioritized profits over ratepayers for too long.
Why Nov. 12 Could Matter for Your Money
If you own stocks, bonds, or have retirement savings, Nov. 12 deserves your attention. Jeff Opdyke warns China’s next financial move could hit the U.S. dollar – and your wealth. See why.
The Real Reason This Matters for Your Holdings
PJM’s capacity market exists to pay generators for promised availability, not just energy delivered. Constellation cleared 18,875 MW in the 2028-29 auction. Talen cleared 10,180 MW at the $325 cap. Vistra and NRG carry similar exposure. Those payments are not a bonus. For pure-play merchant generators, capacity revenue is a core earnings pillar. Talen’s recent results commentary has pointed to higher PJM capacity pricing as a contributor. CEG management has also highlighted capacity pricing as a factor in stronger results.
The coalition’s explicit goal is to reduce that revenue stream. The price collar has already been binding. PJM has published uncapped simulations that imply materially higher clearing prices than the capped outcomes, which is money that did not reach generators.
Is It Cheap, or Is It Just Riding the Wave?
Here is the uncomfortable question. The merchant power stocks were priced as growth stories because capacity auctions kept setting records. If thirteen governors, wielding FERC complaints and political pressure in an election season, succeed in structurally lowering those auction prices, the earnings forecasts embedded in current valuations need revisiting. The Google deal provides some offset: long-term bilateral contracts at negotiated rates reduce dependence on the spot capacity market. CEG’s data-center agreements and NRG’s long-term arrangements are genuine diversification. But they do not fully replace auction revenue at scale.
These 7 Stocks Will Be Magnificent in the rest of 2026
Every market cycle creates a small group of stocks that end up doing most of the work.
The surprise is never that they succeeded – it’s how early their trajectory was visible.
Our analysts believe the next group of leaders is already taking shape, just outside the spotlight.
In These 7 Stocks Will Be Magnificent in the rest of 2026, we highlight companies with expanding cash flows, growing market share, and the characteristics that often precede long-term leadership.
Bull / Base / Bear
- Bull: The coalition stays loud but lacks binding authority. FERC moves slowly, PJM’s governance is federally regulated, and data-center demand keeps the grid chronically short. Auction prices stay elevated because the supply gap is real regardless of political pressure.
- Base: Governors win incremental reform: constraints stay in place and get extended. Auction revenue stabilizes below what an uncapped market might have produced, but does not collapse. Bilateral contracts pick up the slack unevenly across names. CEG and TLN, with stronger corporate power agreement pipelines, hold up better than pure merchant players.
- Bear: Coalition gains genuine FERC traction, structural capacity market redesign follows, and merchant revenue resets lower across the PJM fleet. Stocks that ran on auction euphoria give back a significant portion of 2025-26 gains.
Action Plan
Bargain hunter, the question is not whether the fundamentals changed last Thursday. They did not, at least not yet. The question is whether the market is pricing any of this political risk at all. After double-digit rallies on a single Google deal, the answer looks like no. Trim positions sized for $325-cap-forever. Hold or add selectively on names with the strongest bilateral contract coverage, where capacity auction dependency is lowest. Watch FERC dockets and midterm results before assuming the coalition is noise.
Cheap Investor Checklist
- What share of each company’s forward EBITDA comes from PJM capacity payments versus bilateral contracts?
- Has guidance been stress-tested against a roughly $175 per MW-day capacity floor that has been part of PJM’s recent collar framework?
- Does the coalition’s MOU result in a formal FERC complaint or rulemaking proceeding within 90 days?
- Are midterm results in PJM states likely to strengthen or weaken governor leverage?
- Watch TLN’s Cornerstone integration and AWS contract ramp for non-auction cash flow confirmation.
- Track PJM’s Reliability Backstop Procurement timeline, which FERC accepted but suspended for five months with an effective date of Feb. 28, 2027, and watch whether it gets reshaped under governor pressure.
Bottom Line
If the PJM Governors’ Collaborative remains a press release, merchant power stocks are fine. If it translates into durable FERC-level reforms, the earnings case that drove CEG, VST, and TLN to their recent highs rests on an auction price floor that thirteen governors are explicitly trying to lower. Know which scenario your position price assumes, because the market right now is betting hard on the first one.