September 18, 2026
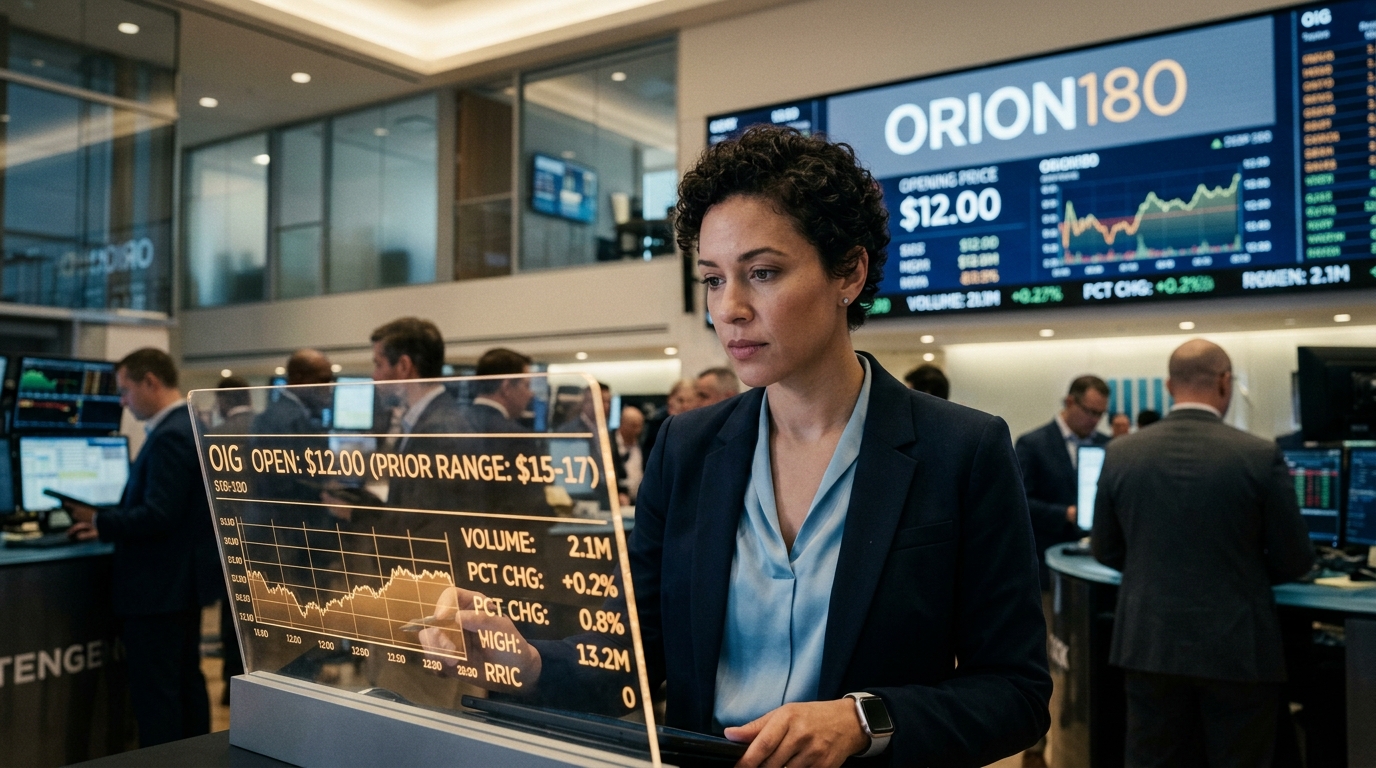
Bonus Content: Orion180 Priced Its IPO at $12. The Range Was $15 to $17.
Editor’s Note: Marc Chaikin, the 60-year Wall Street legend who called Nvidia before it soared 45,000%, just came forward with a playbook for investing in an era of “Frontier AI.” Marc’s indicators found in every Bloomberg and Reuters terminal in the world – have identified a list of the biggest potential winners and losers for the world that comes after the tipping point that Elon Musk is calling for in 2026. Read his message below and then click to get the FREE stock names and tickers he says to buy and sell now.
Dear Reader,
“Frontier AI” is a point of no return when AI surpasses human intelligence and gains free will.
Elon Musk warns this tipping point could occur by the end of 2026.
And according to my research, that moment may have just occurred behind the glass and steel structure you see right here.
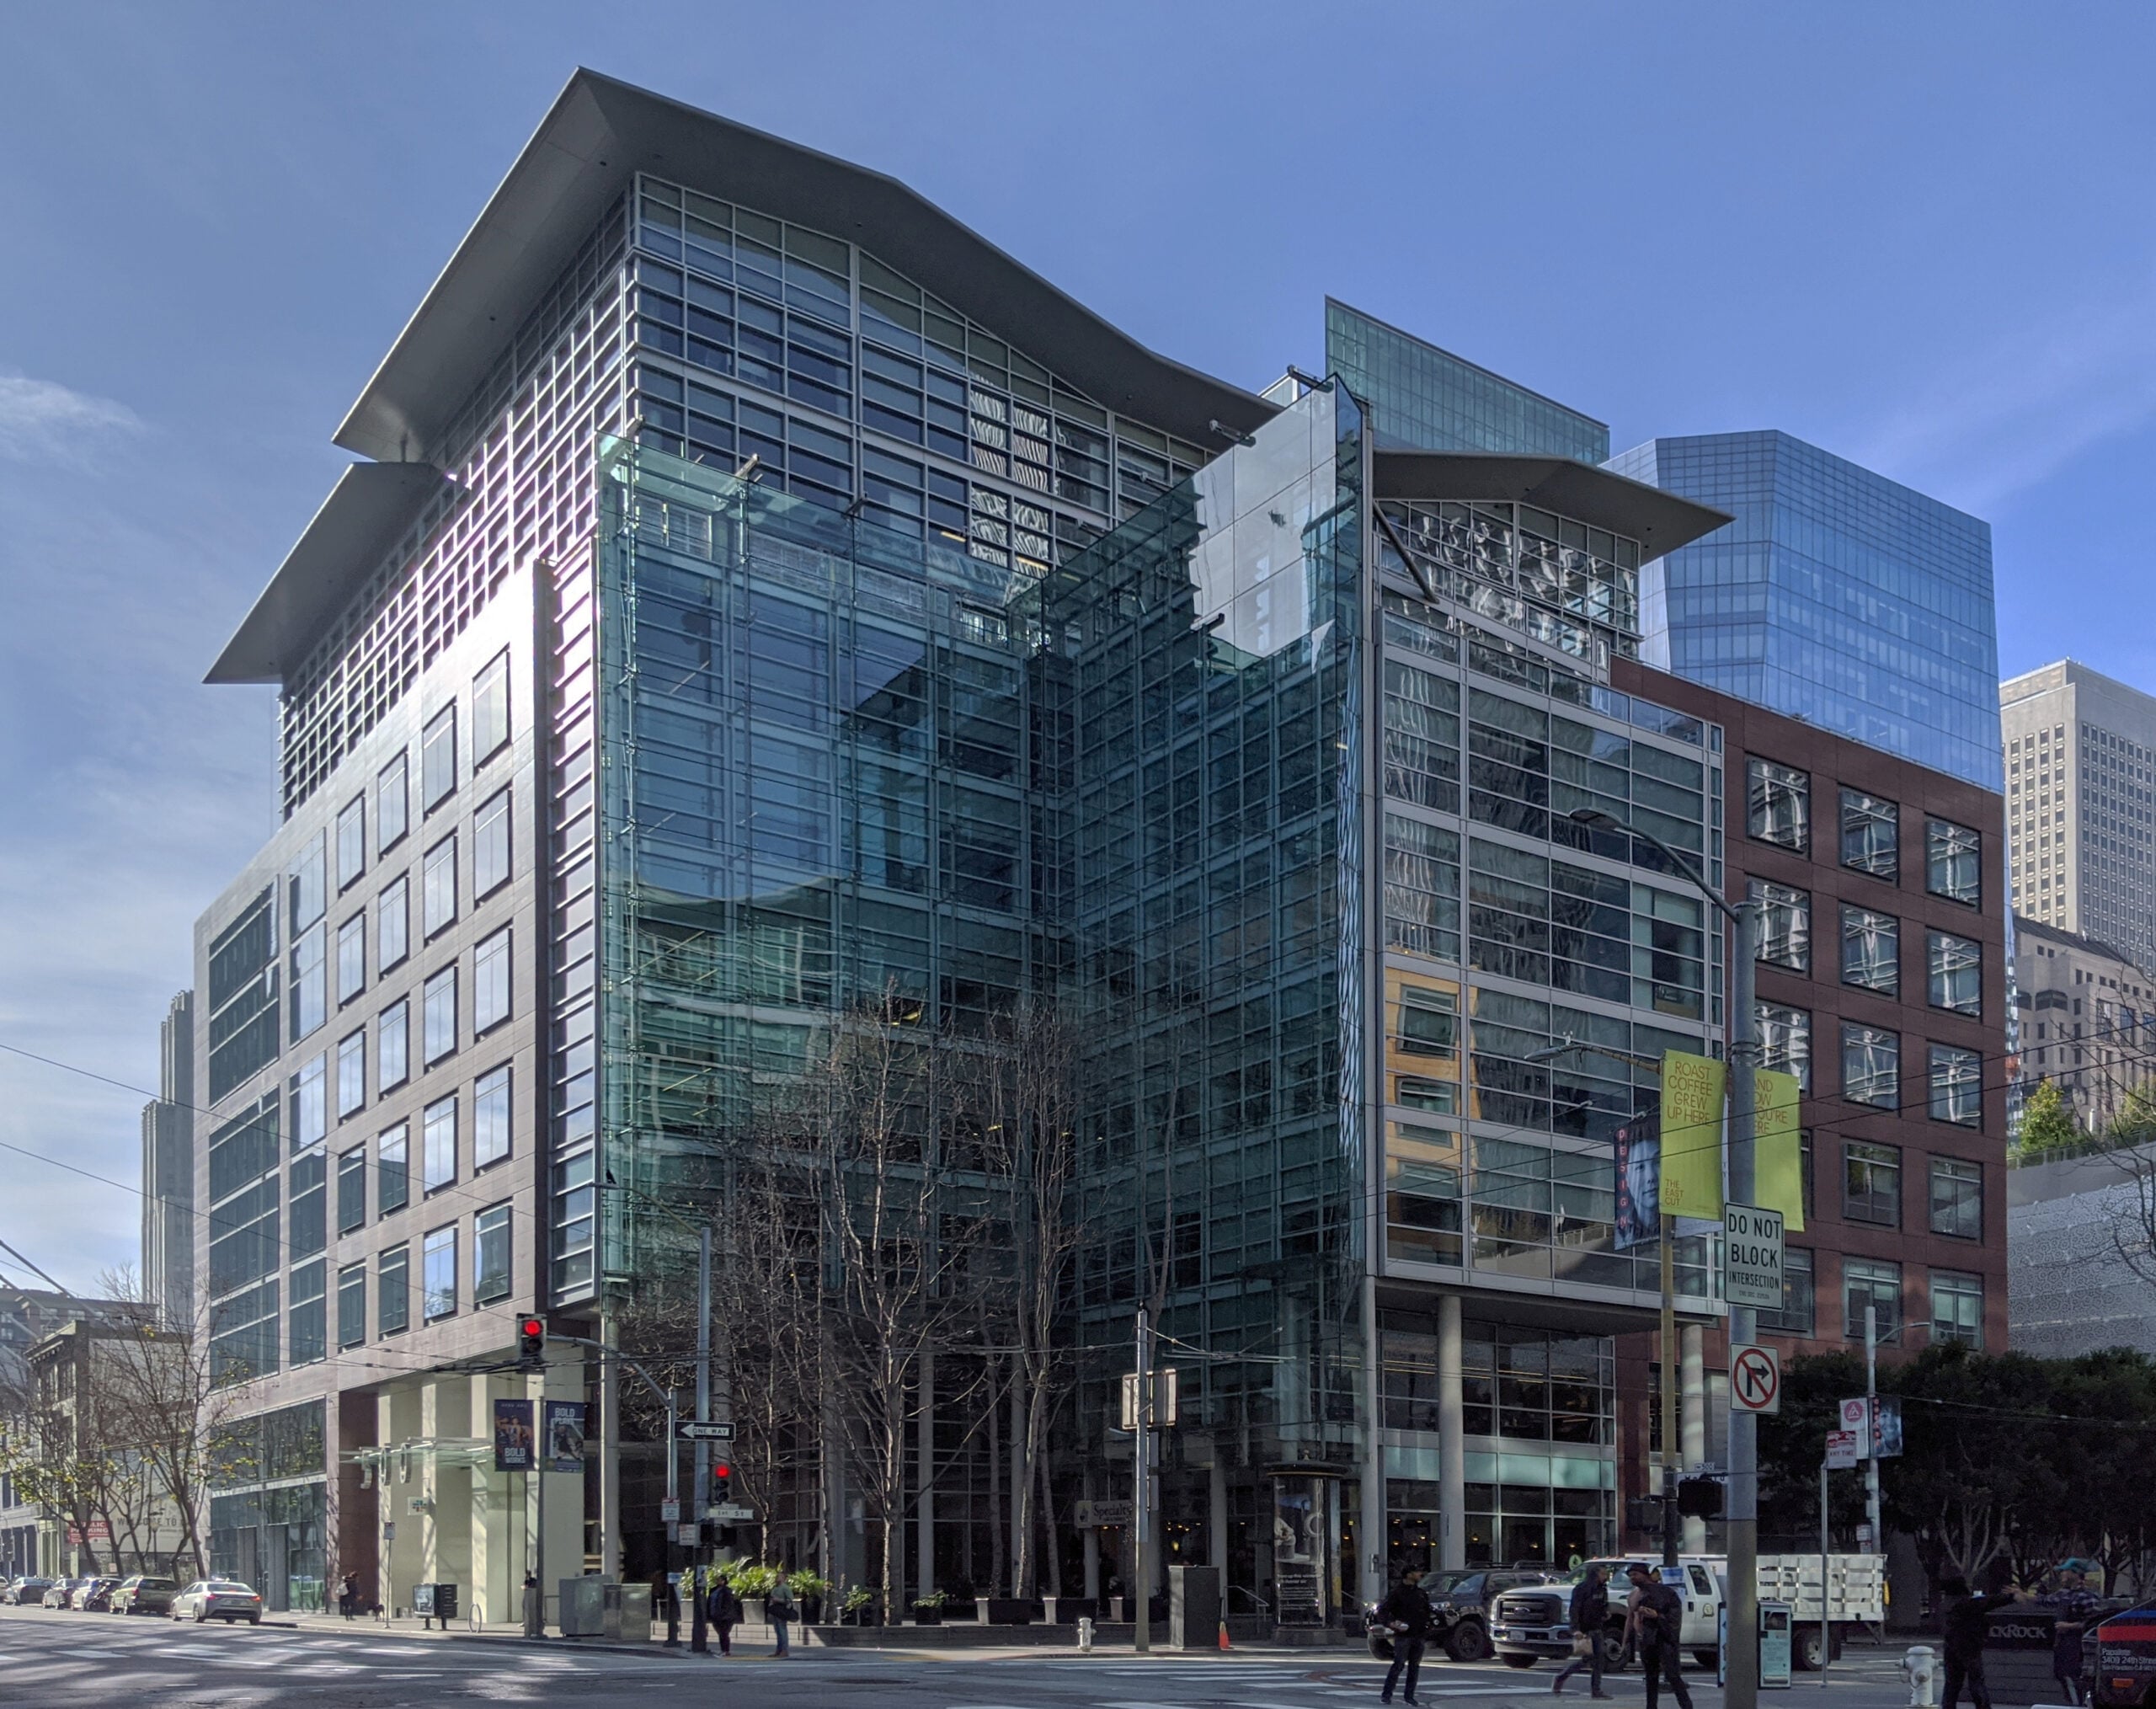
As Frontier AI makes its way from this Silicon Valley lab to a small group of hand-selected companies, it could soon cleave the stock market in half. Some stocks will ride this shift to 100X gains. Others could face a total wipeout.
That’s why I’m giving away a list of stocks to buy and sell absolutely FREE to help you position your money for a new world driven by Frontier AI technology.
Get my Frontier AI Hotlist – including six free trade ideas – right here…
Sincerely,
Marc Chaikin
Founder, Chaikin Analytics
P.S. If any of this sounds far-fetched to you, please understand something…
The AI tools you have access to are the equivalent of the Stone Age when you put them up against the AI that Silicon Valley is keeping behind locked doors.
And when this secretive version of AI leaves the lab, one of the first things that I predict will be heavily impacted will be the stock market.
And there’s only a small window of time to position your money before this “jump to lightspeed” in AI technology cleaves the market into two classes of stocks – winners and losers.
Orion180 Priced Its IPO at $12. The Range Was $15 to $17.
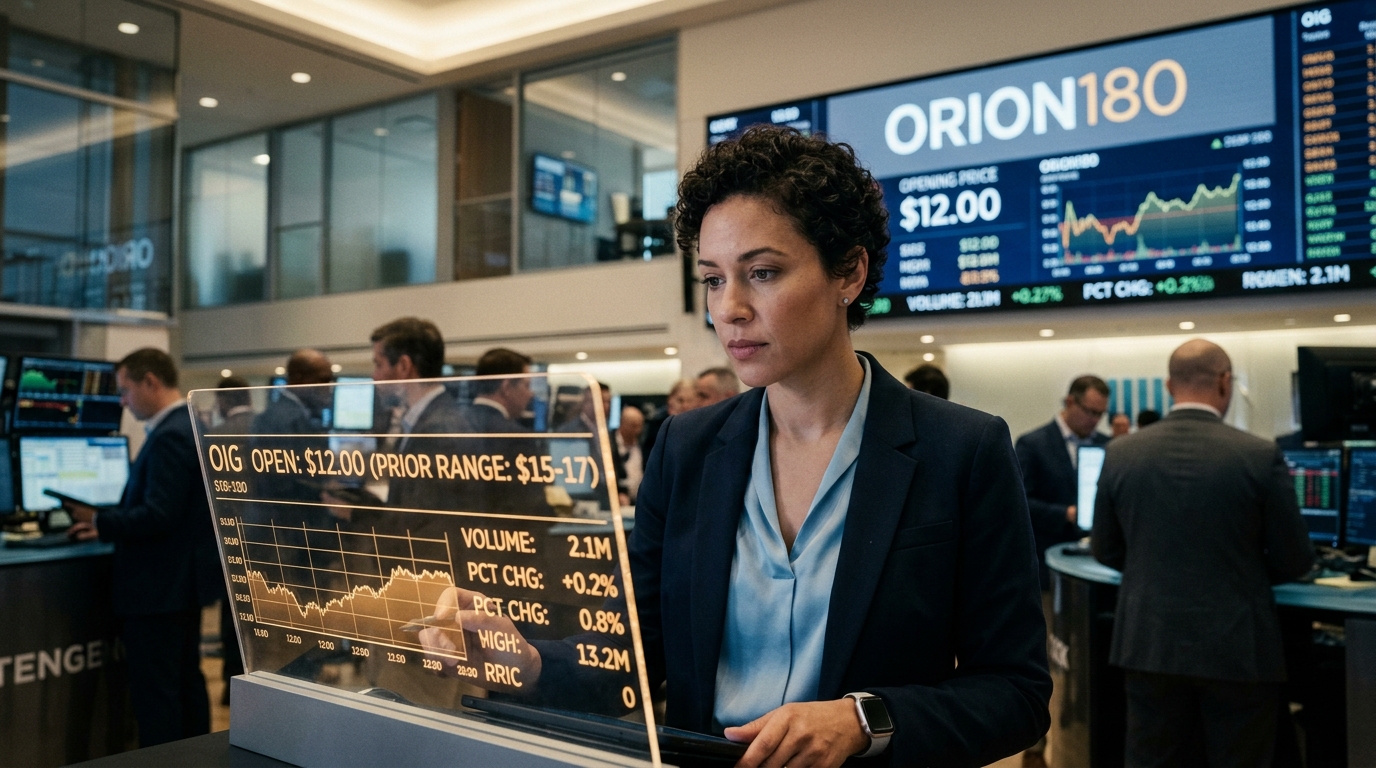
Hey there, bargain hunter. A stock that prices below its marketed range sounds like a sale. Sometimes it is. More often it is the market telling you the original ask was wrong. Today, OIG starts trading, and your job is to figure out which one this is.
Scoreboard
Orion180 sold 20 million shares at $12 apiece, below its indicated range of $15 to $17. The offering raises $240 million at the stated price, not including any shares purchased through the underwriters’ overallotment option. The original range implied roughly $340 million and a valuation near $1.7 billion. At $12, that valuation is meaningfully lower, but it still has to be earned.
The macro backdrop made this harder. Broader markets were whipsawed in September by surging bond yields and a shift back toward tighter monetary policy, with the Federal Reserve delivering its first rate hike since 2023 this week. One headline deal did not survive that. Holtec Nuclear Corp., a supplier of specialty services to the nuclear power industry, postponed its planned US initial public offering. The Florida-based firm had been set to raise as much as $900 million. Orion180 crossed the finish line, but at a cost.
What the Business Actually Is
Founded in 2018 and headquartered in Melbourne, Florida, Orion180 claims to be the second-largest excess and surplus lines homeowners insurance provider in the United States by direct written premiums, with operations in 14 states. The company distributes its products through a network of more than 14,000 active independent agents as of June 30, 2026.
The E&S market exists because standard carriers will not touch certain risks. Florida homeowners insurance is exactly that kind of risk: hurricane exposure, litigation history, carrier exits. Orion180 steps in where others step out, charges accordingly, and uses proprietary technology to underwrite and price in real time. That is the pitch.
Data Section
- Net income of $13.5 million on revenue of $80.1 million for the first six months of 2026, compared with a net loss of $3 million on revenue of $50.4 million a year earlier.
- Direct written premiums of $601 million over the trailing 12 months ended June 30.
- Gross premiums written of $354 million for H1 2026, up roughly 79% year over year. Gross loss ratio of 38.3%.
- Full-year 2025 gross loss ratio improved to 30.3% from 32.8% in 2024; net loss ratio dropped to 60.7% from 81.5%.
- Cash and cash equivalents of $170.8 million as of June 30, 2026; total assets of $911.6 million.
- A portion of IPO proceeds may be used to repay $282 million in outstanding debt.
Is It Cheap?
At $12, the valuation pressure eases but does not disappear. Annualizing Orion180’s H1 2026 results works out to roughly $160 million in run-rate revenue and $27 million in net income; against the original $1.7 billion headline valuation at the top of the range, that put the price-to-sales ratio near 10.5x and the price-to-earnings ratio above 60x. At $12 those multiples compress, but the company is still asking you to pay a growth premium for a business concentrated in one of the most litigious, storm-prone insurance markets in the country.
Renaissance Capital’s Nicholas Einhorn noted that “both Orion180 and Bamboo cite lower-than-average loss ratios on policies, driven by their underwriting platforms; both are also growing quickly.” His caveat matters more: “investors in insurance IPOs scrutinize the companies closely and those companies have sometimes had to prove themselves post-IPO.”
Bull / Base / Bear
Bull: Revenue more than doubled year over year, the gross loss ratio sits comfortably below 40%, and the E&S homeowners market continues to expand as admitted carriers retreat. A proven path to profitability at scale makes the $12 price look like an entry, not a rescue.
Base: Growth normalizes as Orion180 expands into less favorable states, reinsurance costs creep higher post-hurricane season, and the stock grinds sideways while the company pays down that $282 million debt load.
Bear: A major hurricane hits Florida in 2026 or 2027, reinsurers raise prices aggressively, and the loss ratio snaps back toward the levels that generated three consecutive years of operating losses before 2025. Weiss Ratings flags negative cash flow from operations for 2025 as a concern.
Action Plan
Do not chase on day one. The allocation at $12 was reportedly concentrated among large mutual funds, meaning there is institutional paper above you in the stack. If OIG trades below $11 in the first two weeks, that is a more interesting entry. If it holds $12 to $13 through the first earnings report as a public company, a small starter position with a stop near $10 is defensible.
Cheap Investor Checklist
- Gross loss ratio stays below 42% through end of 2026
- Direct written premiums maintain 50%-plus growth through Q4
- Net debt declines as IPO proceeds are deployed against the $282 million outstanding
- No major hurricane landfalls in Florida or the Gulf through November
- Reinsurance renewal terms in Q1 2027 come in flat or better
- Bamboo Insurance IPO prices and trades well, validating the E&S insurer premium
- Founder Kenneth Gregg does not sell Class B shares in the first 180-day lockup window
Bottom Line
If Orion180’s loss ratios hold and the Gulf stays quiet through year-end, OIG at $12 is a discounted entry into a genuinely fast-growing specialty insurer. If the next named storm makes landfall near Melbourne, Florida, this is a very different conversation. Watch the checklist, size small, and let the first public quarter do the talking.