Dear Reader,
Before Bear Stearns collapsed … Lehman Brothers went bankrupt … and Washington Mutual became the largest bank failure in American history …
Our company Weiss Ratings was already warning investors about these risks.
Unfortunately, by the time most Americans realized how serious the problem was, the financial crisis was already upon us and much of the damage was already done.
That’s why we’re speaking out today.
The founder of Weiss Ratings, Martin Weiss, a Wall Street Journal, BusinessWeek and New York Times best-selling author …
Has been running Weiss Ratings as a 100% conflict-free, independent financial rating agency for 55 years.
And during those 55 years, he’s publicly warned investors before six major American crashes.
Right now, he believes another dangerous credit crisis is building beneath the surface.
Banks … insurance companies and annuities … investment funds and retirement portfolios could all feel the effects if it spreads.
However, many Americans don’t realize how exposed their money already is.
Don’t make that mistake.
That’s why he’s laid out five specific steps you can take now to help protect your wealth before this new crisis spreads.
The first step alone could help you identify where your money could be vulnerable. And the remaining steps show you what he believes you should consider doing with your money instead.
Please don’t wait for another Lehman-style headline before you take this seriously.
See Martin’s warning and the five steps he recommends taking now
Sincerely,
Eliza Lasky
Weiss Advocate
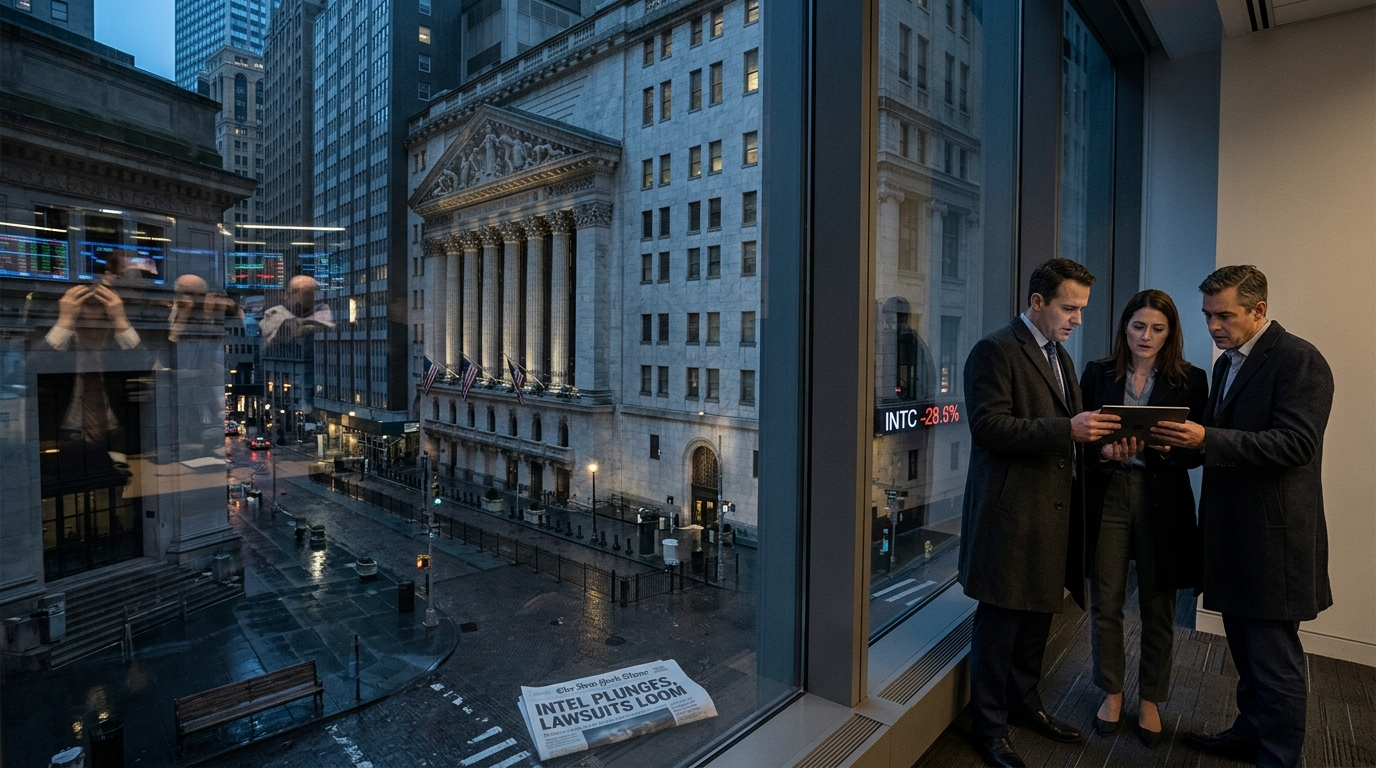
Intel Lost $140 Billion in One Day. Now Shareholders Are Suing.
Hey there, bargain hunter. Intel just handed you a 29% discount in a single session. The question worth asking before you reach for it: is this a sale, or a crime scene?
Scoreboard
Shares of Intel fell 28.6% on October 30, wiping out about $140 billion of market value, one day after the company projected lower-than-expected fourth-quarter revenue and profit and forecast a prolonged slowdown in PC sales. Intel shares are up 62% this year through Friday, November 13, though they have slid from their recent peak of $142.35 on June 30. Shares closed Friday at $59.66. As of November 16, INTC is trading near $58-59, down about 3-4% in overnight venues on the lawsuit news.
What Actually Happened
CEO Lip-Bu Tan and CFO David Zinsner are now facing a shareholder lawsuit alleging the chipmaker withheld information about weakening PC demand and excess inventory before the stock’s nearly 29% single-day plunge.
In a proposed class-action filed in federal court in San Jose, shareholders led by the City of Southfield Fire and Police Retirement System accused Intel of misleading investors about the financial impact of slowing PC sales and mounting inventory. The complaint covers anyone who bought Intel between July 23 and October 29, 2026.
The sharpest allegation: Intel had the motive and opportunity to defraud by raising capital in mid-August, halfway through its “disastrous” third quarter, when it sold $23 billion of stock at $95 per share. Selling $23 billion worth of shares while your core PC business is quietly cratering is the kind of timing that makes plaintiff attorneys very happy.
The PC Numbers They Say Were Hidden
Here is what the data looks like now that it is in the open. Revenue from Intel’s PC chip business was $8.1 billion in Q3 2026, and management said it expects that segment’s revenue to decline greater than 20% sequentially in Q4 as customers work down their inventory.
Intel is not the only name that saw this coming. HP warned the SEC weeks earlier that global PC unit volumes could shrink in 2027, a signal the channel was softening well before Intel’s quarter landed.
Management pointed to an “unprecedented memory crunch” and resulting softness in PCs, and said the inventory correction is expected to persist into 2027. Intel said it is planning for the 2027 PC unit TAM to decline roughly 10%.
The memory crunch Intel cited is not isolated to one company’s balance sheet. Micron has responded to the same inventory cycle by locking customers into take-or-pay contracts through 2031, a structural shift that tells you how long memory suppliers expect the correction to run.
The shareholders said Intel’s problems with PC sales and excess inventory outweighed data center construction and other benefits related to the artificial intelligence boom. Intel’s Data Center and AI revenue rose 78% year-over-year to $7.3 billion. AI is real. It just cannot carry the whole company when PCs account for a large share of revenue and those customers are sitting on chips they already bought.
Is It Cheap?
INTC trades at a high multiple if you look at near-term earnings power, which is exactly why “cheap on a chart” can still be expensive in practice. Several widely circulated peer-multiple stats in the original draft were not supported by a consistent, verifiable source set, so they have been removed here rather than leaving potentially stale numbers standing.
The stock has fallen to a forward P/E of roughly 30x based on 2027 analyst estimates, though some analysts argue Intel does not deserve a premium multiple given the headwinds it faces. The average analyst price target implies about 52% upside from current levels, with a consensus target near $90.93 and a high of $145.
Bull / Base / Bear
- Bull: Inventory correction is a one-to-two quarter event. Data center growth at 78% year-over-year is the real business now. The lawsuit gets dismissed, as Intel prevailed in a prior securities case tied to foundry-related claims that was dismissed in July 2025. Stock re-rates toward $90.
- Base: PC drag runs through Q1 2027 as guided. Q4 revenue lands between $15 billion and $16 billion with non-GAAP EPS of $0.25. Stock grinds sideways in the $55-70 range while litigation plays out.
- Bear: Intel will be paying for 2027 with cash from the equity offering, leaving less room for data center growth to stall or the PC slump to run longer. If PC weakness extends into 2028 and the lawsuit gains traction, the stock revisits the low $40s.
Action Plan
Do not buy the full position today. The lawsuit creates binary risk: if discovery surfaces communications that show management had real-time PC channel data during the August equity raise, the legal cost and reputational damage become hard to model. Wait for one of two conditions: a court dismissal of the class action, or Q4 results confirming the inventory burn is on track. Scale in at $55 and again near $48 if it gets there.
Cheap Investor Checklist
- PC segment revenue decline confirmed at greater than 20% quarter-over-quarter in Q4?
- Inventory correction resolved by Q1 2027 as guided?
- Data center revenue sustaining above $6 billion per quarter?
- Lawsuit dismissed or settled without material cash outlay?
- Gross margin holding at or above 38% in Q4?
- No additional equity dilution beyond the 5.44 billion fully diluted share count Intel guided to for Q4?
- AMD PC share stable (no additional Intel share loss in the channel)?
Bottom Line
If the PC inventory correction ends on schedule and the lawsuit gets dismissed the way Intel’s last major shareholder case did, this is a genuine discount on a data center story the market overpenalized. If the August equity raise was timed around knowledge management had and shareholders did not, this is a different kind of problem entirely. Watch the Q4 results and the San Jose docket. Only one of them will tell you which it is.