October 6, 2026
Bonus Content: Ithaca Energy Pays $860m to Leave the North Sea Tax Trap
In case you missed it…
…make sure you get your free “Simple Options Trading For Beginners” book before your link expires.
I eventually plan to charge money for this training, so do yourself a favor and download it now…
That way, no matter what it costs in the future, you’ll have a free copy.
Sound good?
FREE: Simple Options Trading For Beginners << Get It Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of your “Simple Options Trading For Beginners” book while it’s still free.
Ithaca Energy Pays $860m to Leave the North Sea Tax Trap
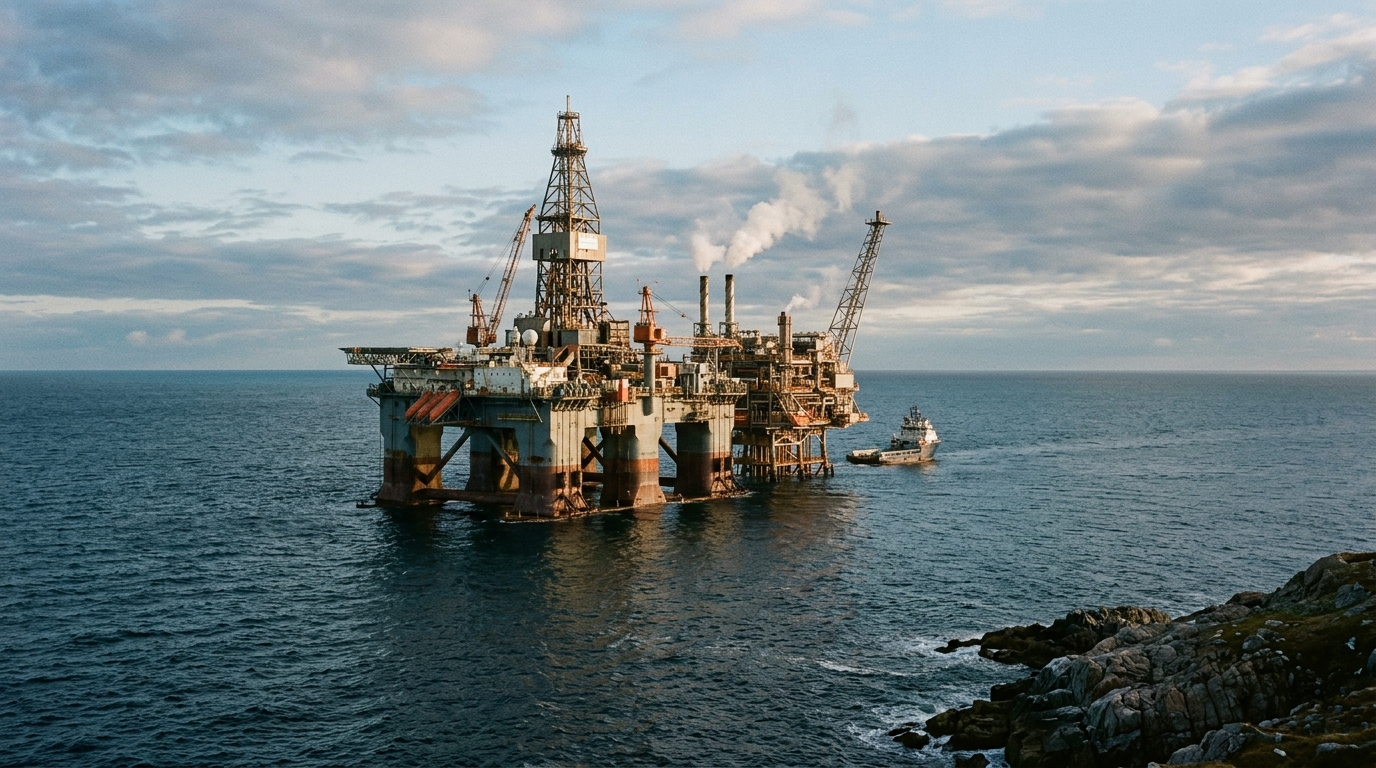
Hey there, bargain hunter. A North Sea oil producer just handed $860 million to Suncor to get out of one of the world’s toughest upstream tax regimes and into a Canadian basin where the government actually wants new barrels. That deserves a closer look.
Scoreboard
Ithaca Energy agreed to acquire Suncor’s interests in the Terra Nova and White Rose oil assets offshore eastern Canada for $860 million in cash, marking its first international acquisition outside the UK. The deal includes potential oil-price-related contingent consideration of up to $250 million based on a sharing factor of 50%. ITH.L led the FTSE risers on announcement day, adding roughly 3.5% to close around 285p.
What Actually Happened
The market read this correctly. The 38% Energy Profits Levy sits on top of the 30% ringfence corporation tax and 10% supplementary charge, producing a headline rate of 78% on North Sea oil and gas profits. That is not a regime you invest through; it is one you manage around. Newfoundland offers lighter fiscal terms, tidewater access, and Brent-linked pricing. Ithaca is paying up to avoid paying more.
The Energy Profits Levy had already pushed Ithaca to reduce investment in near-term projects, deferring or cancelling work at the Greater Stella Area, Montrose Arbroath Area, Elgin Franklin Area, and Alba assets. The Canadian deal is the structural response to that squeeze.
What the Business Is Buying
The deal includes a 48% operated interest in Terra Nova, a 40% non-operated interest in the White Rose Existing Lands, and a 38.6% non-operated interest in the White Rose Growth Lands, including the West White Rose Extension.
Terra Nova is a producing, operated shallow-water asset supported by a recently completed FPSO life-extension project. White Rose is operated by Cenovus Energy and carries substantial near-term production growth from West White Rose, where first production is anticipated in Q4 2026.
The Numbers
- 103 million barrels of 2P reserves, acquired at roughly $8 per barrel.
- Average 2P production of about 30,000 boe/d expected between 2027 and 2031, rising to 35,000-40,000 boe/d in 2029 as West White Rose ramps.
- Net production for the 12 months to June 2026 was 11.6 kboe/d from Terra Nova.
- The acquisition also adds around 200 million boe of additional resources.
- Contingent payments are triggered if average Brent exceeds $80 per barrel over the period from 1 July 2026 to 30 June 2027, with lower thresholds of $74 and $73 in later periods.
- Ithaca expects to fully finance the transaction through cash on hand, its borrowing-base facility, and secured in-country financing.
- The company expects immediate gains to cash flow and dividends per share.
Is It Cheap?
$8 per 2P barrel is a low entry point for conventional offshore oil. Ithaca itself trades at a trailing EV/EBITDA below 4x, a dividend yield above 9%, and was targeting a total 2026 payout of $470 million to $520 million. Since then, the company upgraded its 2026 dividend guidance range to $500 million to $530 million. Adding 30,000 boe/d of Canadian production to that base changes the per-share math meaningfully, assuming West White Rose lands on schedule. That is the key assumption.
Bull / Base / Bear
Bull: West White Rose flows in Q4 2026 as guided, Brent holds above $80, the contingent $250 million never triggers because the stock re-rates first. The UK Energy Profits Levy ends early in 2027, giving Ithaca a double tailwind.
Base: Canada production ramps through 2027 as modelled, the UK book keeps generating cash at current tax rates, and the combined entity sustains a 9%-plus yield. The portfolio peaks at 35,000-40,000 boe/d by 2029.
Bear: There is no assurance West White Rose completes on the expected timetable, and any material delay could reduce the anticipated cash flows and benefits of the transaction. A Brent slide below $73 wipes out contingent risk for Suncor but also pressures Ithaca’s free cash generation.
Action Plan
For aggressive accounts already holding ITH.L, hold. The re-rating from a pure UK tax story to a North Atlantic producer is only partially priced at 285p. For new money, a scale-in at or below 270p builds a position at roughly 8x forward earnings with the Canadian catalyst still ahead. Watch the West White Rose first-oil announcement: that is the next hard catalyst. Conservative accounts can wait for that confirmation before sizing up.
Cheap Investor Checklist
- West White Rose first oil: confirmed Q4 2026?
- 2P production ramp: tracking toward 30,000 boe/d by 2027?
- Brent spot vs. $80 contingent trigger: monitor monthly
- UK Energy Profits Levy: watch for 2027 sunset announcement
- Ithaca 2026 dividend: $500-530 million guidance maintained?
- Transaction close: customary regulatory approvals pending
- Terra Nova FPSO reliability: any unplanned downtime?
- Delek Group (parent) balance sheet: no forced-seller risk
Bottom Line
If West White Rose flows on schedule this quarter and Brent stays above $75, Ithaca Energy just bought 17 years of reserve life at $8 a barrel while the market was still pricing it as a North Sea tax problem. If first oil slips into 2027, patience is required. Either way, the fiscal logic of the move is sound: 78% tax rates in the UK, tidewater barrels in Canada, and a yield above 9% while you wait.