October 4, 2026
Bonus Content: PJM’s Power Auction Is Stuck. Existing Plants Are Winning.
If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
PJM’s Power Auction Is Stuck. Existing Plants Are Winning.
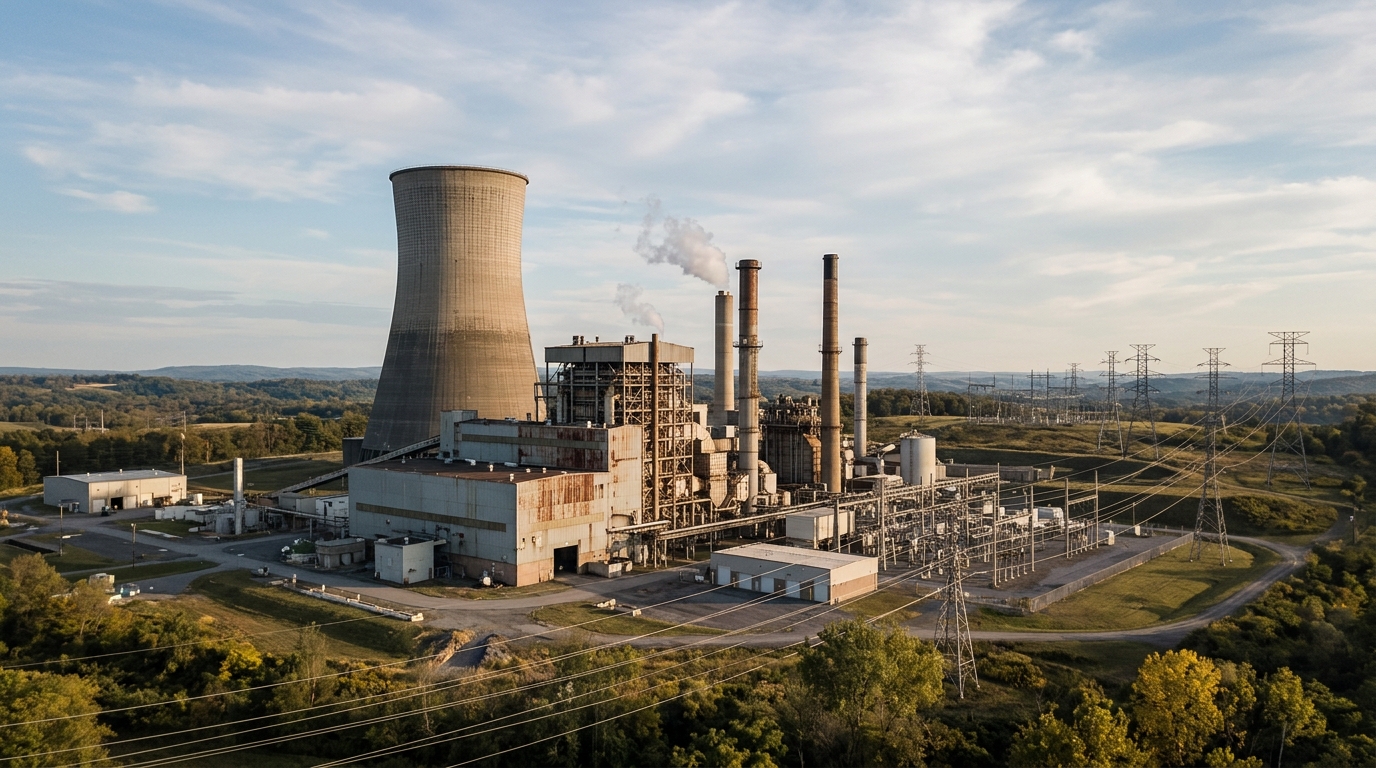
Hey there, bargain hunter. The country’s largest electric grid just got publicly dressed down by its own regulator, and the timing could not be better for anyone who already owns a power plant inside it.
Scoreboard
FERC, on September 29, accepted PJM’s Reliability Backstop Procurement for filing but flagged concerns with key elements. FERC then suspended the program for five months, to an effective date of February 28, 2027. PJM pulled the auction it had planned to open on September 30. The RBP was designed to close a 6,831 MW shortfall from the 2028/2029 Base Residual Auction.
What Actually Happened
FERC Chairman Laura Swett was blunt. Utility Dive reported that PJM filed at the last minute and left the agency no time “to rehabilitate the mess we received,” she wrote in a concurring statement. Cost allocation, transmission owner exit rules, and load-serving entity collateral requirements may be unjust and unreasonable, FERC said.
A new timeline for the backstop procurement is yet to be determined. That matters. PJM has discussed an emergency-style procurement sized to meet fast-rising large-load demand, including data centers, with public materials and third-party analysis frequently citing an initial target on the order of roughly 15 GW. That supply is now in limbo, and the grid keeps falling short.
What the Market Is Really Saying
Wall Street spent 2024 and early 2025 bidding up independent power producers as AI proxies. Then it changed its mind. Several large generators have sold off in 2026 alongside Vistra.
As of the October 2, 2026 close, Vistra shares were about $138.76, and data aggregators tracking S&P Global sell-side estimates showed an average analyst target around $213-$218 (roughly mid-50% upside from that level). The operating reality underneath that selloff has not changed.
In parts of PJM, Vistra saw considerably higher year-over-year average power prices in the first quarter of 2026. In the PJM Western Hub, average power prices were $97.41/MWh, up 81% from $53.91/MWh in the same period of 2025. The stock is down. The power price is up. That is the disconnect.
The Numbers
- VST forward P/E: About 13x, a low multiple for a company with 20-year power purchase agreements with large technology customers.
- VST 2026 EBITDA guidance: Vistra has reaffirmed 2026 ongoing operations adjusted EBITDA guidance of $6.8 billion to $7.6 billion.
- CEG forward P/E: Constellation raised 2026 adjusted operating earnings guidance to $11.50-$12.50 per share in August 2026.
- TLN implied upside: Data aggregators tracking S&P Global estimates put Talen’s consensus price target around $460 in late September 2026, versus a stock price in the low $320s around October 1.
- PJM capacity price cap: $329.17/MW-day for 2026/27, about a 22% increase from the prior auction, which itself was roughly a nine-fold jump versus 2024/25.
Is It Cheap?
Vistra at about 13x forward earnings is pricing in neither the capacity tailwind nor the nuclear PPA premiums still being negotiated with hyperscalers. Vistra carries higher financial risk due to its leveraged balance sheet. Constellation is pricier but cleaner, with a regulated-adjacent moat from its nuclear fleet. Talen is the smallest and the most volatile, but the upside math is hard to ignore.
Bull / Base / Bear
Bull: FERC’s suspension delays new supply, sustaining capacity price pressure well into 2027. Existing generators collect elevated capacity revenue while the paperwork stalls. PPAs with hyperscalers layer contracted upside on top.
Base: PJM refiles quickly, auction launches in early 2027, and the market stays tight enough to keep prices elevated but not at record caps. Current plant owners collect strong cash flow while new supply is still years from delivery.
Bear: If the RBP is implemented successfully, the program could reduce scarcity conditions over time and pressure the forwards that underpin some PPA valuations. Add a regulatory surprise, a milder winter, or a demand revision, and the premium evaporates.
Action Plan
The delay is a fundamental tailwind, not a permanent one. If you have no position, the selloff across the group gives you entry points that look historically cheap relative to both cash flow and consensus targets. VST is the most dislocated on a forward-earnings basis. CEG is the most defensive. TLN is highest-beta.
Scale in, rather than going all at once. The regulatory clock is uncertain. A position sized for that uncertainty and added to on further weakness is more durable than a full commitment today.
Cheap Investor Scorecard
- PJM refiles with FERC within 30 days: watch for a revised proposal by early November
- VST forward P/E stays below 15x: current entry is historically inexpensive
- CEG 2026 EPS guidance maintained: $11.50-$12.50 is the anchor
- PJM capacity prices for 2028/29: next auction results will confirm or deny the shortage story
- Hyperscaler PPA announcements: any new nuclear or gas deal re-rates the group
- FERC suspension lifted before February 28: an early approval is upside for the timeline
- VST buyback execution: authorizations matter, but treat them as flexibility, not a guarantee
Bottom Line
If the PJM backstop stays stuck, the plants already running collect the windfall. If it gets fixed quickly, the shortage is still real enough to support elevated prices. Either outcome benefits the generators who own capacity today. The group has been revalued as though the AI power trade is over. The grid says otherwise.