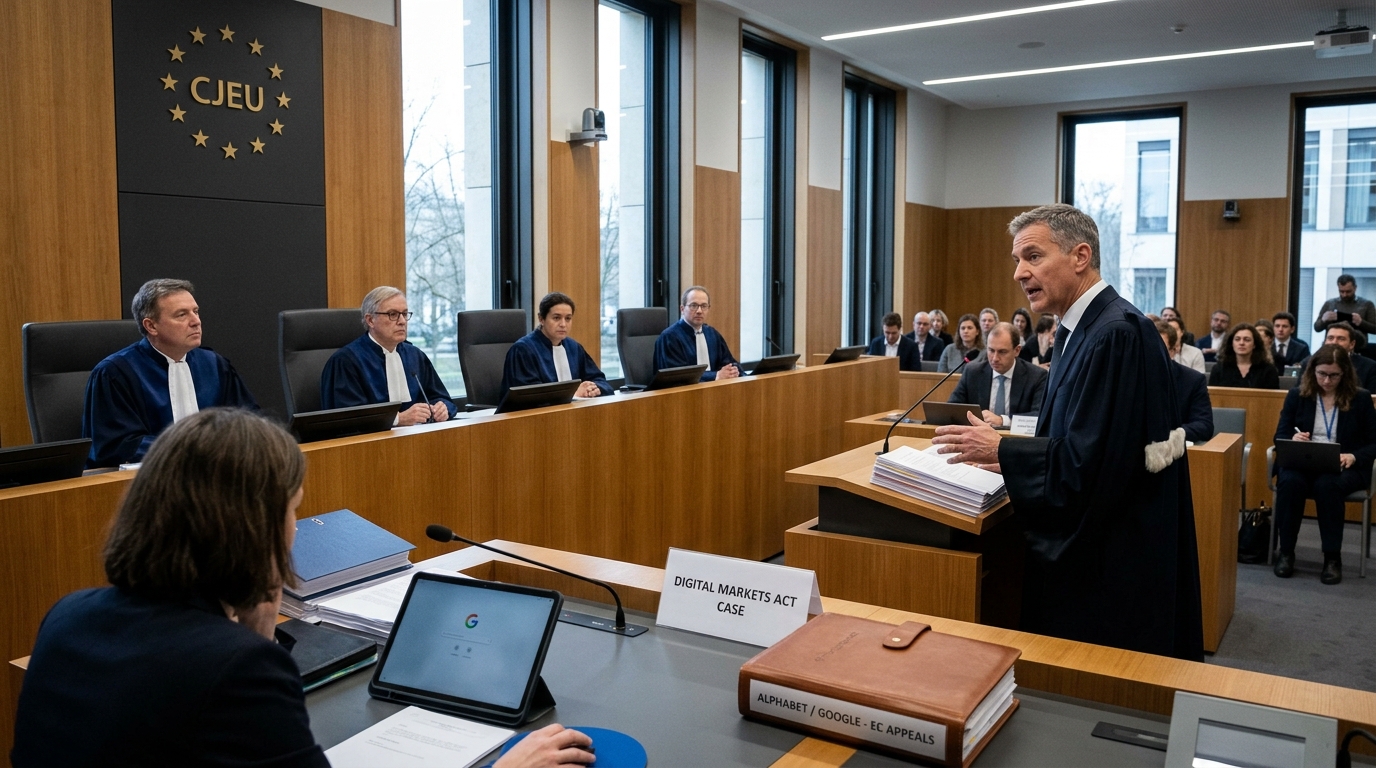
On Monday, Alphabet filed two cases at the EU General Court in Luxembourg, seeking to annul European Commission specification measures adopted on July 16 under the Digital Markets Act. Google filed the appeals against two July 16 decisions: one sets binding measures aimed at ensuring rival AI assistants can access key Android features on equal terms with Google’s own AI services, such as Gemini, and the other sets binding measures requiring Google to share anonymised search data with eligible online search engines and AI chatbots offering search functionalities, with implementation starting in January 2027. Google’s stated grounds are privacy and security. Oliver Bethell, Google’s senior director of competition, warned that sharing personal queries without adequate safeguards would cause irreversible harm to user privacy.
The privacy argument is not cynical. It may even be legally sound. But long-term investors should look past the courtroom and ask a harder question: if regulators succeed in prying open Android and the search data vault, how much of Google’s business actually survives on the strength of its product?
The answer, examined honestly, is uncomfortable. The structural risk sits in the distribution agreements: if Google can no longer pay to be the default engine on iOS or Android OEM devices, the roughly 91% all-device market share, held together partly by contractual defaults rather than organic switching costs, becomes considerably more contested. The mobile gap between Google and every rival traces directly to default search placement on Android handsets and Safari on iOS. That is not a moat built from better algorithms alone. It is a moat built from contracts.
Google pays to remain the default search engine on Safari, and to remain the preset choice across key Apple search access points, because that placement captures a large share of the queries flowing into Google Search, along with the ad clicks and behavioral data that come with them, and it protects the advertising revenue that funds almost everything Alphabet does. In 2022, that placement cost Google roughly $20 billion for Apple alone.
The European measures cut at precisely this structure. The first Commission measure aims to ensure that rival AI services can compete with Google’s own AI services, such as Gemini, by having equal access to features on Android devices; the second aims to give third-party search engines access to search data that only Google Search can collect at scale. The contested measure requires Google to share anonymised ranking, query, click, and view data with eligible search competitors, including qualifying AI chatbots offering search functionalities. For OpenAI and Perplexity, that data is the very ingredient they most lack: the accumulated behavioral signal that teaches a search engine which results humans actually find useful.
Six days before the Luxembourg filing, the UK Competition and Markets Authority added its own pressure. The CMA’s updated proposals would require Google to present a choice screen at first use of Android devices and Chrome, then prompt users annually, and would allow AI assistants that meet relevant technical and security criteria to appear on the same screen as search engines. AI assistants meeting those criteria, such as ChatGPT and Perplexity, would appear on the same choice screen alongside search engines. The market reacted immediately: the CMA proposal directly threatens Google’s core search distribution advantage, and GOOG fell 3.58% on September 23 when the news broke.
None of this is a death sentence for Alphabet. Evercore ISI found Google’s search market penetration expanding from 70% to 75% between August 2025 and March 2026, while ChatGPT’s search presence contracted from 13% to 11% over the same period. The product is genuinely good. The question is whether it is good enough to hold an overwhelming share of queries when Android stops being a walled distribution channel.
A disciplined investor thinking in five-year increments has to weight two outcomes. In the first, Google wins or delays the Luxembourg cases long enough that Gemini’s AI integration cements a new kind of loyalty rooted in product quality rather than default placement. In the second, regulators force open the distribution layer just as OpenAI and Perplexity are capable enough to convert newly free users at scale. The first outcome rewards patience. The second resets the search business structurally, not cyclically. The filing in Luxembourg is Alphabet’s bet on the first. Investors should decide whether they share that conviction before the court’s calendar forces the question.