September 29, 2026
Bonus Content: Vail’s Pass Sales Are Down 12%. Is the Stock Finally Cheap Enough?
You’ve seen this movie before.
A massive IPO hits. Everyone piles into the hot new stock. And while they’re distracted, the smart money picks up the stocks that just got sold off to fund those positions.
That’s exactly what happened Friday.
SPCX closed up 19%. The rest of the space sector got obliterated. Rocket Lab: down 10%. Firefly: down 18%. Virgin Galactic: down 34%.
Textbook institutional rotation. Mechanical. Temporary. And it almost always creates a window in quality names that have nothing fundamentally wrong with them.
Tim Bohen has spent 20+ years finding exactly these windows. Tesla at $37. Plug Power before 1,500%. NIO before 1,600%.
He just put together a free training on the 5 space stocks he’s watching right now – before the rotation reverses and the window closes.
P.S. Rocket Lab joins the Nasdaq-100 on June 22. Forced institutional buying regardless of price. Tim covers exactly what that means in the training.
Vail’s Pass Sales Are Down 12%. Is the Stock Finally Cheap Enough?
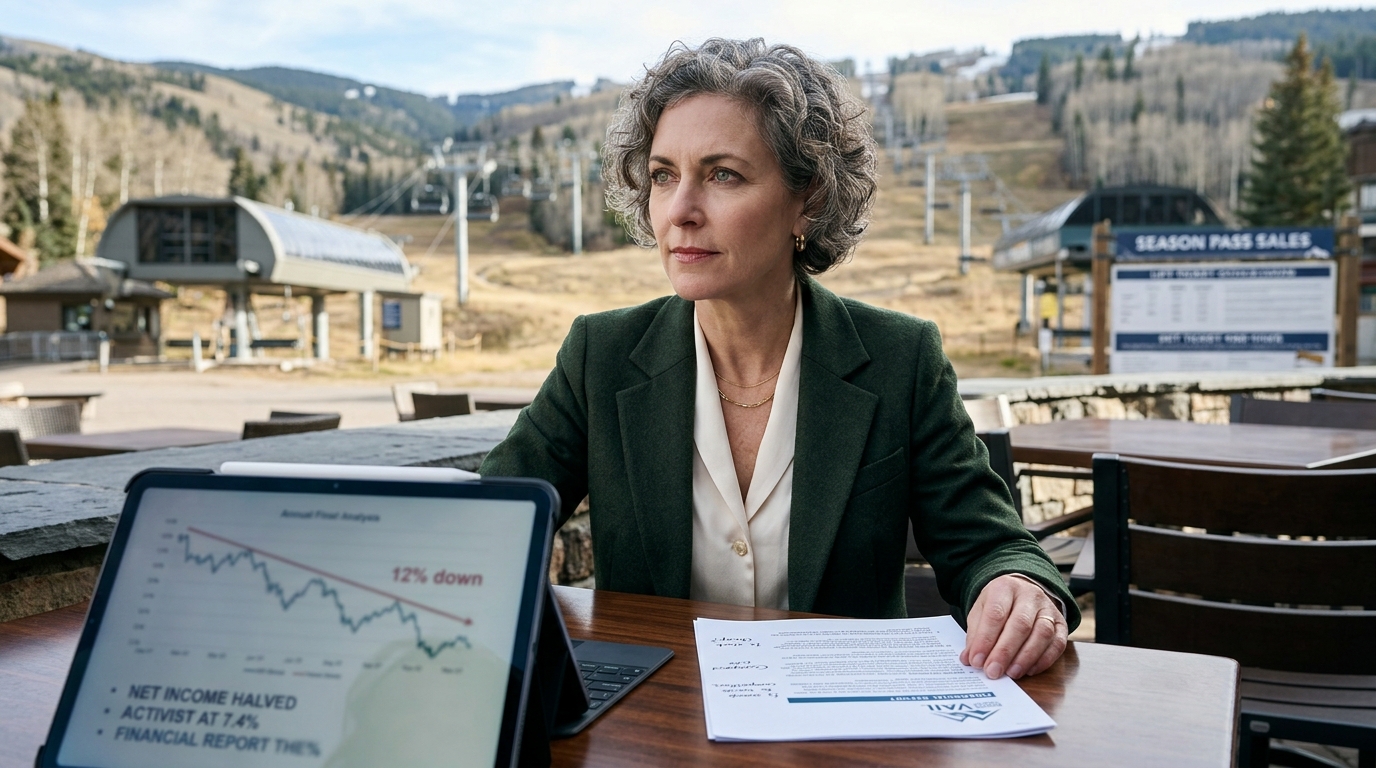
Hey there, bargain hunter. Vail Resorts dropped its full-year numbers on Monday evening, and the headline figure activists have been waiting on landed right on cue: pass unit sales for the coming 2026/2027 North American ski season are down 12% through September 18. The stock slipped overnight. Now you have to decide whether that is a reason to run or a reason to look harder.
Scoreboard
Net income attributable to Vail Resorts fell to $147.5 million for fiscal 2026, compared to $280.0 million in the prior year. That is a 47% collapse in a single year. Resort Reported EBITDA came in at $745.7 million, down from $844.1 million in fiscal 2025, and includes $11 million of one-time costs tied to the company’s resource efficiency transformation plan.
Pass product unit sales through September 18, 2026 for the upcoming 2026/2027 North American ski season decreased approximately 12%, days sold decreased approximately 10%, and sales dollars decreased approximately 6%, compared to the prior year period through September 19, 2025. That last figure matters most: dollars only fell 6% even as units fell 12%, meaning the buyers who did commit spent more per pass.
The Real Reason
Full-year lift revenue fell 3.5% even as skier visitation declined 13.4%. The gap between those two numbers is the advance-commitment model doing exactly what it was designed to do: smooth revenue even when mountains sit half-empty. Pass revenue rose about 3.9% for the full year, helping offset weaker traffic.
Management believes the 12% pass unit decline reflects delayed decision-making by customers rather than a decrease in skiing intent, with potential recovery through lift ticket sales. That may be true. It may also be what you say when two consecutive historically bad winters have spooked your most loyal customers into waiting to see actual snow.
The Business, Briefly
Vail operates 42 mountain resorts across four countries. Its Epic Pass is sold months before a single chair lift spins, locking in revenue regardless of weather. Between 2018 and 2024, pass revenue grew at a 15% CAGR, rising from 47% to 65% of mountain revenue. That advance-commitment flywheel is the reason this company trades at a premium to any normal leisure operator. The risk is what happens when two brutal winters in a row train pass buyers to wait.
Key Metrics
- FY26 net income: $147.5 million (vs. $280.0 million in FY25)
- FY26 Resort EBITDA: $745.7 million (vs. $844.1 million in FY25)
- Total skier visitation declined 13.4% in fiscal 2026.
- Net leverage stands at 3.9 times trailing 12-month Total Reported EBITDA as of July 31, with a target of approximately 3.5 times by fiscal year-end 2027.
- Dividend yield is about 6.4%, based on the current $8.88 annual dividend rate and recent share prices.
- Fiscal 2027 guidance: net income of $158 million to $233 million and Resort Reported EBITDA of $805 million to $865 million, including an estimated $14 million of one-time costs.
Is It Cheap?
MTN trades around $138, giving the company a market cap of roughly $4.9 billion. At the midpoint of FY2027 Resort Reported EBITDA guidance, you are paying roughly 5.7 times forward EBITDA. That is not obviously expensive for a business with irreplaceable physical assets and a history of 15% pass revenue compounding. But it is not a screaming discount either, particularly with leverage at 3.9 times and pass units still falling heading into the season that is supposed to prove recovery.
The analyst consensus price target sits at $174.90, implying about 27% upside from current levels. The 52-week range tells you where the real fear is: the stock has traded between $124.38 and $175.51 over the past year. You are buying near the bottom of that band.
The Activist Factor
Oasis Management increased its stake on September 22 from 6.2% to 7.4%, according to an SEC filing. The Hong Kong-based hedge fund now reports beneficial ownership of about 2,623,912 shares. That is a firm conviction bet, placed after two terrible winters and with pass data continuing to worsen. Oasis says a reconstituted board would help Vail achieve improved operational efficiency, enhanced food and beverage offerings, stronger partnerships with host communities, and expanded year-round programming.
Bull / Base / Bear
Bull: Normal snowfall in 2026/2027 restores visitation, lift ticket revenue converts reluctant pass buyers, and EBITDA reaches the top of the $865 million guidance band. Oasis forces capital allocation changes. You collect a dividend around 6%-7% while you wait.
Base: Weather is mediocre, pass unit declines stabilize but do not reverse, EBITDA lands near the $835 million midpoint, and the proxy fight produces one or two board seats without wholesale change. Stock drifts toward $150.
Bear: A third consecutive bad winter hits. Pass units fall another 10% next September. Leverage at 3.9 times limits flexibility. The dividend becomes a conversation item. Stock tests $110.
Action Plan
This is a weather-binary position right now. If you buy here, you are making a bet that two historically bad winters are an anomaly, not a climate trend. The dividend provides compensation while you wait, but it is not risk-free at 3.9 times leverage.
Scale in cautiously: a half position near current levels, a second tranche only if the stock breaks below $115 or if November snowpack data shows meaningful improvement. Do not chase on proxy fight excitement alone.
Cheap Investor Checklist
- Pass unit sales: watch the next update for any improvement from the current 12% decline
- November snowpack: western U.S. early-season conditions are the single leading indicator
- Net leverage: needs to track toward 3.5 times by July 2027 as guided
- Dividend safety: current payout requires stable EBITDA above $700 million
- Oasis proxy outcome: board seat count determines pace of any operational change
- Lift ticket conversion: can walk-up revenue offset lost pass units this season?
- FY2027 EBITDA vs. guidance midpoint: $835 million is the number to track quarterly
Bottom Line
If the next two winters are average, MTN around $138 with a dividend yield around 6%-7% and activist pressure for better capital allocation looks like a reasonable bet. If the Rockies serve up a third historically bad season, the math on the dividend and the debt gets uncomfortable fast. Buy a half position, leave room to add, and watch the snowpack like it is an earnings report. Because right now, it basically is.