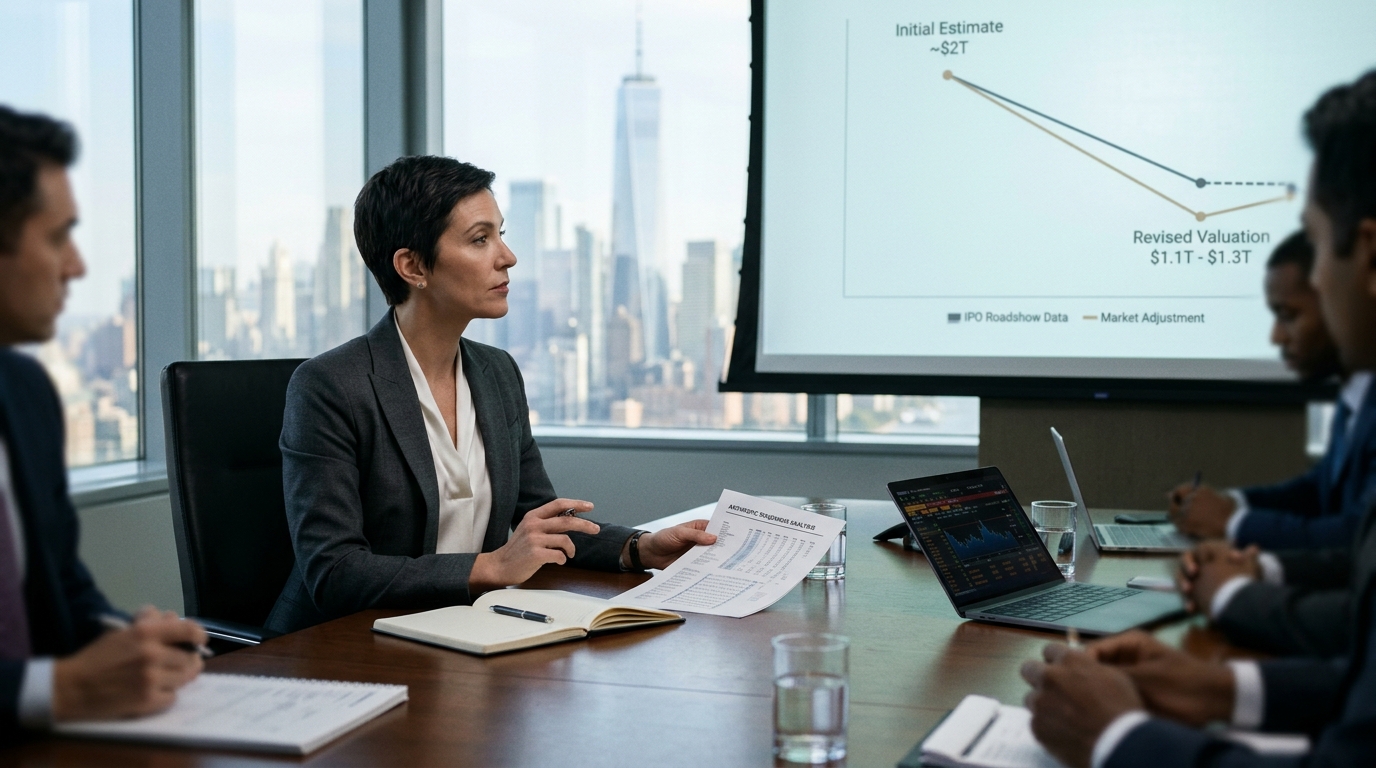
The roadshow window that opens this week for Anthropic’s Nasdaq IPO carries a number that tells you something important. Institutional investors who, just a few weeks ago, were discussing a $2 trillion valuation are now anchoring closer to $1.1 trillion to $1.3 trillion. That is not a rounding error. It is a verdict.
Why Wall Street Cares
Anthropic’s market listing will be a crucial test of investor confidence in the broader AI trade. Every major AI investment thesis, from Nvidia’s data center cycle to Amazon’s cloud bet, runs through assumptions about how much enterprises will ultimately pay for frontier models. If the market marks down Anthropic’s growth story at the gate, those assumptions get harder to defend across the entire sector.
The IPO comes after a sharp tech selloff last week. That backdrop alone would pressure any listing. But the size of the markdown here suggests something more specific than general market nerves.
The Bull Case
The growth figures are genuinely extraordinary. Anthropic reported revenue of $33.242 billion for the nine months ended September 30, 2026, a year-over-year growth rate the filing states at 1,206%.
The strategic backing is also hard to dismiss. Still, specific claims about a $26 billion combined private placement by Google, Nvidia, AMD, Broadcom, Micron, Microsoft, and TSMC, and an IPO-plus-placement total raise of $87 billion to $95 billion, are not supported by the company’s November 2, 2026 amended filing or by widely reported deal terms as of November 10, 2026. Until Anthropic files terms and the banks publicly describe any anchored orders, it is more accurate to say strategic and financial partners are central to both its funding and its compute supply chain.
The Bear Case
The compute commitments are where the investment committee conversation gets tense. The amended S-1 filing discloses approximately $895.4 billion in aggregate compute and infrastructure-related spending commitments under purchase agreements and leases. Approximately $69.8 billion of those commitments are due in the 12 months following September 30, 2026, and approximately $447.5 billion is expected to be incurred before December 31, 2030.
It is also important to separate commitments from current expense. In the amended filing, compute and infrastructure expense for the nine months ended September 30, 2026 was $18.808 billion. Third-quarter revenue was $16.956 billion, and the company reported a $567 million operating loss for the quarter. The unit economics moved in the wrong direction at exactly the wrong moment.
The Evidence
The valuation compression followed a clear sequence. Reporting in early October described Anthropic as targeting a valuation around $2 trillion. By mid-October, Reuters reported investors were discussing about $1.5 trillion. Bloomberg later reported prospective investors had moved to $1.2 trillion to $1.3 trillion, after earlier conversations around $1.4 trillion to $1.5 trillion.
The chaotic filing process this week did not help. Reuters reported that Anthropic briefly circulated a document showing plans to offer about 866.7 million shares at between $70 and $80 per share, then retracted the pricing details after informing banks that the information was inaccurate. A pricing correction this close to marketing leaves buyers without the anchor they need to size orders.
The Mavens’ View
At $2 trillion, the valuation would work out at roughly 29 times annualized Q3 revenue, and at $1.5 trillion it would be closer to roughly 22 times on the same annualized base. Professional investors are not debating whether Anthropic is growing fast. They are debating whether revenue growth that depends on locked-in compute commitments with major strategic partners constitutes an independent business or a structured arrangement between suppliers, distributors, and the issuer.
Discounting a projected $2 trillion fair value back at 15% annually would imply a $1.5 trillion present-day value. Apply a further 20% to 30% discount because IPO investors expect to buy below fair value, and you land on the $1.1 trillion to $1.2 trillion range now doing the rounds. That math is disciplined, not pessimistic.
What Investors Are Missing
The more interesting question is what this markdown does to the companies on the other side of Anthropic’s $895.4 billion compute and infrastructure commitments. Those commitments represent future revenue for major infrastructure suppliers and cloud platforms, and that revenue depends on Anthropic staying funded and growing. A lower IPO valuation raises the cost of future capital for Anthropic, which in turn tightens its ability to honor commitments that are already embedded in suppliers’ forward planning. The risk is circular in a way that has not fully entered the conversation.
Stocks to Watch
- Anthropic (ANT): Anthropic has said it intends to list its Class A common stock on the Nasdaq Global Select Market under the ticker ANT, but as of November 10, 2026 it has not publicly confirmed a specific listing date. The final valuation, once confirmed terms replace the retracted pricing details, sets the reference point for every AI company that follows it public.
- Nvidia: A key supplier into the AI buildout that underpins Anthropic’s growth. Its exposure runs in both directions: a successful listing validates AI capex; a stumble questions it.
- Amazon: Anthropic has committed to spend at least $110 billion with Amazon Web Services over 10 years, through April 2036. Amazon’s cloud margins depend partly on Anthropic’s ability to keep paying that tab.
- Microsoft: Microsoft is among the strategic partners frequently cited in reporting around Anthropic’s compute ecosystem. The core question for investors is whether any large, long-dated compute commitments remain financeable if Anthropic’s cost of capital moves higher.
- Broadcom: Anthropic’s filing describes master equipment leases involving Broadcom, including arrangements used to procure specialized AI accelerators and associated components. But the specific claim that Broadcom holds $161.2 billion in equipment leases with Anthropic is not supported by the amended filing as written here, so it should not be stated as a fact.