Quick one.
You can grab my Smart Trade Options Checklist free today – normally $29.97.
It’s a one-page filter. Seven checks. Run it before you place any options trade and you’ll catch the bad ones before they cost you.
Print it. Keep it next to your screen. Use it on every trade.
Download your free copy right here.
Heads up: That link expires soon.
Good Trading,
Bill Poulos
P.S. The download link expires soon. Once it’s gone, the checklist goes back to $29.97. Grab it here.
Mortgage Rates Hit 7.28%. Homebuilders Are on Sale.
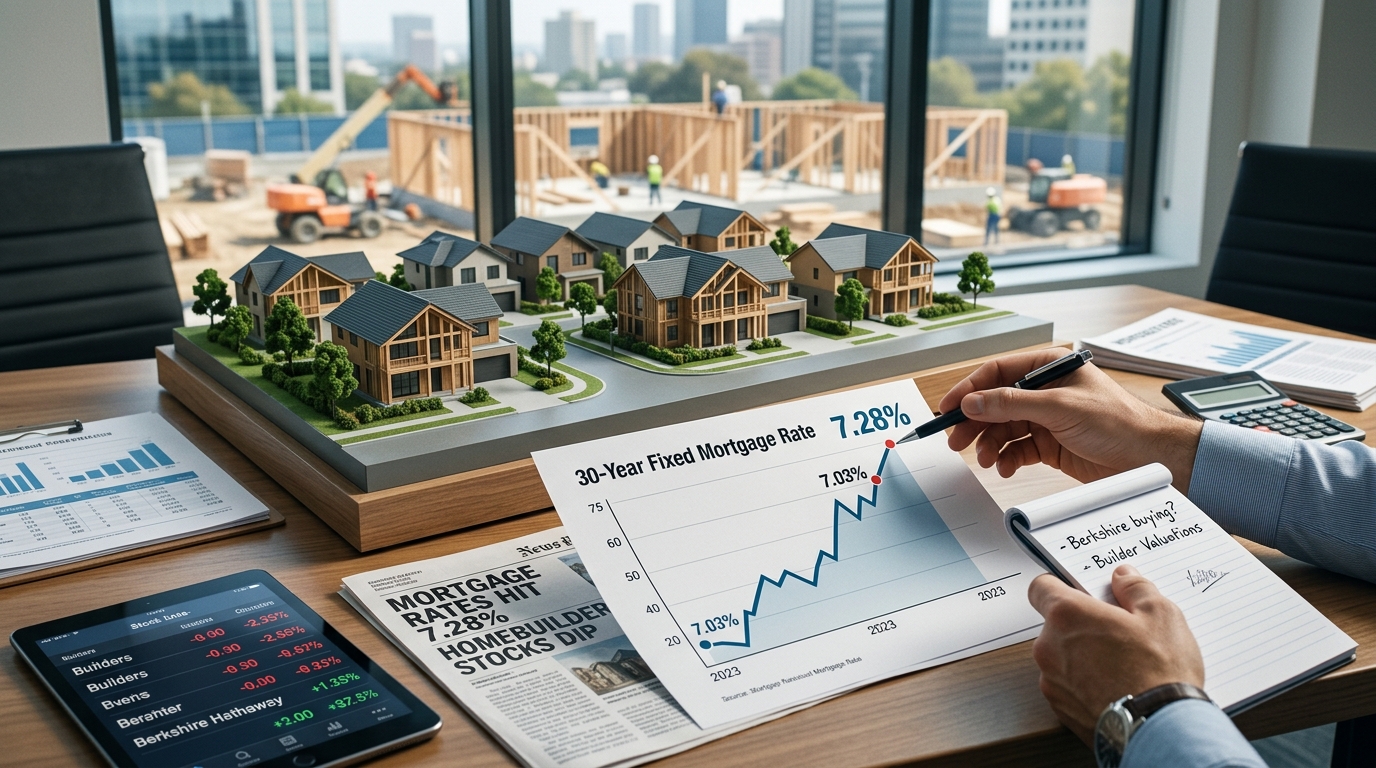
Hey there, bargain hunter. The number that matters this week is 7.28%. That is what Freddie Mac’s Primary Mortgage Market Survey put the 30-year fixed mortgage at as of October 1, a 25-basis-point jump in a single week from 7.03%, and the highest reading since November 22, 2023. A year ago, the same loan cost 6.34%. The weekly move was the largest in four years.
Scoreboard
- 30-year fixed: 7.28% (Freddie Mac, Oct. 1)
- 15-year fixed: 6.60%, up from 6.42% the week prior
- 10-year Treasury: closed September 30 at 5.29%, touched an intraday high above 5.30% on Oct. 1, its highest level since 2002
- LEN (Lennar): ~$82, down 22% year-to-date, 40% off its 12-month high
- DHI (D.R. Horton): ~$137, down roughly 3% in 2026
- PHM (PulteGroup): ~$116, trading near its 52-week low range
- ESNT (Essent Group): closed September 30 at $57.91, down over 8% in a single session, extending a 12-session losing streak
What Actually Happened
Mortgage rates do not move on Fed policy alone. They track the 10-year Treasury, and the 10-year has been in freefall upward all September, rising roughly 70 basis points in the month on fears about oil prices, inflation reacceleration, and government debt loads crossing $40 trillion. The bond market is reassessing fiscal risk, and the housing market is absorbing the collateral damage directly. Zillow revised its year-end rate forecast upward to 7.1% on the same day Freddie Mac printed 7.28%. The MBA’s competing survey hit 7.30%, confirming the move is broad-based, not a one-week quirk.
The Business: How Homebuilders Make Money (and Lose It)
Lennar, D.R. Horton, and PulteGroup sell new homes. When rates rise, the buyer pool contracts immediately. A payment on a $400,000 loan at 6.34% runs roughly $2,490 per month; at 7.28%, that same loan costs about $2,730. Builders respond by cutting base prices and layering in incentives, which compresses gross margins. Lennar’s Q3 average sale price was around $372,000, with about 12.0% baked into incentives to keep volume moving. Gross margin on home sales came in at 15.8% in Q3, and Q4 guidance is set at 15.5% to 16.0%. New orders fell 9% year over year in Q3. Volume and pricing both declined more than 3% against the year-ago period.
Mortgage insurers like Essent (ESNT) and MGIC (MTG) face a different but related squeeze. Higher rates reduce origination volume, which shrinks new insurance written. Essent’s default rate has been creeping: 2.12% in Q2 2025, 2.54% by Q1 2026. On the regulatory front, the FHFA has been publicly focused on borrowers’ all-in mortgage costs, including mortgage insurance premiums, which adds another layer of scrutiny on top of the rate pressure.
Is It Cheap?
Lennar trades at roughly 0.9 times book value, with book value per share around $90. That is a level where a 20-year historical average closer to 1.3 times would imply material upside if the cycle turns. Price-to-sales sits at 0.61. The balance sheet is not a disaster: $1.2 billion in homebuilding cash, debt-to-total-capital at 16.6%, and $3.1 billion in revolving credit capacity with $650 million currently drawn. D.R. Horton trades around 13 times trailing earnings. PulteGroup at roughly 11.8 times is the leanest of the three on that metric, with operating margins near 12.1%.
Here is the tell: Berkshire Hathaway has been buying Lennar steadily through late September, lifting its position to about 25.9 million combined shares and pushing it above the 10% ownership threshold that triggers accelerated SEC reporting. Recent purchases disclosed on Form 4 show Berkshire buying about $136 million of LEN over September 23 to September 25 at weighted-average prices in the roughly $81 per share area. That is not a trader’s move. It is a cyclical bet placed by a patient institution that has read housing cycles before.
Bull / Base / Bear
Bull: The 10-year yield peaks here or reverses. Rates fall to the 6.5% range by mid-2027, the lock-in effect unwinds, and homebuilder volumes recover sharply. LEN re-rates toward book value.
Base: Rates stay in the 7% zone through Q1 2027. Builders hold volume through incentives, margins compress another 50 to 100 basis points, earnings estimates step down another 10 to 15%, and stocks grind sideways with dividends cushioning the wait.
Bear: Treasury yields push toward 5.75% or beyond. Cancellation rates accelerate, land write-downs appear, and earnings fall hard enough to make current valuations look less cheap than the multiples suggest.
Action Plan
Do not chase a falling rate bet. But if you want exposure to the eventual turn, scale in on further weakness rather than buying all at once. LEN at or below book value with Berkshire as a co-investor is a better entry than most rate-recovery plays in this sector. PHM is the margin quality story. DHI is the volume scale play. For ESNT, the persistency rate is genuinely compelling at 84.7%, but wait for rate stabilization before adding aggressively.
Cheap Investor Checklist
- 10-year Treasury yield: watch the 5.50% level as the next pain threshold for mortgage rates
- Lennar Q4 gross margin: guidance band 15.5% to 16.0%; any miss widens the bear case
- Berkshire 13F (mid-November): confirms whether the buying campaign continued into Q4
- LEN price-to-book: entry at or below 0.9x is the historical signal; above 1.1x starts to close the discount
- MBA weekly mortgage applications: sustained weekly declines above 10% signal buyer paralysis
- Cancellation rates at DHI and LEN: rising above 25% would flag demand deterioration beyond incentive-fix range
- ESNT default rate: watch for any acceleration past 3.0% as the reserve-building trigger
Bottom Line
If the 10-year yield stabilizes or retreats, homebuilders at current prices look like a classic late-cycle value entry. If yields keep climbing toward 5.75%, the pain trade continues regardless of how cheap the multiples look on paper. Berkshire’s buying is the strongest data point in favor of patience here. The question is not whether to own homebuilders at sub-book value. The question is whether you can afford to wait out the bond market first.