September 30, 2026
Bonus Content: Canada’s Beer, Dairy and Motorcycles Are Now Banned
As copper breaks records… capital is turning toward early-stage discovery stories that are only beginning to unfold.
One under-the-radar Canadian copper company – still trading undiscovered below $2 per share – is emerging at exactly the right moment.
The company controls a historic copper belt in Canada’s Yukon that produced for decades… and is now being explored as a unified system for the first time.
And the results are starting to speak for themselves:
- High-grade copper confirmed at the flagship
- Past-producing areas getting a fresh look via the drill bit
- Multiple additional targets advancing toward drilling
Multiple rigs are already operating. More are being added. And the company is fully funded through the end of 2027 for its biggest exploration program yet.
More rigs. More drilling. Multiple shots at discovery – from a copper stock still trading below $2.
We’ve compiled a FREE online report detailing the high-grade results, the district-scale opportunity, and where the 2026-27 drill campaign goes next – including our exclusive interview with the company’s CEO.
Click here for instant access – and get the full story before the next round of drill results arrives.
Canada’s Beer, Dairy and Motorcycles Are Now Banned
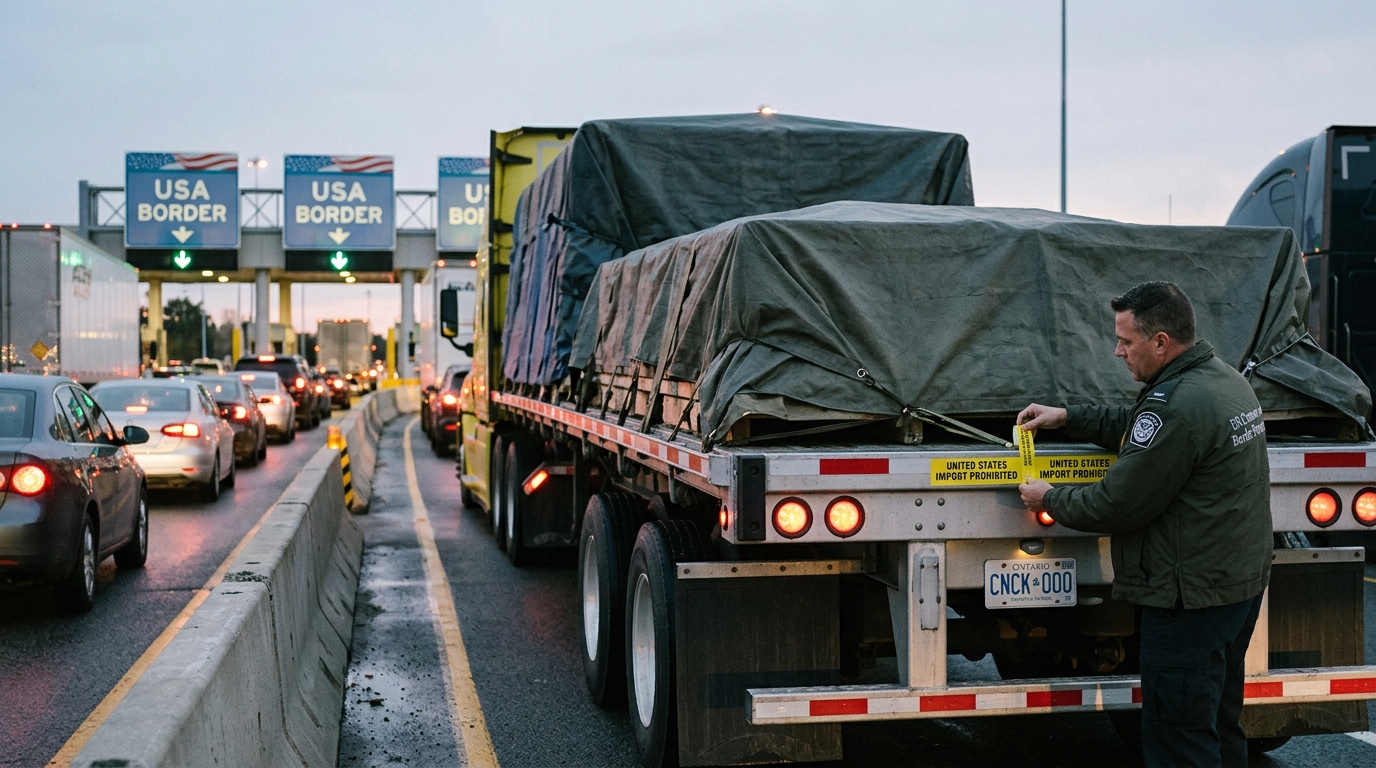
Hey there, bargain hunter. At 12:01 a.m. Tuesday, the US stopped letting certain Canadian goods cross the border. Not taxed. Not surcharged. Banned.
Scoreboard
Three presidential proclamations signed September 8 converted parts of the existing 50% Section 338 duties into full prohibitions: certain Canadian alcoholic beverages and certain dairy products are now excluded from importation entirely, effective 12:01 a.m. ET on September 29. A third proclamation excludes a narrow motor-vehicle-related line item, motorcycles (including mopeds) with piston engines over 800cc. USMCA origin does not exempt covered goods. Canada has been retaliating dollar-for-dollar on C$27.6 billion of US goods since September 8.
What Actually Happened
What makes this different from every earlier round is the shift from taxation to prohibition. A 50% duty still allows a shipment through at a higher cost. An outright ban does not. The market hasn’t fully processed that distinction yet.
The banned goods include motorcycles and mopeds with petrol engines over 800cc, whey and modified whey, molasses, and a long list of alcoholic beverages packaged for direct consumption, covering beer, cider, wine, whisky and vodka. The ban covers just under $1 billion of Canadian imports based on 2025 trade.
Independent spirit distillers and beer brewers are expected to bear the brunt of the ban more than some well-known Canadian brands that may have workarounds. Crown Royal, for example, can ship whisky in bulk for processing, bypassing the ban entirely. That workaround matters: the volume gap sits with the brands that cannot reroute.
Who Picks Up the Volume
American beverage stocks like Constellation Brands and Molson Coors could benefit from reduced Canadian competition and increased shelf space for domestic products. That framing is correct but incomplete. TAP is a complicated beneficiary.
On September 29, the ban hit Molson Coors (TAP) directly by stopping new imports of covered goods, including packaged Canadian beer under covered tariff lines. Molson Coors faces limited risk from the ban itself, but declining overall beer demand continues to cloud the earnings picture. TAP’s price-to-sales ratio is around 0.63. Cheaper, yes. Cleaner story, no.
The cleaner read is on whey. Kraft Heinz is exposed to dairy input costs on the demand side, while US domestic dairy suppliers stand to benefit from the supply gap. Shelf space in beverages follows a similar logic: Constellation Brands reported that through July of its fiscal 2026 it grew volume share in 49 of 50 states, giving it the retail positioning to absorb freed-up facings. STZ currently trades at roughly 9.6x forward earnings based on widely quoted market data.
Is It Cheap?
TAP at about 0.63x sales is historically cheap but carries real structural headwinds: volume declines, ongoing pressure in the category, and the dual-sided Canada exposure. STZ at under 10x forward earnings trades at a discount to where the market often values branded Consumer Staples leaders, with its Mexico beer operations expecting aluminum tariff relief in fiscal 2027 as discussed by management in April 2026. The Canada ban does not hurt STZ directly; it frees up shelf space STZ’s distribution network is built to fill.
Bull / Base / Bear
- Bull: The volume hole from covered Canadian beer and spirits holds absent a negotiated reversal. US brewers and distillers with domestic capacity capture that demand within two to four quarters. Whey processors see spot-price lift as import supply drops.
- Base: The ban holds but trade talks produce a partial agreement in Q1 2027 that reopens select categories. Shelf space gains for US brands prove modest relative to overall beer demand softness.
- Bear: Further retaliation closes additional US export channels, hurting companies like STZ that sell into Canada and blunting any domestic volume gain.
Action Plan
STZ is the cleaner trade: no Canadian import exposure, discounted multiple, and strong shelf presence. Start a position in thirds: one-third now at current levels, one-third on a confirming volume read in Q4 scanner data, hold the final third for any trade-noise selloff.
TAP is a watch-and-wait. The valuation is compressed, but ongoing volume declines create a drag. It earns a spot on the watchlist at $35 or below.
Cheap Investor Checklist
- Ban status: In force as of September 29. No reversal announced.
- TAP P/S ratio: ~0.63x.
- STZ forward P/E: ~9.6x.
- Covered import set: About $967 million of Canadian imports based on 2025 numbers.
- Ottawa retaliation package: C$27.6 billion, in force since September 8.
- Watch: US retail scanner data for beer and spirits shelf-space resets in October.
- Watch: Any USMCA negotiation restart that could reopen banned categories.
Bottom Line
A tariff adjusts the price. A ban removes the product. If the ban holds for two quarters, US producers are not competing against cheaper Canadian goods; they are filling a vacancy. That is a different kind of opportunity. STZ has the shelf position and the discounted multiple to make it interesting today. TAP has the valuation but too many other problems to own ahead of a catalyst.