Hey there, bargain hunter. A stock that fell 26% in a single session, is down roughly 50% from its 52-week high near $1,227, and still earns about a 90% segment margin is not automatically a buy. But it is worth running the numbers before you walk away.
Scoreboard
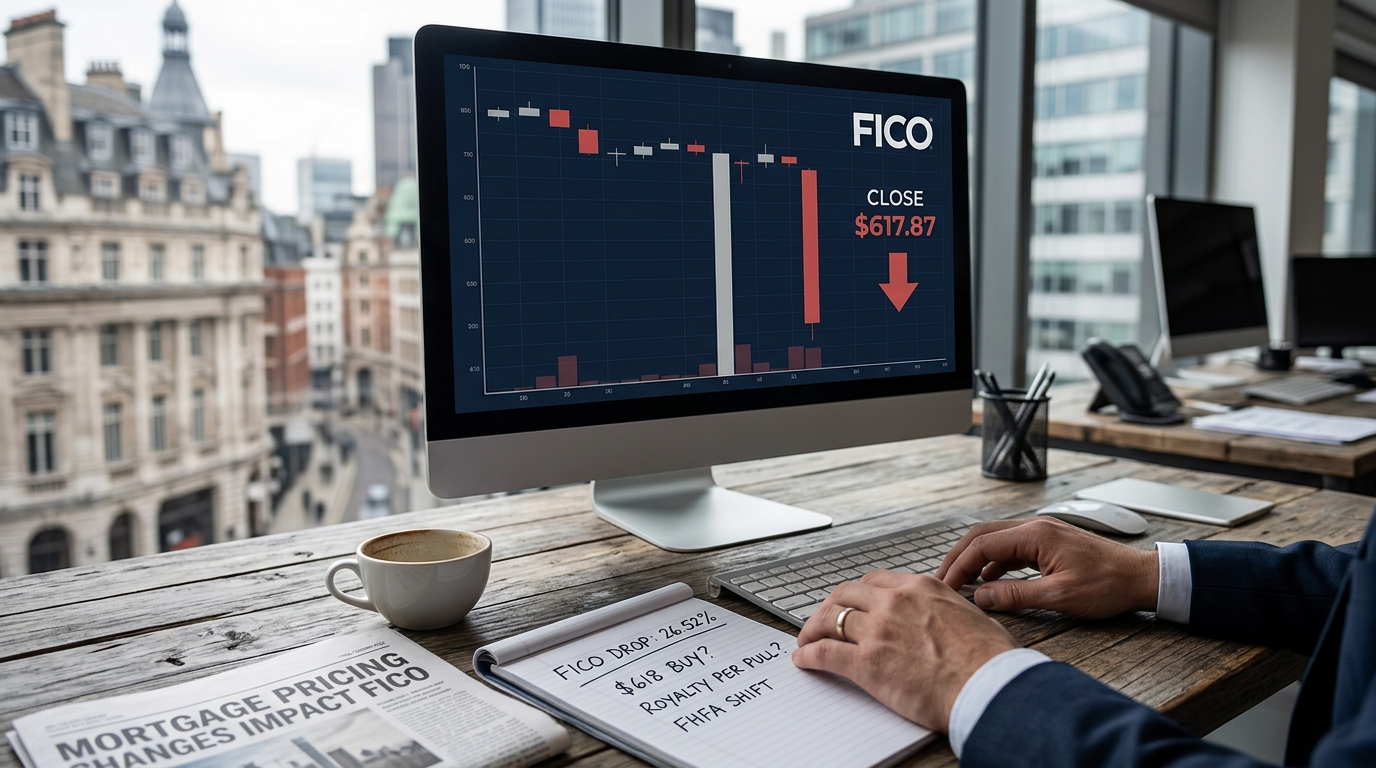
Fair Isaac closed Tuesday at $617.87, down 26.52% on the day and one of its sharpest single-session drops in years. The catalyst was FHFA Director Bill Pulte, who posted on X that Fannie Mae and Freddie Mac will move to a single pricing grid, with VantageScore joining Classic FICO inside that grid. Pulte did not provide a timeline for when that unified single-family pricing grid would go into effect. Separately, TransUnion set $0.99-per-pull pricing for VantageScore 4.0 for mortgage originations in March 2026. Equifax fell about 2.65% after Goldman Sachs cut its target to $171 from $199, keeping a Neutral rating.
What Actually Happened
The market was not surprised by competition existing. It was surprised by the pricing architecture shifting. As long as FICO and VantageScore sat on separate grids, lenders had a structural reason to keep paying FICO’s higher wholesale mortgage royalty. A single unified grid reduces that friction. Borrowers whose VantageScore 4.0 exceeds their Classic FICO score can qualify for a more favorable pricing bucket when lenders select that model, giving VantageScore a tailwind it previously lacked.
Rocket Mortgage confirmed the direction of travel the same morning, announcing it will default to VantageScore 4.0 in Q4 for all eligible direct-to-consumer loans, including Fannie Mae, Freddie Mac, and VA mortgages. Rocket said it tested 1.4 million credit reports side by side. Borrowers who saved money with VantageScore saved an average of $1,600 at closing. The liability logic is simple: put a borrower in a costlier loan when a cheaper alternative existed, and you own that decision.
The Business: How FICO Makes Money
Fair Isaac runs two segments. Software contributes roughly $197 million per quarter, growing slowly as legacy contracts roll off. Scores is the engine: $458.9 million of the $674.2 million in Q3 fiscal 2026 revenue, operating at about a 90% segment margin that functions essentially as a pure royalty stream. FICO licenses its algorithm to Equifax, Experian, and TransUnion, which distribute the score to lenders. Every mortgage origination that used Classic FICO generated a royalty. Management raised fiscal 2026 guidance to $2.53 billion in revenue; the company’s GAAP EPS guidance is not stated here because it is not consistently disclosed in a single, easily verifiable figure in the company’s primary filings and releases. Mortgage origination revenue grew 97% year over year in Q3.
That 97% growth was built largely on price increases, not volume. CEO Will Lansing raised the wholesale mortgage royalty to $4.95 per score for mortgage originations for calendar 2025. Lenders paid because they had no GSE-approved alternative. Now they do.
Is It Cheap?
At $618, the question is less about the headline P/E and more about whether the Scores segment retains anything close to its current revenue per pull, or whether lenders commoditize it.
- If 30% of mortgage volume migrates to VantageScore, mortgage royalty revenue falls materially, and the justification for even 20x earnings weakens.
- If mortgage scores turn out to be a small share of total pulls and lenders keep FICO alongside VantageScore as MBS investor demand requires, the cash flow impact is manageable.
- Platform ARR was growing 62% year over year to $413 million as of Q3, now at about half of total Software ARR. That segment is not in the crosshairs.
Bull / Base / Bear
Bull: FICO stays embedded in MBS documentation requirements even when VantageScore is used for origination pricing. Two scores per loan means FICO volume holds, and the company cuts royalties modestly to compete while protecting margin with Platform growth. Stock recovers toward $900.
Base: Lenders gradually shift 30-40% of eligible mortgage volume to VantageScore over 18 months. FICO defends auto and card scoring, Platform ARR continues compounding, and fiscal 2027 earnings settle 15-20% below the prior trajectory. Stock range: $550-$750.
Bear: The FHFA timeline accelerates, and tri-merge requirements loosen. FICO becomes one of two accepted models rather than the standard. The royalty line compresses structurally. Stock tests $400.
Action Plan
Do not chase the open tomorrow. The implementation timeline for the unified grid remains vague, which means volatility in both directions is probable. A scale-in approach makes more sense than a single entry. If you want exposure, consider a first tranche at current levels only if you are prepared to add at $500 if the bear case gains traction over the next quarter.
Cheap Investor Checklist
- Does FICO remain required in MBS documentation even when VantageScore prices the loan?
- Does the $0.99 VantageScore 4.0 mortgage origination pricing hold, or do bureaus undercut further?
- How many of TransUnion’s VantageScore adopters run it as a replacement versus alongside FICO?
- Does tri-merge stay in place during the interim phase, as FHFA has said it will?
- Does Platform ARR stay near half of Software ARR, insulating the income statement from Scores pressure?
- Does FICO cut its mortgage royalty below $4.95 to defend volume, and by how much?
- Does Rocket Mortgage’s Q4 default trigger a domino among the other top-10 lenders?
Bottom Line
If FICO scores still ride every mortgage as a secondary documentation requirement, the royalty math is painful but survivable and $618 is almost certainly too cheap. If the unified grid becomes genuine winner-take-most competition and Rocket’s Q4 switch is the first of many, the prior multiple was the fiction, not the business. Watch the MBS investor documentation requirement first. Everything else follows from that answer.