September 15, 2026
Bonus Content: Vicor’s Factory Is Full. Two New Ones Need a Year.
Hey. It’s Alex Reid.
And I just held what could be arguably the most important event in my entire career…
In this event, I revealed Oracle…
A brand-new, first-of-its-kind breakthrough that helps us track the massive, sneaky bets of insiders right in the predictions market…
And reveals the stocks and options set to benefit the most!
The team and I worked long hours for months to put Oracle together…
We even ran beta tests for weeks, and the results were amazing!
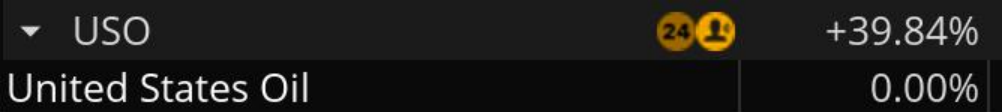
I’m talking about 39% on USO in 4 days…
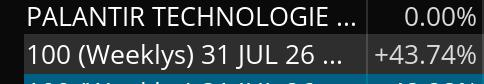
43% on PLTR in a day…
And 67% on WEN in 2 days…
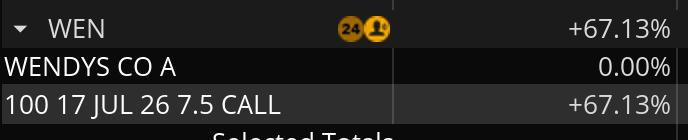
All with a regular brokerage account.
Of course there were smaller winners and those that didn’t work and we won’t be making reckless promises when it comes to trading…
But I gave anyone who joined the live event the chance to secure FREE access to Oracle!
And in the next few minutes…
You too can secure access at no cost!
Look…
Insiders are using the predictions market to hide their huge, sneaky bets at an insane rate.
The question is will you let this opportunity pass you by?
If you’d like to get a deep dive into how Oracle tracks these massive insider bets…
And secure access completely on the house…
To Better Trading,
Alex Reid
Vicor’s Factory Is Full. Two New Ones Need a Year.
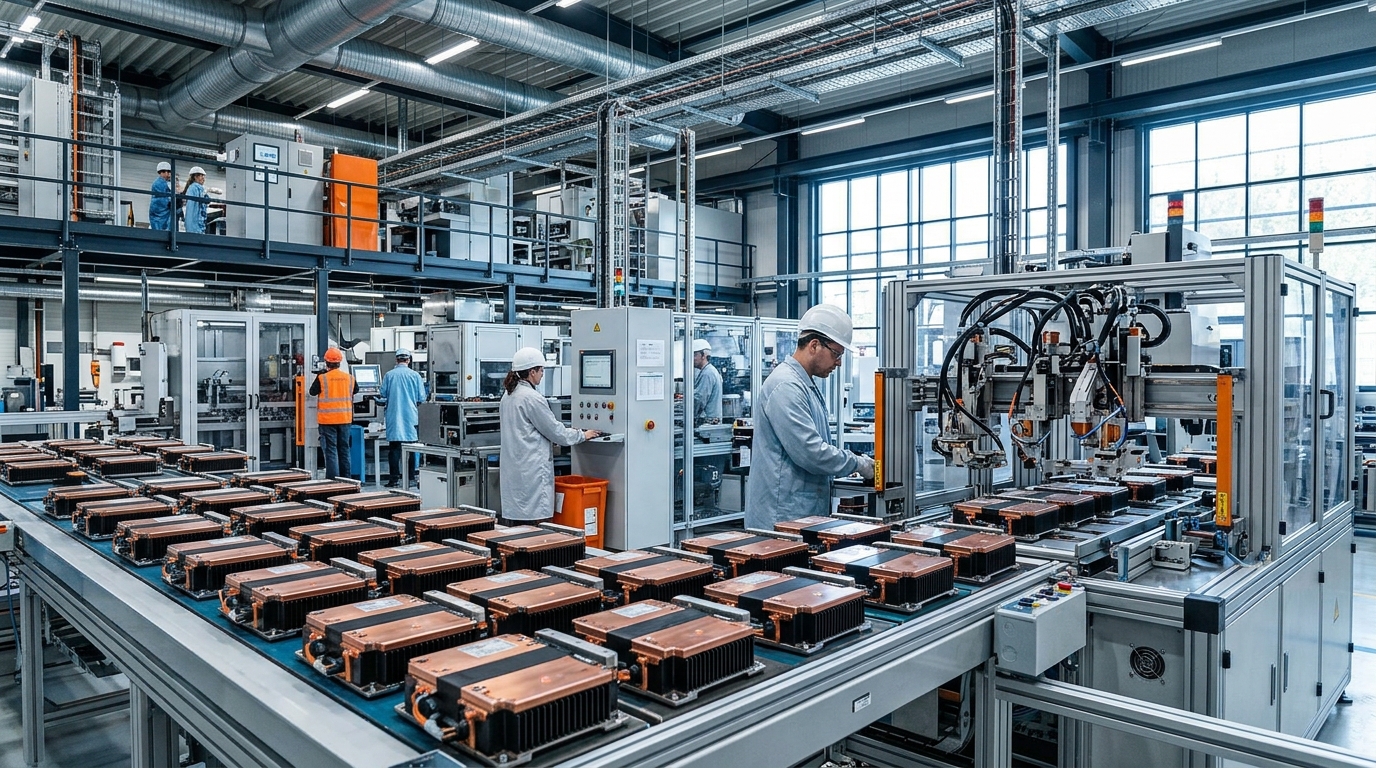
Hey there, bargain hunter. Vicor just told you demand for its power modules is overwhelming. The problem is it can’t build them fast enough, and the new factories it just bought won’t ship meaningful volume for about a year after initial deployment, which management said points to initial deployment in late 2027.
Scoreboard
Q2 2026 revenue came in at $143.4 million, up 26.9% sequentially and ahead of the roughly $138.7 million consensus estimate. EPS hit $1.04, beating estimates by about 68%. Management then raised full-year 2026 revenue guidance to over $600 million from an earlier target of roughly $570 million. The stock hit a 52-week high near $382.65 on June 30, 2026, pulled back sharply, and closed at $184.73 on September 14, 2026. That is about a 52% haircut from the peak, despite fundamentals that keep improving.
The Real Reason It Matters
The guidance raise is only half the story. The more important signal came on September 11, 2026, when Vicor announced it is buying two New Hampshire sites to support ChiP Fab-2 and Fab-3, with a combined footprint of nearly one million square feet. The reason: ChiP Fab-1 in Andover, Massachusetts was built out to 320,000 square feet and management said utilization is approaching capacity. Backlog hit $379.7 million in Q2, up 26% sequentially and 145% year over year. Book-to-bill stayed above 1.0. In plain English: customers are ordering far more than Vicor can currently produce.
What the Business Actually Does
Vicor makes high-density power modules that convert electricity efficiently at the processor level inside AI servers and GPU clusters. Its Vertical Power Delivery architecture places the power converter physically beneath the chip, cutting the resistance losses that plague conventional designs. Each AI processor in a dense cluster can demand hundreds of amps. Vicor says its second-generation VPD solution is delivering about 3 amps per square millimeter of current density, with a target of 5 A/mm2 by early 2027, versus roughly 1 A/mm2 for traditional approaches. That gap is the moat.
Key Numbers
- Q2 gross margin: 58%, up 280 basis points sequentially
- Advanced Products revenue: $94.2 million, up 45% sequentially, representing 65.7% of total sales
- Royalty income in Q2: $30.4 million
- Cash: $453.6 million, essentially debt-free
- Long-term revenue target: $2.5 billion at 70% gross margin
- Management targets 60-65% gross margin as AI module volumes scale near term
Is It Cheap?
At roughly $185, VICR trades around 59 times trailing earnings. That is not a value stock by any standard measure. Monolithic Power, a close listed peer, was up about 49% year to date as of mid-July. Vicor was up much more on the year into the summer, before the pullback. The royalty stream is nearly 100% margin and still growing, but Vicor has also been explicit that licensing timing is tied to its ITC enforcement cycle. The company has said a second ITC case is expected to reach a final determination in 2027, and the bull case needs that to happen on schedule.
Bull / Base / Bear
Bull: Second ITC case resolves favorably, adding another major licensing payment in 2027. Fab-2 hits the one-year lead time to initial deployment. Royalties accelerate while product revenue compounds. The $2.5 billion long-term target starts looking credible before 2030.
Base: Over $600 million in 2026 revenues, margins hold near 58%, Fab-2 delayed modestly. Stock recovers toward prior highs as capacity comes online.
Bear: Fab buildout takes longer than guided. A major hyperscaler designs around the IP or wins an ITC appeal. Royalty income steps down as licensing accounting normalizes in Q3. The stock at a premium multiple has no margin for error.
Action Plan
Do not chase the Fab-2 announcement pop. The stock already corrected about 52% from its peak, which creates a more reasonable entry than three months ago, but the royalty step-down in Q3 (to $5 million from $30.4 million in Q2) is a near-term earnings headwind. Scale in on weakness below $185 with a second tranche if the ITC ruling timeline slips and the stock reacts. Full position only once Fab-2 is clearly on a path from site acquisition to buildout and equipment deployment.
Cheap Investor Checklist
- Q3 revenue growth: targeting nearly 10% sequentially per management commentary
- Royalty income: watch for new licensees beyond the agreements already signed
- Backlog: needs to stay above $350 million to sustain bull thesis
- Fab-2 initial deployment: management cited a one-year lead time to initial deployment, implying late 2027 from the September 2026 announcement
- Gross margin trajectory: holding 58% or higher confirms product mix shift
- ITC second case target date: Vicor has pointed to 2027 as the final-determination year
- Cash burn on capex: $11.2 million in Q2, watch for acceleration
Bottom Line
If Vicor executes on Fab-2 on the stated one-year lead time to initial deployment and a second ITC win adds another licensing payment, the stock around $185 can look cheap relative to its long-term target. If the fab timeline slips and royalties flatten, you are paying a premium multiple for a company that physically cannot grow revenue fast enough to justify it. The backlog is real. The constraint is real too.