Hey there, bargain hunter. Swarmer, Inc. (SWMR) posted its Q3 earnings on Monday, November 10, 2026, and the headline numbers are not for the faint of heart.
Scoreboard
The company posted $25,554 in revenue, down from $35,771 a year earlier, and a net loss of $9.3 million, compared with a $3.4 million loss in the same period last year. Operating expenses rose to $9.4 million, driven in part by increased noncash stock-based compensation. The stock dipped after hours.
The Real Reason
None of that is the story. Swarmer is not trying to be a software-subscription business in 2026. It is trying to bolt a revenue-generating hardware company onto its autonomy software before the market notices the original entity barely exists. The Austin-based firm says its autonomy software has supported more than 100,000 combat missions in Ukraine since April 2024. The tech is battle-tested. The income statement is not.
Deep Dive
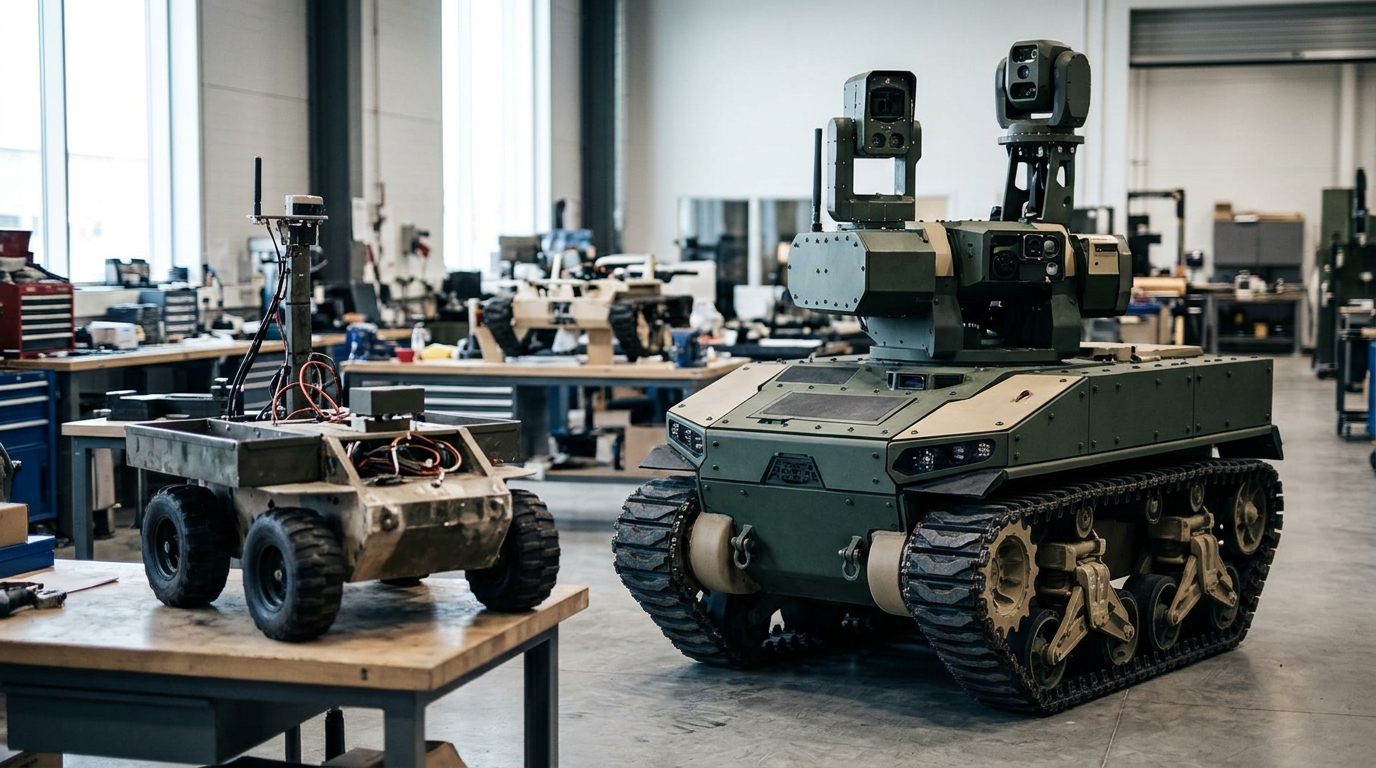
The acquisition signals Swarmer’s planned expansion into multi-domain autonomous systems by combining Ratel’s UGV manufacturing capabilities with Swarmer’s combat-proven autonomy software. Ratel holds a roughly 37% share of unmanned ground vehicle contract spending by Ukraine’s Defense Procurement Agency for the period from January 1 to April 18, 2026. Following closing, Swarmer intends to retain Ratel’s brand and operate it as an independent autonomous division, with its engineering and manufacturing functions remaining separate within Swarmer.
Ratel’s UGV backlog is one data point in a broader pattern of governments locking in multi-year autonomous and munitions supply before procurement windows close. NATO’s restocking cycle is already converting framework agreements into hard revenue for established defense manufacturers.
The Numbers That Matter
- Ratel’s preliminary, unaudited year-to-date revenue for the first three quarters of 2026 was $42.1 million, with $32.5 million in the third quarter.
- Management estimated Ratel’s fourth-quarter revenue at $35 million to $40 million, with operating margins of 13% to 17%.
- As of September 30, 2026, Ratel has approximately $65.1 million in backlog under previously signed government contracts.
- The revenue targets in the earnout agreement are $77 million for 2026, $130 million for 2027, and $187 million for 2028, with operating income targets of $8.47 million, $14.3 million, and $20.57 million respectively.
- Swarmer ended the quarter with approximately $37.3 million in cash and cash equivalents, up from $25.3 million at June 30.
Is It Cheap?
That depends entirely on which company you think you are buying. At roughly $8.77 per share, the market is pricing SWMR as a pre-revenue software shell. If Ratel closes this month as guided, the combined entity suddenly has a run rate approaching $150 million to $160 million in annualized revenue based on Ratel’s $35 million to $40 million Q4 outlook. At the current share price, that is a very different multiple than the standalone Swarmer multiple, which is essentially infinite. The earnout structure keeps the acquisition price manageable: the definitive agreement makes the majority of Ratel’s consideration contingent on earnouts tied to continued revenue and operating income growth. That is buyer-friendly structuring.
Bull / Base / Bear
Bull: Ratel hits its 2027 target of $130 million, Swarmer’s software creates genuine cross-selling into allied NATO buyers, and the market resets SWMR as a hardware-plus-software defense platform.
Base: Ratel delivers $110 to $120 million in 2027 revenue at thin margins. Swarmer trades at a modest multiple on hardware earnings, with software optionality unpriced.
Bear: Management acknowledged uncertainty around geopolitics and Ukraine’s future budgets, noting that all of Swarmer’s revenue to date and all of Ratel’s revenue are sourced from Ukraine. A ceasefire, a budget freeze, or a procurement pause would gut the revenue base immediately.
Action Plan
This is not a stock for a retiree’s core portfolio. It is a small, speculative, single-country defense bet with real technology and real near-term revenue that the market has not fully absorbed. If you want exposure, size it accordingly: a 1% to 2% position, entered in stages after the Ratel close is confirmed. Watch Q4 revenue against the $35 to $40 million guide as your first signal.
Cheap Investor Checklist
- Ratel Q4 2026 revenue: does it land in the $35M to $40M guided range?
- Operating margin: does Ratel hold the 13% to 17% band management projected?
- Contract backlog: does the $65.1M figure grow or shrink post-close?
- Geographic diversification: any non-Ukraine contracts signed within 90 days of close?
- Cash burn: does Swarmer’s standalone operating expense stay below $10M per quarter?
Bottom Line
If Ratel closes in November as guided and hits anywhere near its Q4 revenue target, SWMR transforms from a roughly $26,000-revenue software shell into a defense hardware company with a credible growth curve. If Ukraine procurement stalls, every target above becomes wishful thinking. Know which bet you are making before you buy.