Dear Reader,
Democrats have won both the House and the Senate.
That could make things a lot harder for President Trump.
Obviously, now comes the debate over what he can get done in the remainder of his term, and what it means for your money.
But before you make any changes to your investments, there’s something else worth thinking about.
What if the next big financial problem starts OUTSIDE Washington?
As you probably already know, companies are spending huge sums on AI data centers… counting on future revenue to justify the current expenditure.
But what happens if that revenue falls short?
The losses could hit not just AI stocks but also banks and retirement funds. And Washington could face pressure for another bailout.
Our new briefing explains all our concerns and also the steps you can take to prepare.
You’ll also find out how to get our reports on buying gold and silver in a crisis.
As Washington adjusts to the election results, take a moment to check how prepared your money is for what comes next.
Eliza Lasky
Weiss Advocate
Cloudflare Wants to Get Paid When AI Reads the Internet
Hey there, bargain hunter. Cloudflare just reported its best quarter ever, grew revenue 39% year over year to $782.5 million, and crossed $3 billion in annualized revenue. Non-GAAP operating income came in at $137.1 million, or 18% of revenue. The stock bounced 15% after hours following a bruising pre-earnings selloff. That is the scoreboard. Here is the more interesting question: is Cloudflare quietly building the most important toll road on the internet?
The Real Angle
Most NET coverage focuses on its CDN and security roots. The fresher story is what it is building on top of them. Cloudflare announced an update on July 1, 2026, that splits AI bot traffic into three distinct purposes: crawlers that build a searchable index, automated agents completing tasks in real time, and crawlers pulling content to train a model. That three-way classification is the foundation of a monetization stack most people are still underestimating.
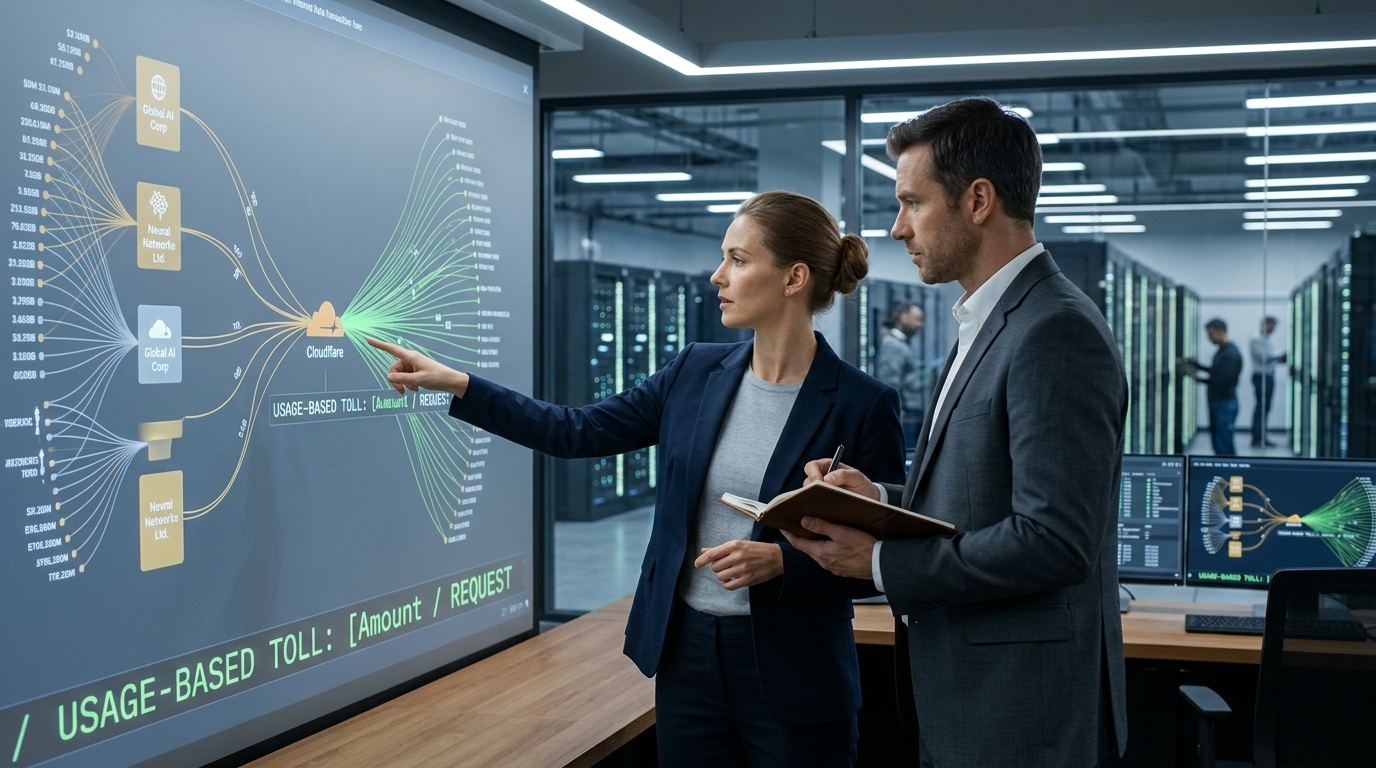
Around July 1, Cloudflare started pushing beyond charging per crawl toward experiments it calls Pay Per Use, where content owners get compensated when their content is used in AI answers, not merely fetched. The original Pay Per Crawl system let publishers set a price per fetch and return an HTTP 402 response to bots that would not pay. Cloudflare has said it is now sending more than two billion HTTP 402 “payment required” responses per day across its network, and that most of those do not end in payment.
The Business Case
Cloudflare has built out a monetization stack alongside the access controls: Monetization Gateway to help content providers charge for assets behind Cloudflare via x402, and Pay Per Crawl, which lets a publisher set a price for crawler access rather than a flat allow-or-deny rule.
Rather than reacting to AI disruption of its core CDN and security business, Cloudflare is positioning itself as the infrastructure layer that arbitrates the relationship between publishers and AI companies, a position with recurring revenue potential if Pay Per Crawl, Pay Per Use, and Monetization Gateway gain real adoption. On January 15, 2026, Cloudflare acquired Human Native, a UK-based AI data marketplace, bringing a training-data licensing team into the company that already controls crawler access for its customers.
The question of whether AI workloads are actually running at scale — not just contracted — is the same pressure Cloudflare’s monetization layer faces. Datadog’s consumption billing offers the most honest real-time signal of whether enterprise AI applications are generating the traffic Cloudflare’s toll booth depends on.
Is It Cheap?
Bluntly: no. As of the U.S. close on November 12, 2026, Cloudflare carried a market cap of about $114 billion. Depending on the data source and day, its EV/Revenue has been roughly in the low-40s recently, and EV/EBITDA is not a stable yardstick here because trailing EBITDA has been minimal or negative in many calculations. Full-year 2026 revenue guidance sits between $2.963 billion and $2.964 billion, implying approximately 37% growth. That is real growth. Paying around 40x revenue for it is a different conversation.
Bull / Base / Bear
- Bull: Pay Per Use achieves broad adoption. Cloudflare becomes a recurring cut on every AI content transaction across the web. Revenue trajectory sustains above 35%.
- Base: Monetization tools gain traction with large publishers only. Large publishers with strong content leverage negotiate direct deals or turn on metered access quickly, while smaller sites mostly use the free block-by-default protection without engaging the monetization layer for months. Growth stays in the 30-35% range.
- Bear: Trading at an elevated valuation, the stock is exceptionally vulnerable to multiple compression if growth decelerates even modestly.
Action Plan
NET at $315 is not a value stock by any metric a bargain hunter normally trusts. If you own it, the Q4 guidance of $845-846 million and a Q4 non-GAAP EPS outlook of $1.35 justify holding. If you are building a position, scale in on broad tech pullbacks rather than chasing. The pay-per-citation model needs 12-18 months to show real revenue contribution.
Cheap Investor Checklist
- Q4 revenue vs. guidance of $845-846M
- Pay Per Use partner count beyond Ceramic.ai and You.com
- Free cash flow margin trend (Q3 operating cash flow margin: 28%)
- Large customer count growth (5,006 at over $100K ARR, up 25% YoY)
- Current RPO growth (37% in Q3; watch for deceleration)
Bottom Line
If Cloudflare’s Pay Per Use model becomes the web’s default content licensing rail, a roughly $114 billion market cap could look conservative. If adoption stalls at large publishers and AI companies route around the toll booth, that multiple corrects hard. The business is genuinely exceptional. The price already knows it.