There’s a market signal that shows up around 9:35 AM that most traders completely overlook.
They’re watching RSI.
Moving averages.
Candlesticks.
Trying to figure out where the market is headed next.
Meanwhile, I’m watching what happens in the first few minutes after the opening bell.
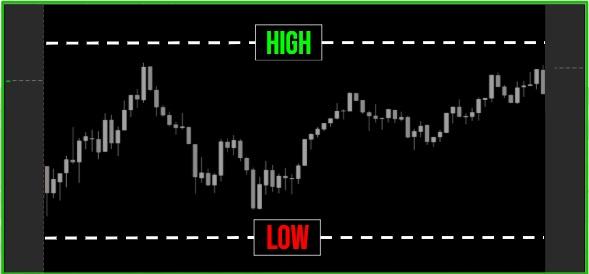
Because that’s where I’ve found a recurring pattern that can help identify key levels above and below the market.
I’ve spent years tracking this behavior.
And over the past two years, we’ve seen this approach produce 618 winning signals.
Now there’s a new test on the table.
Can we get to win #618 before the weekend?
I’ve set a challenge in motion to find out.
No trading guarantees, of course…
But I can show you the data behind the setup, the levels I’m watching, and exactly what I’m looking for as we make our run from #618 toward #620.
If you want to follow along the Challenge, I’ve laid everything out right here.
See you in the market,
Chris Pulver
Petrobras Pumped a Record. The Payout Came Up Short.
Hey there, bargain hunter. A fat dividend yield is the oldest trap in the value investor’s toolkit. Petrobras just sprung it again.
Scoreboard
Adjusted EBITDA rose 34% year-over-year to 85.82 billion reais, missing analyst expectations of 95.59 billion reais. Net profit came in at 39.75 billion reais, up 21.5% from a year earlier. Despite record production and stronger refining margins, Petrobras announced about $2.74 billion in payouts, below the roughly $3.8 billion analyst estimate. The real is trading near 5.58 to the dollar, its weakest level in over a year.
What Actually Happened
Average output in Q3 2026 reached 3.512 million barrels of oil equivalent per day, an 11.7% increase year on year. The result marked the third consecutive quarterly oil production record for the company in 2026. Brent crude averaged about $97 per barrel during the quarter, compared with approximately $69 a barrel a year earlier. So: record volumes, higher oil prices, and still a 10 billion reais EBITDA miss. The culprit is spending.
Quarterly capital expenditure rose almost 17% to $6.4 billion, lifting nine-month investment to $16.8 billion, up 20.2% year-on-year. Petrobras now expects total investment outlays of $24 billion to $25.5 billion, compared with $19.4 billion previously earmarked. That is a $4 billion-plus upward revision to spending in a single quarter. Capex is cash out the door before shareholders see a cent.
The Business
Petrobras is Brazil’s state-controlled integrated oil giant, dominating upstream production in the pre-salt deepwater fields and supplying the bulk of the country’s refined fuels. Total refined product production amounted to 1.873 million barrels per day, reinforcing Petrobras’ position as Brazil’s dominant domestic fuel producer. The government owns a majority stake, which means every capex plan, every dividend, and every five-year strategy carries political weight alongside financial logic.
Key Metrics
- Revenue rose 32.4% year-on-year to 169.35 billion reais.
- Adjusted EBITDA: 85.82 billion reais vs. 95.59 billion consensus. Miss: roughly 10 billion reais.
- Operating cash flow: $12.026 billion. Free cash flow: $6.618 billion.
- Net debt ended the quarter at $57.8 billion, down 4.2% from the previous quarter.
- Payout: about $2.74 billion vs. $3.8 billion expected. Miss: roughly $1.1 billion.
- Full-year 2026 oil and gas output guidance lifted to 3.3 to 3.4 million barrels of oil equivalent per day, up from 3.1 million previously.
Is It Cheap?
PBR trades at a P/E ratio of roughly 5.3. On that basis alone, Petrobras looks like a steal. But a low multiple on a state-controlled producer with accelerating capex and a currency sliding toward 5.60 per dollar is not automatically a bargain. The P/E is cheap; the risk-adjusted yield is a different question.
Petrobras offers a dividend yield of about 6% to 7% based on trailing payouts. The coverage looks solid until you remember that the distributable cash pool shrinks every time the capex budget expands.
Oil price is the single variable that can rescue or wreck the Petrobras yield thesis from here. Brent crossing $100 created two distinct trades, and the distinction between owning the front-month move versus the long-dated curve matters enormously for income investors.
Bull / Base / Bear
Bull: The updated five-year plan, expected on November 28, should detail spending priorities and shareholder returns as Petrobras pursues offshore production and invests in refining, biofuels, and fertilizers. If the new plan raises the production ceiling without adding proportional debt, the yield resets higher on a bigger earnings base.
Base: Capex stays elevated through 2027, free cash flow covers the minimum dividend, and PBR trades in its accustomed 5x to 6x earnings range. Total return depends almost entirely on oil prices and the real.
Bear: The company must fund a heavier investment program while earnings continue to trail expectations. If spending climbs and results keep disappointing, raised guidance shifts from a support to a burden. A weaker real amplifies the dollar cost of imported inputs without lifting reais-denominated payouts proportionally.
Action Plan
Wait for the five-year business plan before adding. The updated plan, expected on November 28, should detail spending priorities and shareholder returns. If capex guidance moderates and free cash flow per share rises, that is your entry signal. Scale in at two-thirds of a full position now only if Brent holds above $90 and the real stabilizes below 5.60. Reserve the final third for post-plan clarity.
Cheap Investor Scorecard
- EBITDA vs. consensus: MISS (85.82 vs. 95.59 billion reais)
- Payout vs. estimate: MISS (about $2.74bn vs. $3.8bn expected)
- Production growth: PASS (record Q3, +11.7% year-on-year)
- Net debt trend: PASS (down 4.2% quarter-on-quarter)
- Capex discipline: FAIL (guidance up $4+ billion in one quarter)
- Currency risk: FLAG (real near 5.58 per dollar, 15-month low)
- Valuation vs. peers: PASS (P/E ~5x to 6x vs. major integrated multiples in the teens)
- Five-year plan clarity: PENDING (due November 28)
Bottom Line
If the upcoming five-year plan reins in spending and shows a credible path to higher free cash flow per share, Petrobras earns a larger position. If capex keeps climbing and payouts keep disappointing, that yield is a number on a screen, not cash in your account. The barrel record is real. The distribution question is not yet answered.
The same Brent environment that inflated Petrobras’s revenue line is running through every integrated energy name right now. Marathon Petroleum posted a blowout refining quarter and immediately raised the question of whether the conditions that produced it are already over.