Everything hinges on 8:30 ET this morning. The Bureau of Labor Statistics releases the October nonfarm payrolls report Friday morning, and the range of estimates sitting on traders’ desks is wide enough that any surprise in either direction rewrites today’s playbook from scratch.
Where Bonds and Rates Stood Heading In
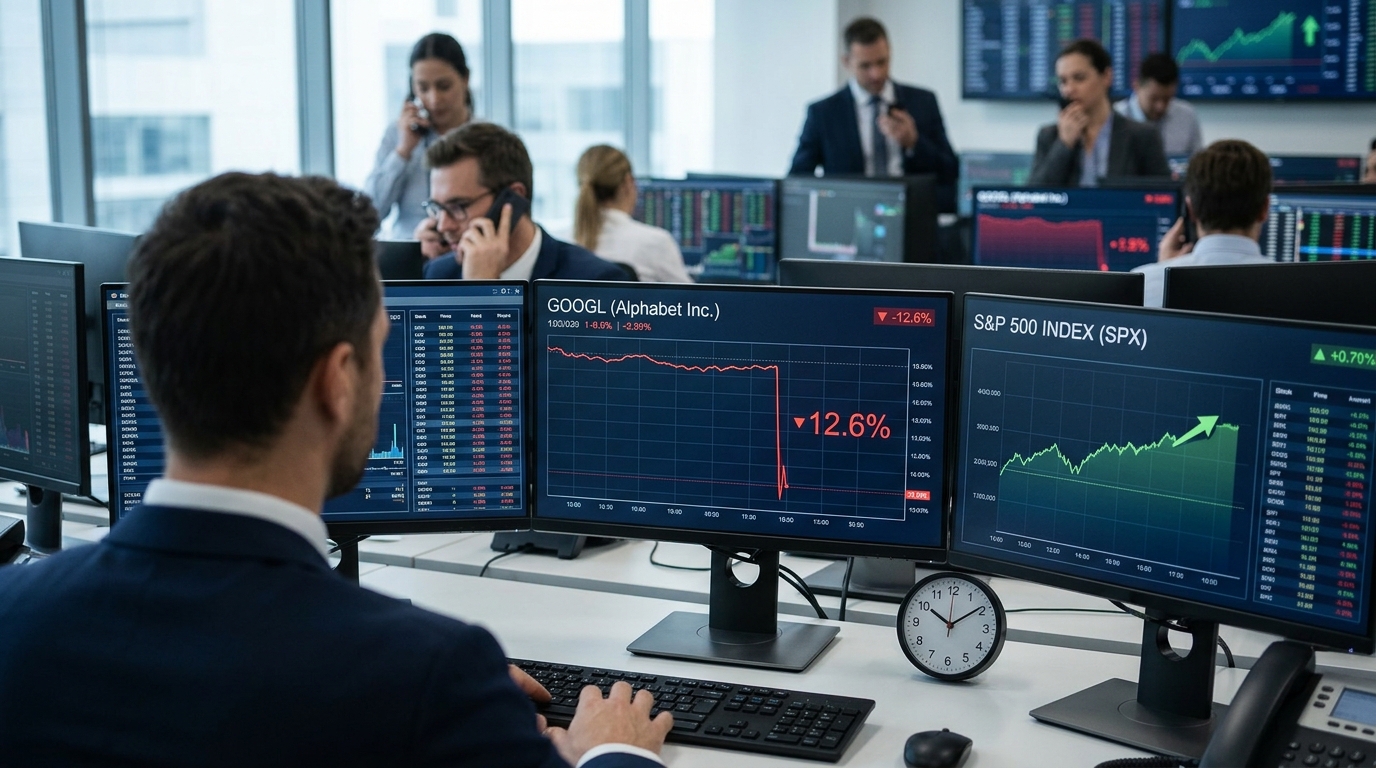
Thursday’s equity selloff did real work in the rates market. The two-year Treasury yield fell 12 basis points to 4.46% and the ten-year dropped 6 basis points to 4.84%, its lowest close since September 9, widening 2s10s to 38 basis points.
December hike pricing also backed off meaningfully Thursday. CME FedWatch showed markets leaning toward a hike for the December meeting late on November 5, but with a materially lower probability than the prior day.
That single-day collapse in December hike odds is the context every trader needs before interpreting whatever hits at 8:30. The bond market already did a lot of work for the bulls. The question is whether payrolls confirm or erase it.
The Consensus and Its Gaps
Forecasters predict the United States added 65,000 jobs in October, an uptick from September’s surprisingly sluggish growth, according to FactSet. The dispersion across shops is unusually large: RSM anticipates a net gain of 95,000 jobs, while Vanguard expects 120,000, well above consensus. KPMG sits at 45,000, below the floor of most published ranges.
Average hourly earnings are forecast to have increased 0.3% in October after edging up 0.1% in September. That wage number matters as much as the headline count. Softening wages remove one of the Fed’s key justifications for a December move.
The Three-Way Branch at 8:30
A print in the neighborhood of consensus keeps December odds near current levels and probably allows the 10-year to hold near current levels. That is the cleanest path for equities to stabilize after Thursday’s tech-led destruction.
A print above 90,000 is a different animal. It directly challenges the bond rally of the past 48 hours. The 2-year at 4.46% looks stretched if labor demand is re-accelerating. December hike odds would likely recover, the DXY would catch a bid from its current 101.80 area, and the technology multiples that just entered correction territory face renewed pressure.
A sub-45,000 print opens the other door. December hold odds would surge, the 2-year could break below 4.40%, and the DXY likely gives back its overnight recovery. The problem is that a particularly weak jobs report can also trigger concerns about an impending recession, which is not straightforwardly bullish for anything except defensive sectors and Treasuries.
Sector Rotation Implications
Defensive leadership has been a clear theme around the tape: health care and consumer staples have been among the areas holding up best as traders have looked for shelter, and the broader market tone has reflected rising sensitivity to rates.
Monthly jobs growth has averaged about 45,000 per month over the last year, based on the BLS September report. That framing is important: a consensus print does not kill December, it merely leaves the probability table where it sat Thursday evening.
Trader’s Action Plan
Watch the 2-year yield and December FedWatch odds simultaneously at 8:30. Those two data points will tell you faster than any commentary which scenario has arrived. The DXY near 101.80 is the secondary confirmation: a dollar that cannot rally on a strong number signals that safe-haven demand from equities is overwhelming the rate impulse, and defensives stay in charge. A dollar that breaks above 102.20 on strong payrolls means rates are back in the driver’s seat and cyclical leadership reasserts.
The bond market has already priced a lot of good news. The burden of proof this morning sits with the bulls.