October 31, 2026
Bonus Content: McDonald’s $5 Meal Is Everywhere. Sales Tell a Different Story.
Editor’s Note: Jeff Brown is the former tech executive who identified Nvidia in 2016, before its 37,800% appreciation. He is now tracking an AI infrastructure company at a comparable stage of development — one he describes as his single highest-conviction position. See the full analysis here or read more below.
Dear Reader,
If I were concentrating into a single AI infrastructure position at current valuations…
This under-covered company has already secured multi-billion dollar contracts with OpenAI, the creator of ChatGPT…
Amazon… Microsoft… IBM… and AMD… among others.
Demand for its patented technology has pushed its order book to capacity through 2027.
The business is scaling at a rapid pace.
Wall Street consensus projects revenue to triple in 2027 alone.
It is among the fastest-growing companies in the AI infrastructure sector…
And it sits at roughly the same market capitalisation Nvidia held in 2016…
Before Nvidia’s 37,800% appreciation over the following years.
A $5,000 position in Nvidia at that stage would have reached $1,895,000 at the peak.
Past performance does not determine future results, but the structural parallel is worth examining closely.
We have so much to look forward to,
Jeff Brown,
Founder & CEO, Brownstone Research
P.S. This is also the infrastructure position two of Elon Musk’s most recent ventures appear to be accelerating.
Why?
Because two recent moves by Elon Musk point directly toward accelerating demand for this company’s patented technology…
And ahead of the executive team’s upcoming announcement, the entry window at current valuations may be narrow.
Read the full briefing to see why this position stands apart.
McDonald’s $5 Meal Is Everywhere. Sales Tell a Different Story.
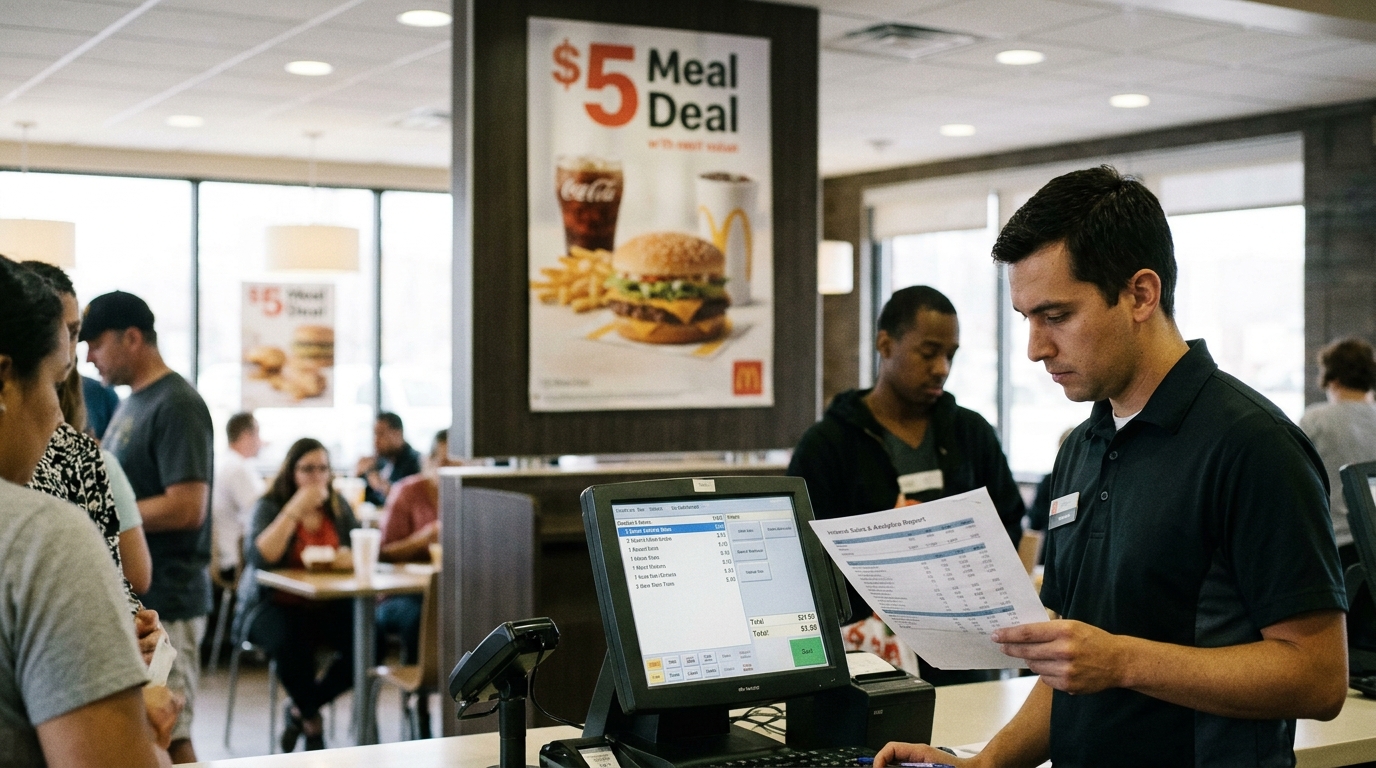
Hey there, bargain hunter. McDonald’s has been telling you it is your best friend in a tough economy: $5 meal deals, $4 breakfast combos, $3 items on a revamped McValue board. That is a lot of marketing. Wednesday’s Q3 report, expected before the open on November 4, will tell you whether any of it is showing up where it matters: guest counts.
Scoreboard
Consensus EPS: $3.38, up 5.0% from $3.22 a year ago. Revenue consensus: $7.29 billion, implying 3.0% growth year over year. Analysts have trimmed their EPS forecast by roughly 1.5% over the past 90 days, which signals measured caution rather than outright pessimism. The stock closed at $258.12 on October 30, down roughly 12% year-to-date and sitting at a trailing P/E near 21, well below its five-year average.
What Actually Happened Last Quarter
Q2 told a story the arches would rather not repeat. U.S. comparable sales grew just 0.8%. Global comps came in at 1.3%. Management said U.S. comps were slightly negative in July. That is the number to beat on Wednesday.
It was not a profit collapse. Adjusted EPS of $3.38 beat the $3.32 consensus. But higher checks masked lower guest counts. Fewer people walked through the door; they just spent a bit more per visit.
The Real Test: Value Menus vs. Real Traffic
Here is where the bargain-hunter lens matters. McDonald’s has had a $5 meal deal since June 2024, and it has been extended multiple times. The McValue platform launched in April 2026 with a new Under $3 Menu and a $4 Breakfast Meal Deal alongside meal deals at lunch and dinner. The deal itself is real.
The problem: real traffic has not responded. Third-party visit data points to continued decline even as comparable sales crept positive on check size alone. Chipotle’s Q3, reported this week, offered a warning. Restaurant-level margin fell 120 basis points to 23.3% as the chain leaned into promotions to reconnect with customers after demand slowed in mid-July. That is the cost of buying traffic. McDonald’s, which operates on thinner company-owned margins already, cannot afford the same trade-off at scale.
The Business in Plain English
McDonald’s earns money three ways: royalties and rent from its franchise base, fees tied to systemwide sales in certain markets, and margins at the smaller slice of company-operated stores. The franchise model means labor and food-cost inflation largely pass to franchisees, but value menu pressure does hit franchisee profitability, which eventually circles back to McDonald’s in the form of operator tension and slower unit growth. The global target of 50,000 restaurants has already slipped from 2027 to 2028.
Data Section
- Q3 consensus EPS: $3.38 | Revenue: $7.29B
- Q2 U.S. comps: +0.8% (global: +1.3%)
- Full-year 2026 EPS consensus: ~$12.84
- YTD adjusted operating margin: 46.9%
- Loyalty: nearly 220 million 90-day active users, loyalty sales up 20% to $40B trailing
- Dividend yield: approximately 2.99% at current price
- Debt load: about $54.6B total debt vs. $822M cash
Is It Cheap?
At around 21x trailing earnings, MCD trades below its recent history on that metric. The forward P/E sits around 17-19x depending on the source, modestly above the restaurant industry median. Yum Brands trades at roughly 24x normalized earnings; Chipotle at 28x, even after this year’s pain. On a pure multiple basis, McDonald’s is the cheapest it has been in years. The catch: cheap multiples require the earnings to keep growing. A second consecutive quarter of negative U.S. traffic would put that assumption under pressure.
The confidence backdrop matters beyond fast food. Packaged-food companies absorbing the same 81.9 Conference Board reading show how broadly the low-income consumer squeeze is hitting earnings models.
Bull / Base / Bear
Bull: U.S. comps recover to 1.5%-plus in Q3 as value marketing penetrates lower-income households squeezed by a Conference Board confidence reading of 81.9 in September. Loyalty drives incremental frequency; international accelerates. Stock re-rates toward 23x.
Base: U.S. comps print near flat to +0.5%, EPS meets the $3.38 consensus on margin discipline. Stock trades sideways; no catalyst for re-rating until Q4 shows sequential improvement.
Bear: U.S. comps go negative again, franchisees push back on value pricing, and expectations for full-year 2026 get trimmed. The stock, already down about 12% on the year, tests fresh lows.
Action Plan
This is a hold ahead of the number, not a chase. If U.S. comps print above 1% and management confirms the $5 meal deal drove actual guest count growth (not just check-size noise), that is a legitimate entry point for a scale-in over two to three weeks. Start with a half position at current prices if the valuation discount to history is your primary thesis. Add the second half only on confirmed traffic recovery, not on an EPS beat alone. MCD has beaten EPS five of the last eight quarters while the stock has drifted lower each time the revenue line disappointed.
Cheap Investor Checklist
- U.S. Q3 comps: need to see above +1.0% for the value menu to have a credible traffic argument
- Guest count direction: positive transactions, not just check-size inflation
- Franchised margin dollars: watch for any compression that signals value pricing is biting the model
- Full-year EPS expectations: any downward revision to the ~$12.84 consensus is a red flag
- Loyalty active users: nearly 220M is the Q2 baseline; growth here underpins digital pricing power
- McValue consumer awareness: management called out low awareness in Q2 as a key execution miss
- International comps: IOM and IDL were expected to accelerate sequentially; confirm they did
- Unit growth update: any further delay to the 50,000 restaurant target signals franchisee hesitation
Bottom Line
If U.S. comps rebound above 1% and management can show guest counts, not just check size, turned positive, MCD at roughly 21x earnings with a 3% dividend is genuinely interesting for value-oriented accounts. If traffic stayed negative into September, the cheap multiple is a value trap, not a bargain. Wednesday morning will tell you which one this is.