October 15, 2026
Bonus Content: Albertsons Pulled Guidance. The Kroger Lawsuit May Be Bigger Than the Stores.
If you still haven’t downloaded my “Top 10 Stocks to Buy This Quarter” report…
…please take a few seconds and download it right now while this quarter’s edition is still up.
Every quarter we replace the list with a brand-new one. Once the new edition goes up, this one comes down.
So do yourself a favor and save a copy to your computer now. That way, you’ll have it no matter what.
Make sense?
FREE: Top 10 Stocks to Buy This Quarter << Download Now
Good Trading,
Bill Poulos
p.s. Go here to save a copy of my “Top 10 Stocks to Buy This Quarter” report before we swap in the next edition.
Albertsons Pulled Guidance. The Kroger Lawsuit May Be Bigger Than the Stores.
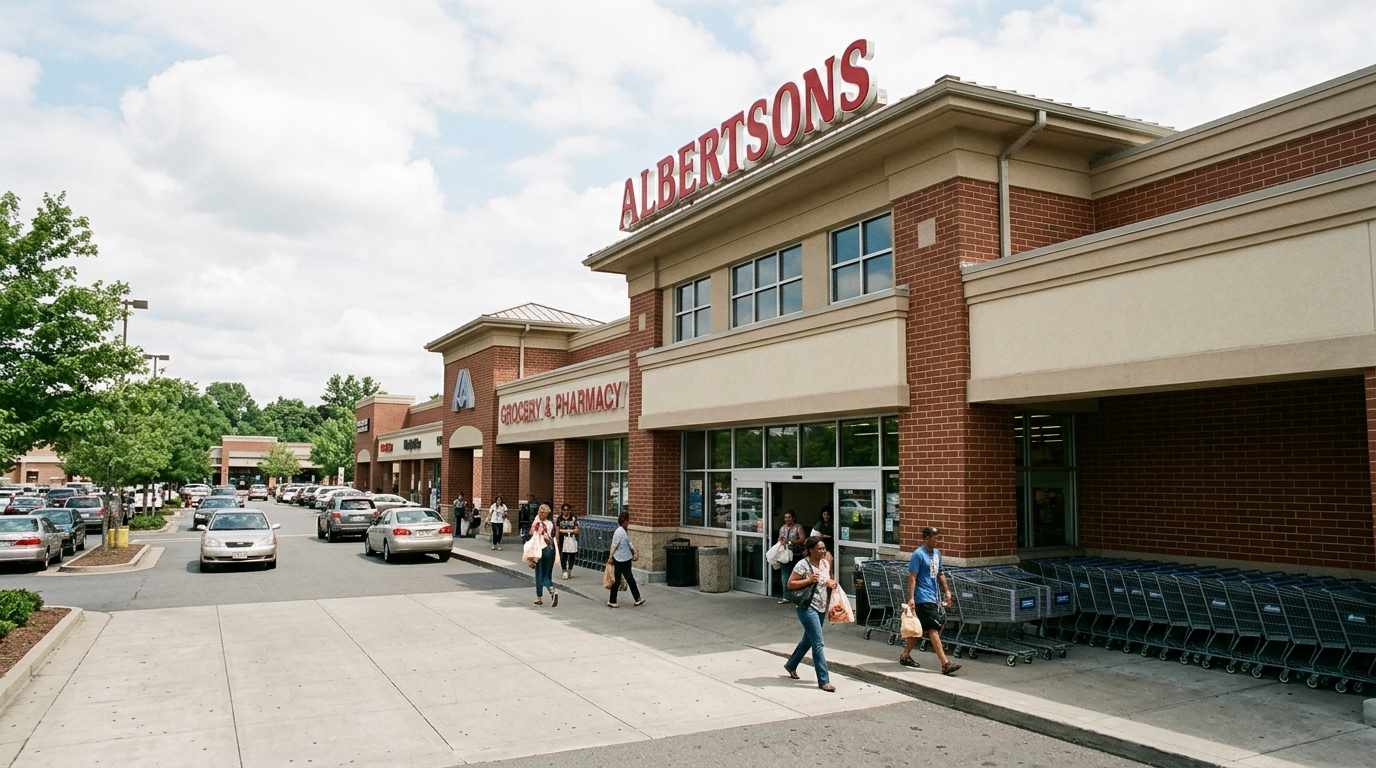
Hey there, bargain hunter. Albertsons just handed you one of the stranger valuation puzzles in consumer staples right now: a broken grocery business trading below book value, with an $8-billion-plus lawsuit sitting in court that could be worth more than the entire company’s market cap.
Scoreboard
Revenue for the quarter ended September 12 slid 0.1% to $18.89 billion, and adjusted net income fell about 28% to $179 million. Identical-store sales were down 0.8%. Adjusted EPS of $0.36 beat the $0.33 consensus, but adjusted EBITDA fell to $784 million from $848 million a year earlier. Net income dropped 69% to $51.5 million. Then management pulled the full-year outlook entirely.
What Actually Happened
The retailer announced a comprehensive business review aimed at improving operating performance, reducing costs and reassessing its business structure, with CEO Susan Morris saying the review is intended to accelerate improvements and address a cost base that management considers unsustainable.
Albertsons has withdrawn its financial guidance for the full year and plans to present a revised outlook when it reports its fiscal 2026 fourth-quarter results. That means no forward visibility until fiscal Q4 results land. Gross margin slipped to 26.8% from 27.0%, driven by higher delivery and handling costs from digital sales growth and elevated shrink.
What the Market Is Really Saying
ACI closed at $12.94 on October 14, against a 52-week high of $20.00. Enterprise value sits at roughly $21.98 billion. The consensus price target is $14.19, but after the guidance withdrawal, several analysts have trimmed targets into the $10 to $13 range, citing execution risks during restructuring and leadership changes.
The real question is what the lawsuit is worth. Albertsons is seeking approximately $8 billion from Kroger in the Delaware Court of Chancery, a sum that includes a $600 million termination fee plus compensation for shareholder losses suffered because the deal fell through. Trial is scheduled to begin October 19, 2026. The largest slice of the claim is also the shakiest: subtract the $600 million fee and roughly $75 million in interest and costs, and the rest is lost shareholder premium. Delaware courts have questioned whether a target can collect premium that flows to stockholders rather than the company itself.
Cerberus Capital Management holds the largest position at about 151.82 million shares, roughly 30% of shares outstanding based on recent filings. Kroger has argued that Albertsons’ multi-billion-dollar lawsuit is an attempt by its investors to extract money from the grocer. With Cerberus owning around a third of ACI, that framing matters at trial.
Is It Cheap?
As of September 12, Albertsons operated 2,240 stores, including 1,709 pharmacies and 408 fuel centers. That is a real asset base. At $13 per share the grocery business alone trades at roughly 0.08x trailing sales, which is distressed. The lawsuit adds a wildcard: even a partial win, say the $600 million termination fee, moves the math quickly on a market cap in the mid-$5 billions.
Kroger rejects the full claim, arguing it acted in good faith and that the FTC’s objections required divestitures beyond the agreed 650-store limit. Probability-weighting the outcome is genuinely hard. Assign 50% odds to collecting the base fee alone and you add roughly $0.55 per share in expected value. Assign meaningful odds to a larger recovery and ACI starts to look like a stub equity with a lottery ticket attached.
Bull / Base / Bear
- Bull: Delaware court awards the full $600 million termination fee plus a fraction of premium damages. Business review produces real cost cuts and identical-sales stabilize. Stock recovers toward $17 to $18.
- Base: Court awards the fee only. Business review takes 18 months to show traction. Shares trade sideways in the $12 to $14 range pending Q4 guidance restoration.
- Bear: Kroger wins outright. Albertsons’ own conduct during divestiture negotiations is used against it in court. Operating losses deepen as restructuring costs rise. Shares retest the 52-week low near $10.86.
Action Plan
This is a two-asset situation: broken grocer plus litigation option. Do not buy it as a grocery recovery alone at this margin profile. If you want exposure, size it as you would a distressed special situation, small, with hard stops. A scale-in at $11.50 and again near $13 makes sense for risk-tolerant accounts only. Hold through the trial verdict before adding more.
Cheap Investor Checklist
- Identical-store sales: watch for return to positive in Q3
- Adjusted EBITDA margin: needs to stabilize above 4% to support the enterprise value
- Delaware trial verdict: expected within weeks of the October 19 start
- Business review scope: banner divestitures or real estate sales would crystallize hidden value
- Guidance reinstatement: management committed to a fiscal Q4 update; any delay is a red flag
- Cerberus exit risk: largest shareholder has held for about two decades; watch for block sales
- Gross margin trend: currently 26.8%, needs to recover toward 27.5% to matter
Bottom Line
If the Delaware court awards Albertsons even the contractual $600 million termination fee, that alone is roughly 11% of the current market cap landing in cash. If the grocery business stabilizes and the review produces credible cost cuts, the stock has a reasonable path back to $16 to $17. If Kroger wins cleanly and the operating business keeps losing volume, this is a value trap near $11. Watch the trial first. Then decide how much of the lawsuit you are willing to pay for.