October 9, 2026
Pacira just got taken out at $1.65bn. The stock was right there the whole time.
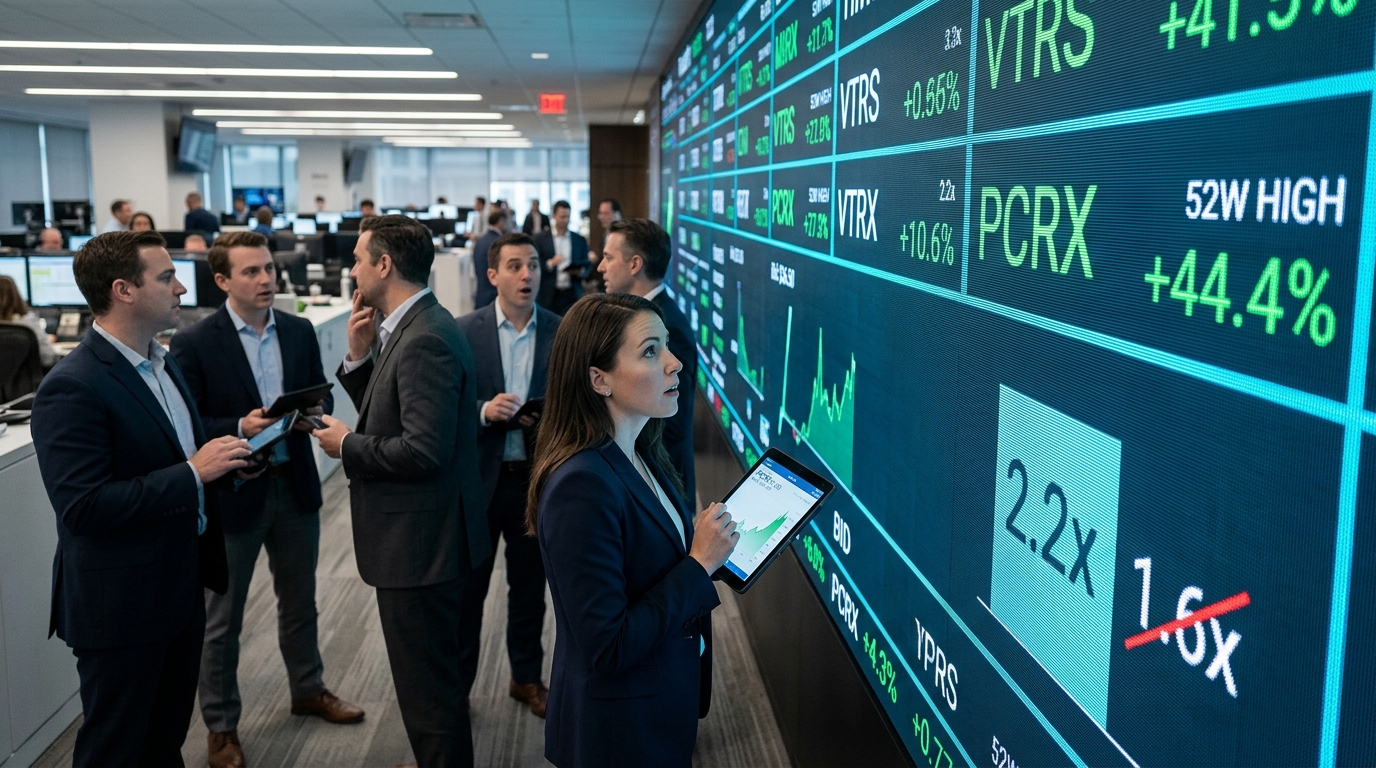
Hey there, bargain hunter. On Thursday, Viatris agreed to acquire Pacira BioSciences for $36.50 per share in an all-cash deal valuing the equity at $1.65 billion. PCRX closed October 8 up 44.4% at $36.39, right at a 52-week high; the 52-week range was $18.80 to $36.46. The market had nine months to get there on its own.
3X Over Lunch? (True Story)
I bought a tech stock back in 1998 for $5.
It nearly 10X’d to $45 in two years.
Then… one day I stepped out for lunch.
When I came back, the stock was at $135…
All said… a 2,600% gain.
I made a quarter of a million dollars in that single afternoon.
Right now, the same setup is forming again.
Scoreboard
The 45% premium to Pacira’s prior close of $25.20 is the headline. The real number is the multiple. Based on the announced $1.65 billion equity value, Viatris is paying roughly 2.2x trailing twelve-month revenue of about $746 million and about 9.3x trailing adjusted EBITDA of about $177 million. Before this deal, the stock traded at 1.6x that same revenue base.
The Real Reason
Pacira spent years in the penalty box. Revenue grew from $675 million in 2023 to $726.4 million in 2025, a 3-4% annual pace that kept the market bored. Gross margins were exceptional, with record 79.4% GAAP gross margin in 2025, and the NOPAIN Act had delivered a genuine reimbursement catalyst. From January 1, 2025, through December 31, 2027, Medicare provides temporary additional payments for qualifying non-opioid treatments for pain relief in hospital outpatient department and ambulatory surgical center settings. The market priced none of that in. Viatris noticed.
“The World’s Best Gold Mine Combined with up to 10% Yields”
Fed Chair Kevin Warsh just raised rates…
The irony: higher rates aren’t stopping inflation.
The biggest winner from this inflation: Very specific gold securities.
For example, the world’s best gold mine is yielding up to 10%.
That’s real income that can help any investor protect their wealth from inflation…
Caveat:
The longer you wait to own this security, the more you’ll get crushed by inflation.
Deep Dive
Pacira’s engine is Exparel, a liposomal bupivacaine injectable for postsurgical pain. Full-year 2025 Exparel net sales were $575 million with 6.2% volume growth. Zilretta, the osteoarthritis knee injectable, added $116.6 million. By Q1 2026, Zilretta was up 15% year-over-year. TTM revenue through June 30, 2026 reached about $746 million, up about 6%.
Is It Cheap?
At roughly 2.2x TTM revenue and roughly 2.7x Exparel’s FY2026 guidance midpoint of $610 million in net sales, Viatris is paying a clear premium to where the stock lived, but not an aggressive one for a business with high gross margins and patent protection.
Bull / Base / Bear
Bull: NOPAIN Act adoption in ambulatory surgery centers accelerates Exparel volume beyond the recent 5-6% pace; Zilretta Phase 3 shoulder data expected later in 2026 opens a new indication. Base: Deal closes by year-end at $36.50; no competing bid given the unanimously approved boards and $62 million break fee. Bear: Regulatory delay, or Congress lets the NOPAIN Act sunset after December 31, 2027 without renewal.
7 AI Stocks to Invest in Today
AI is fueling the Fourth Industrial Revolution – and these 7 stocks are front and center. One of them makes $40K accelerator chips with a full-stack platform that all but guarantees wide adoption. Another powers the . From core infrastructure to automation leaders, these companies and other leaders are all in 7 AI Stocks to Invest in Today.
Action Plan
The arb spread is microscopic: PCRX closed at $36.39 against a $36.50 offer, leaving roughly 30 basis points. Tender if you own it. The more useful question is whether Viatris just published a price guide for other small-cap, high-margin pain names still trading at steep discounts to franchise value.
Cheap Investor Checklist
- TTM revenue: ~$746M, +~6% year-over-year
- Adjusted EBITDA: ~$177M (TTM ended June 30, 2026, per deal announcement materials)
- GAAP gross margin: record 79.4% in FY2025
- Exparel FY2026 guidance: $600-620M net sales
- Equity value/Revenue: ~2.2x; equity value/Adjusted EBITDA: ~9.3x
- NOPAIN Act reimbursement window: through December 31, 2027
- Break fee: $62M
- Expected close: end of 2026
Bottom Line
A profitable, patent-protected business with 79% gross margins and a Medicare reimbursement tailwind spent most of 2026 at 1.6x revenue. Viatris is paying $1.65 billion to correct that. The lesson is not in the 44% pop. It is in the gap that made the pop necessary.