October 9, 2026
Bonus Content: Wolfspeed Got $1.5 Billion From the Government. It Will Cost You 7.5%.
Hi Friend,
Just wanted to let you know you can now get a free copy of my new strategy guide here:
How to Master the Retirement Trade [PDF]

What’s the Retirement Trade?
It’s a simple trading opportunity that appears almost every trading day, between 9:30 and 10:45 am EST where traders are making between $300-$1,100+ per contract.
One of my favorite parts about this trade is how predictable it is. It occurs about 3-5 times each week. And once you know what you’re looking for, and how to enter/exit the trade, this could become another nice stream of income for you.
I’m not sure how long I’ll leave this guide up for. So do yourself a favor and take 5 seconds to download it now. At least you’ll have a copy stored for future use!
>> Click Here to Download Your FREE Strategy Guide Now.
To your success,
Dave Aquino
Partner, Head of Options Trading
Base Camp Trading
IMPORTANT NOTICE! No representation is being made that the use of this strategy or any system or trading methodology will generate profits. Past performance is not necessarily indicative of future results. There is substantial risk of loss associated with trading securities and options on equities. Only risk capital should be used to trade. Trading securities is not suitable for everyone. Disclaimer: Futures, Options, and Currency trading all have large potential rewards, but they also have large potential risk. You must be aware of the risks and be willing to accept them in order to invest in these markets. Don’t trade with money you can’t afford to lose. This website is neither a solicitation nor an offer to Buy/Sell futures, options, or currencies. No representation is being made that any account will or is likely to achieve profits or losses similar to those discussed on this web site. The past performance of any trading system or methodology is not necessarily indicative of future results.
CFTC RULE 4.41 – HYPOTHETICAL OR SIMULATED PERFORMANCE RESULTS HAVE CERTAIN LIMITATIONS. UNLIKE AN ACTUAL PERFORMANCE RECORD, SIMULATED RESULTS DO NOT REPRESENT ACTUAL TRADING. ALSO, SINCE THE TRADES HAVE NOT BEEN EXECUTED, THE RESULTS MAY HAVE UNDER-OR-OVER COMPENSATED FOR THE IMPACT, IF ANY, OF CERTAIN MARKET FACTORS, SUCH AS LACK OF LIQUIDITY. SIMULATED TRADING PROGRAMS IN GENERAL ARE ALSO SUBJECT TO THE FACT THAT THEY ARE DESIGNED WITH THE BENEFIT OF HINDSIGHT. NO REPRESENTATION IS BEING MADE THAT ANY ACCOUNT WILL OR IS LIKELY TO ACHIEVE PROFIT OR LOSSES SIMILAR TO THOSE SHOWN.
Wolfspeed Got $1.5 Billion From the Government. It Will Cost You 7.5%.
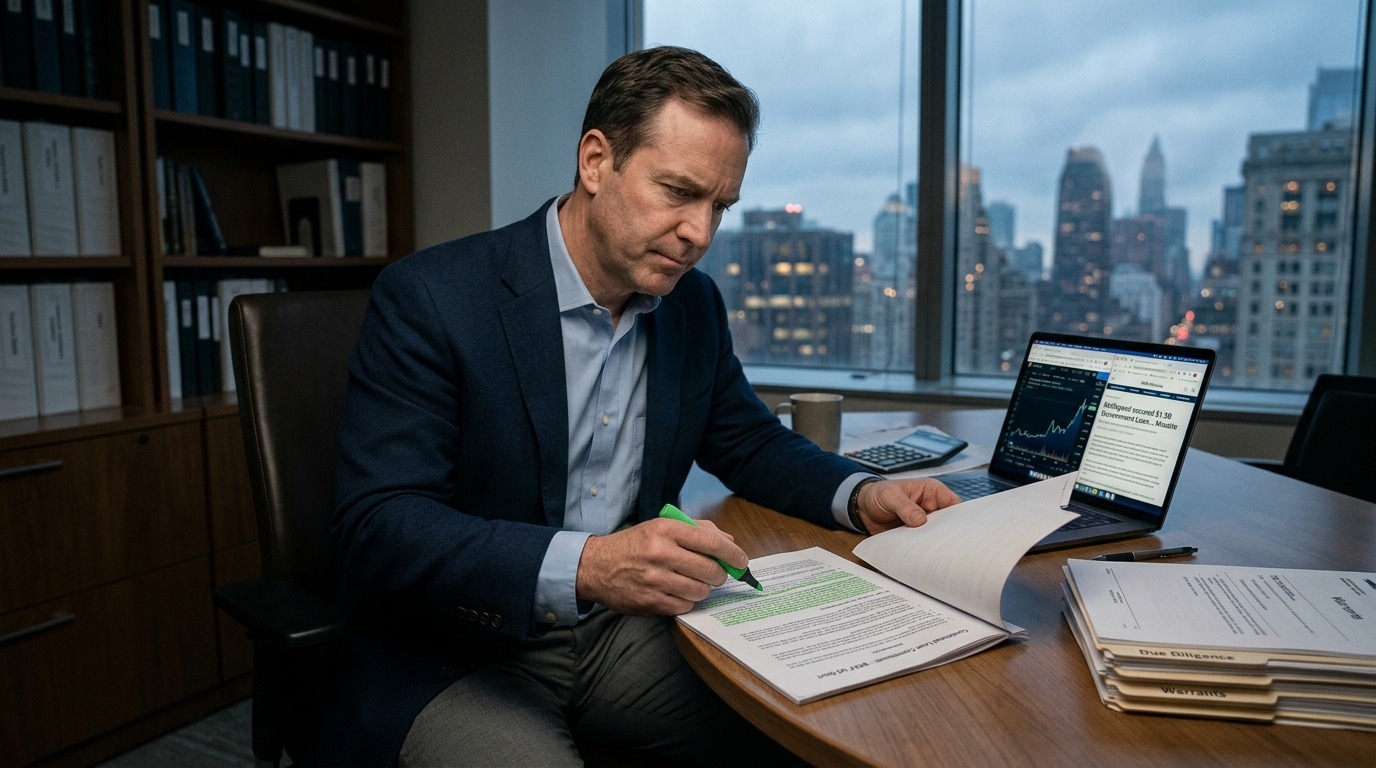
Hey there, bargain hunter. Wolfspeed surged roughly 27% in after-hours trading Wednesday and was still up double digits Thursday morning after announcing a conditional 30-year loan commitment of up to $1.5 billion from the U.S. Department of War. Before you chase that move, read the fine print.
Scoreboard
WOLF closed at $31.37 on October 7 before the announcement. After-hours it jumped nearly 20% toward $37.60, and by Thursday morning shares were trading around $33. The market cap sits near $1.6 billion at current prices. The loan itself is structured as a senior secured delayed-draw term loan in up to four tranches: a $600 million initial draw and up to $900 million in subsequent tranches of $200 million to $400 million each.
What Actually Happened
The Department of War’s Office of Strategic Capital sent Wolfspeed a conditional commitment letter. Conditional is doing a lot of work in that sentence. The deal still requires due diligence, negotiation of definitive agreements, government authorizations and approvals, appropriations, and sign-off from existing lenders. None of that is guaranteed. The money does not exist on the balance sheet today.
The price of admission: Wolfspeed must issue the government warrants to purchase up to 7.5% of its fully diluted equity, with warrants granted in tranches as each draw is funded. The company also has to contribute at least $750 million from qualifying sources and use commercially reasonable efforts to equitize a substantial majority of its convertible notes before the first dollar arrives.
The Business and What It Makes
Wolfspeed makes silicon carbide materials and power semiconductor devices. SiC chips handle high-voltage, high-temperature environments more efficiently than traditional silicon, which makes them useful in electric vehicles, solar inverters, industrial power systems, and defense electronics. The DoW says the financing is aimed at advancing the domestic wide bandgap supply chain with an additional focus on U.S. national security applications.
The Numbers That Matter
- Free cash flow burn: about $454 million in the year ended June 28, 2026
- Cash on hand: $1.1 billion in cash, equivalents and short-term investments as of June 28, 2026
- Revenue (Q4 FY2026): approximately $150 million, down roughly 24% year over year
- Gross margin (Q4): negative 25% GAAP, negative 20% non-GAAP
- Operating cash flow (Q4): negative $54 million
- Shares outstanding: 52,995,396 as of August 13, 2026, with convertibles and warrants adding to the fully diluted count
At 7.5% of fully diluted equity, the government warrants represent meaningful ownership. The fully diluted share count, once you layer in convertible notes and other existing warrants disclosed in SEC filings, runs well above the basic share count. Existing holders absorb that dilution progressively as each tranche funds.
Is It Cheap?
At $33 per share and a market cap near $1.6 billion, you are paying roughly 3.5 times trailing revenue for a company with negative gross margins and no path to profitability that is visible on the current cost structure. The average analyst price target sits around $27.50 to $30. That is not a ringing endorsement of buying the pop.
The loan is cheap money. Thirty years at government rates is genuinely advantageous financing, and at roughly $450 million of annual free cash flow burn, $1.5 billion buys real time. But the loan is also senior secured, which means if things go wrong, the government is first in line. Existing equity holders are last.
Bull / Base / Bear
Bull: The loan closes in full, Wolfspeed uses the capital to scale its Mohawk Valley fab and North Carolina SiC production, defense offtake contracts arrive, and the company reaches positive gross margins by fiscal 2028. The 7.5% warrant dilution is a rounding error against the upside if SiC becomes the dominant power semiconductor for EVs and defense.
Base: The loan partially closes after 12 to 18 months of conditions being satisfied, Wolfspeed raises the required $750 million in qualifying contributions (diluting holders further if that comes largely from equity), and the business stabilizes at sub-scale revenue while it waits for EV demand to recover. Shares drift back toward $25 as the initial euphoria fades.
Bear: Conditions are not met, the deal collapses, and Wolfspeed is left with $1.1 billion of cash against about $1.7 billion of total debt and a business burning cash every quarter. The company went through Chapter 11 in 2025. A second restructuring is not off the table.
Action Plan
Do not chase Thursday’s open. The move from $31 to $37 in after-hours already priced in a meaningful portion of the good news. If you want exposure, the more disciplined entry is to wait for confirmation that at least the first tranche of conditions has been satisfied, which is likely to take several months.
If you already own WOLF, the 30-year loan commitment reduces near-term solvency risk enough to hold a small position. Trim any outsized exposure above 2% of portfolio. This is a turnaround, not a compounder, at current valuations.
Cheap Investor Checklist
- Does Wolfspeed satisfy the $750 million qualifying contribution requirement without catastrophic dilution?
- Do existing lenders approve the new senior secured facility? (They have priority claims.)
- Does gross margin turn positive on a non-GAAP basis within four quarters of first draw?
- Does the AI data center SiC revenue continue growing after the 50% quarter-over-quarter jump reported in Q2 FY2026?
- Does quarterly cash burn stay below $100 million ahead of loan funding?
- Watch the fully diluted share count: warrants plus convertibles plus DoW warrants could push it well past 120 million shares.
- Monitor ON Semiconductor and onsemi for SiC pricing signals; if competitors are cutting, Wolfspeed’s revenue recovery is slower.
Bottom Line
If the DoW loan closes in full, Wolfspeed becomes a better-financed company with a government customer locked in for defense and other national security-related wide bandgap applications. That is worth something. But the conditions are substantial, the dilution is real, and the business is still losing money on every dollar of revenue at the gross margin line. Buy the story only if you can hold through the conditions process, the additional qualifying contribution requirement, and the inevitable volatility. For everyone else, this is a watch-and-verify situation.