October 8, 2026
Bonus Content: Levi’s US Sales Are Slipping. International Is Not.
Hey there, bargain hunter.
On January 30th, Elon Musk quietly filed a document with the FCC.
It asks permission to launch 1,000,000 satellites.
Bloomberg confirmed it.
The Scoreboard
Satellites SpaceX has in orbit today: about 10,000
Time it took to get there: about 20 years
Satellites in the new filing: 1,000,000
That’s a 100x jump in fleet size
What actually happened
This isn’t about faster internet.
The filing is for AI data centers in space.
SpaceX calls it “the largest actionable total addressable market in human history.”
Big words. Here’s the part the market may be missing.
What the market is really saying
There’s one thing Elon can’t build himself:
The chip that runs every satellite.
One small public company owns that design, and SpaceX pays it on every chip.
The cheap-investor math is simple:
More satellites means more chips
More chips means more payments
If payments scale with units, a 100x fleet could mean a much bigger bill
See the ticker here >>
Action plan for tomorrow
Dylan, the analyst behind this research, has circled October 24th as a potential catalyst for this stock.
Is it a sure thing? No. FCC approvals take time, launch schedules slip, and small caps swing hard in both directions. That’s exactly why Dylan lays out the full case, including the risks, before you decide anything.
Bottom line
If SpaceX’s filing moves forward, then the company collecting a fee on every chip could be one of the quietest ways to play it.
And you don’t need to be a SpaceX insider. You can own this one in any brokerage account.
Get the full story before October 24th >>
The Buck Stops Here,
Kelly Maguire
Behind the Markets
Levi’s US Sales Are Slipping. International Is Not.
Hey there, bargain hunter. Levi Strauss dropped its fiscal Q3 numbers after the close on October 7, and the headline reaction was a shrug. Shares moved down a bit after hours. But underneath a soft US number is a genuinely different company than the one most investors think they own.
Scoreboard
Adjusted diluted earnings came in at $0.48 a share, well above the $0.36 analysts expected, while revenue rose 4% to $1.61 billion, just short of the $1.62 billion consensus. In the Americas, reported revenues increased 4%, but US revenue fell 1%. Levi adjusted its full-year revenue growth forecast slightly to around 7%, from a prior range of 7% to 7.5%. Profit guidance, however, went the other way: up.
The Real Reason the Stock Went Nowhere
Earnings beat by a third. Gross margin expanded 450 basis points to 66.2%. So why the muted reaction? Because the company faced challenges in its direct-to-consumer segment, particularly in the US and Europe. That DTC softness, especially in US stores, was the number the market locked onto. The revenue guidance trim to the bottom of the prior range confirmed the concern.
Here is what the market is underweighting: management said trends accelerated late in the quarter, and that early Q4 DTC growth had returned to positive territory.
What the Business Actually Is Right Now
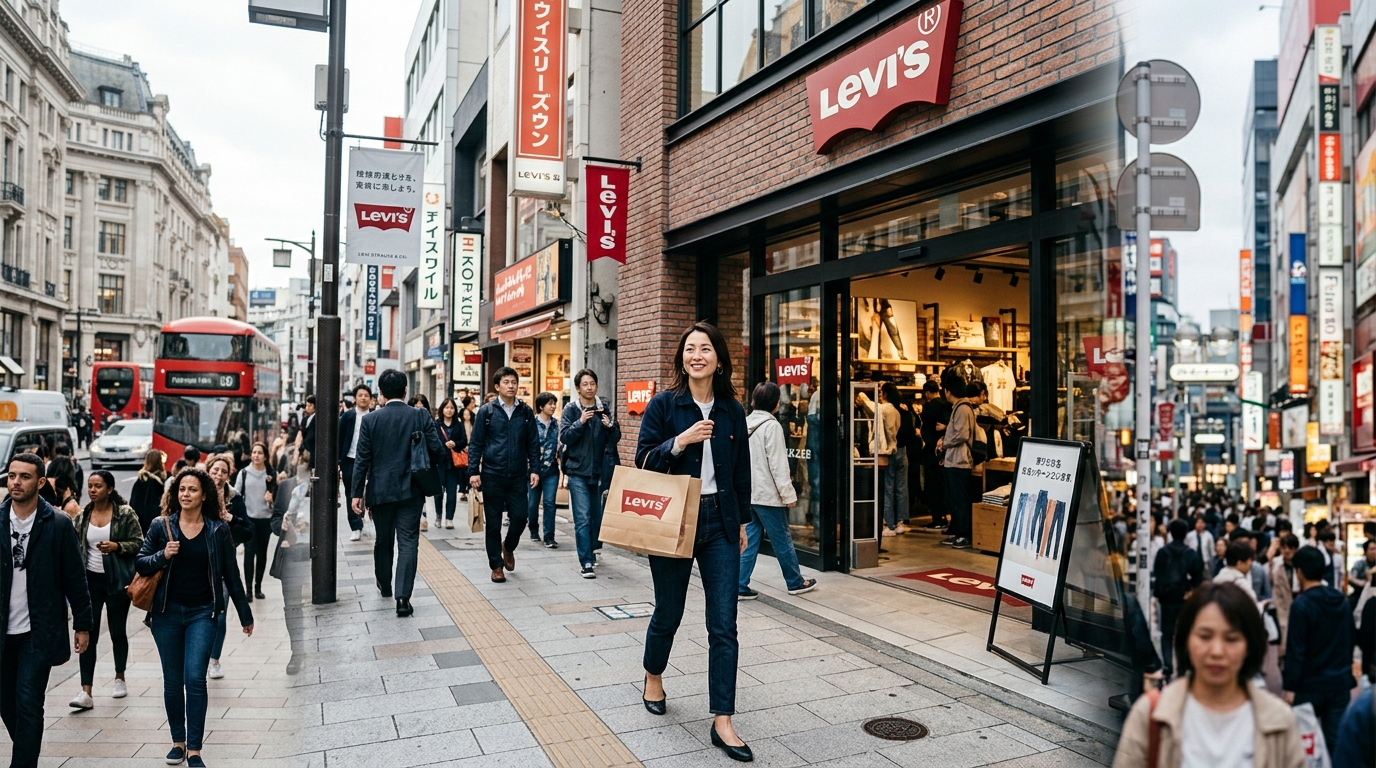
Levi makes jeans. You know that. What is less obvious is how much of the growth engine has shifted outside the US. International markets represented approximately 60% of the company’s revenues in the first half of fiscal 2026, up from 57% a year ago. That shift is not a blip. It is the strategy.
CEO Michelle Gass said the company has become “a more diversified, higher growth company,” with a larger international footprint and a more balanced mix of direct-to-consumer and wholesale sales. Categories outside Levi’s denim bottoms accounted for about half of top-line growth in the quarter.
Data Section
- Revenue rose 4% reported and 5% organically; year-to-date organic revenue growth reached 7%.
- Global wholesale up 6%; Asia net revenues up 10% organically.
- European net revenues rose 4% reported and 5% organically.
- Inventory down 3% from a year earlier.
- Gross margin: 66.2%, up 450 basis points year over year. Adjusted EBIT margin: 15.5%, with the tariff refund benefit, net of redeployment, contributing 330 basis points.
- Updated full-year guidance: adjusted EPS $1.54-$1.56, reported revenue growth about 7%, organic revenue growth about 6%.
- The company said it redeployed about $25 million of the tariff refund benefit in Q3 to support the business, and expects to redeploy about $60 million for the full year.
- Spring/summer 2027 wholesale pre-bookings are up at a high-single-digit rate.
Is It Cheap?
Valuation moves fast, and the specific PE figures in the last draft do not match widely used market data screens as of October 7, 2026. The key point still stands: the stock is priced as if the whole brand is in retreat. The US DTC segment is soft. Asia and Europe are not.
Bull / Base / Bear
Bull: Asia kept delivering double-digit organic growth. If DTC rebounds in Q4 as management expects and European bookings convert, the stock could trade closer to its historical range. That is a meaningful move from current levels.
Base: US DTC muddles along, international carries the load, earnings grow at a mid-teens pace. The stock grinds higher in line with earnings. Not exciting, but not dangerous.
Bear: The guidance assumes current tariff rates stay in place for the remainder of the year. Any escalation there, or a consumer spending pullback in Europe, compresses both revenue and the tariff refund buffer that padded this quarter’s margin.
Action Plan
This is not a screaming buy, but it is a reasonable one for a patient bargain hunter. The international engine is real and accelerating. The US softness may prove cyclical, not structural. You are not paying for perfection.
Consider scaling in: a starter position now, add on any further weakness tied to macro noise rather than fundamental deterioration. Watch Q4 DTC results closely. Management expects fourth-quarter revenue to grow at a mid-single-digit rate and DTC to return to at least mid-single-digit growth. That is the checkpoint.
Cheap Investor Checklist
- US DTC revenue: watch for return to positive growth in Q4
- Asia revenue growth: must sustain double digits to justify the international thesis
- European wholesale pre-bookings for spring 2027: already up high-single-digits, monitor conversion
- Gross margin ex-tariff refunds: the underlying expansion matters more than the one-time benefit
- Inventory levels: down 3% is healthy; any reversal signals demand risk
- Tariff policy: guidance assumes current rates persist for the rest of the year
- Valuation vs history and peers: update the multiples using your preferred data source before acting
Bottom Line
If US DTC traffic normalizes in Q4 and Asia keeps compounding at double digits, LEVI at current prices looks like the market is handing you the international growth at a discount because of American anxiety. If the American weakness deepens or tariffs escalate, the margin buffer shrinks fast. Know which scenario you are betting on before you buy.