September 28, 2026
The hard question comes after the pop.
Hey there, bargain hunter. This morning the UK housing sector handed you a 15% single-day move before most people had finished their coffee. The question worth asking now is whether that move was priced for reality, or priced for hope.
What 25 years on a Wall Street desk taught me about retirement income
I spent 25 years at Merrill Lynch and Vanguard watching the same play run, week after week, in every market condition imaginable. The money keeps coming in on every trade. Now that I’m on the outside, I’ve put together a free guide that breaks down exactly how this works, in plain English.
Scoreboard
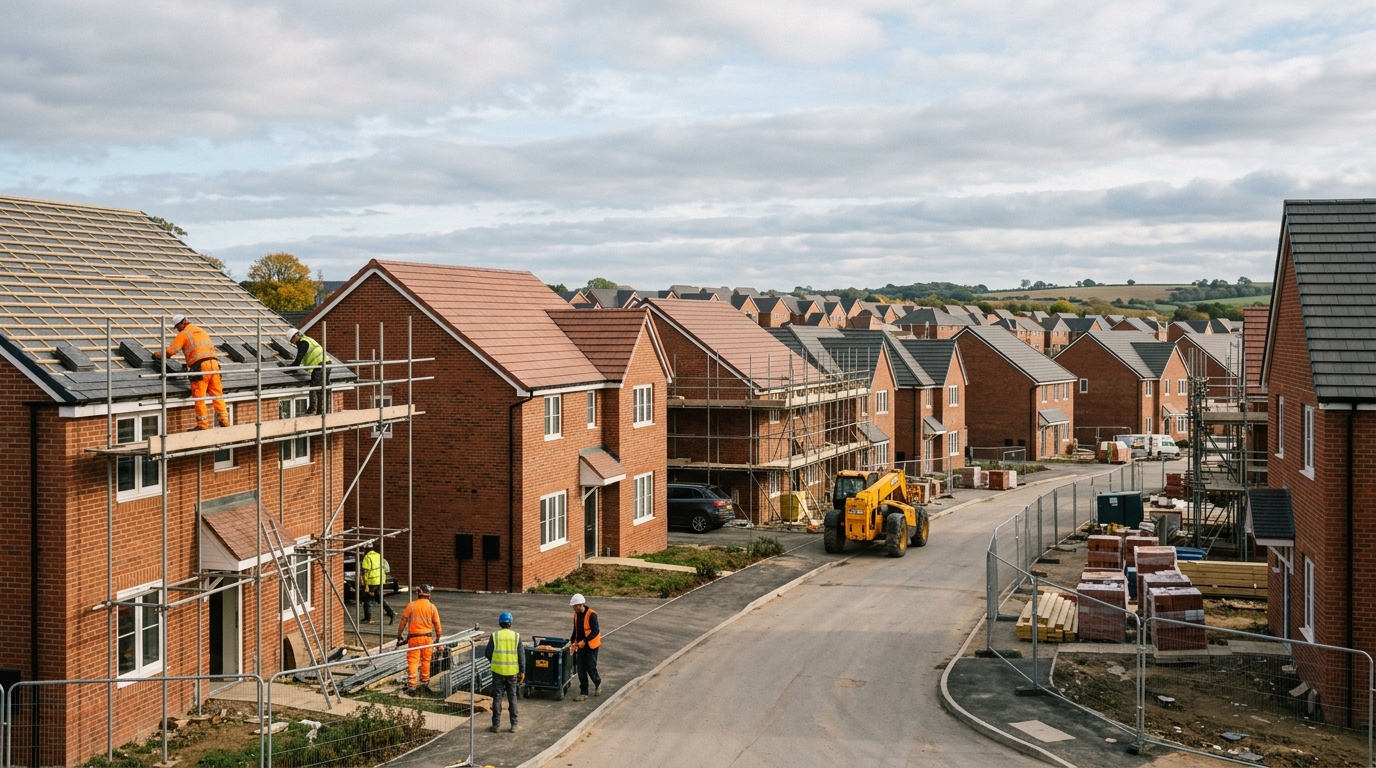
UK housebuilders ripped higher after the government said its “Your First Home” equity loan scheme will be confirmed at the October 28 Budget. Reuters reported shares of Persimmon, Barratt Redrow, Taylor Wimpey and Vistry rose between 13% and 17%. The index-level numbers and exact pence moves depend on your timestamp and data feed.
What Happened
Prime Minister Andy Burnham used the eve of Labour’s conference in Liverpool to announce “Your First Home,” a new equity loan scheme for England. Buyers need only a 2.5% deposit, with the government covering 20% of the property value via an equity loan. Reuters and the Guardian reported the equity loan is interest-free for five years. Income caps and local property price caps are intended to focus the scheme on buyers who genuinely cannot bridge the deposit gap without help. The detail arrives at Chancellor John Healey’s October 28, 2026 Budget; pre-registration is expected before year-end.
The scheme is a direct revival of Help to Buy, which ran from 2013 and closed to new applications in England on 31 October 2022. Official statistics put total Help to Buy: Equity Loan completions at just under 370,000, so “over 369,000” is directionally right but best treated as “almost 370,000.”
The Real Reason Markets Moved
This is a demand stimulus dropped into a sector that was already beaten down. The scheme is not just good news; it is good news arriving at a moment of maximum pessimism.
“By September 30, Elon Musk’s Prophecy Will Fulfill Itself”
The two investment legends who picked Nvidia 10 years ago are predicting that…
By the end of this month, Elon Musk’s new AI breakthrough they call “M.A.G.I…”
Will collide with a strange market pattern with a flawless 100% track record of massive market gains.
But cheap plus catalyst is not automatically a buy. The budget detail still needs to land, and UK borrowing is already running well above forecast.
Remember What Happened Last Time
When Help to Buy wound down, Savills warned it would contribute to a decline in housing delivery over the following 18 to 24 months. They were directionally right about delivery cooling as the market softened.
Two company datapoints are solid: Taylor Wimpey completions fell about 30% in 2023 versus 2022. Barratt reported total completions down 28.5% in the six months to 31 December 2023 versus the prior year period.
“Your First Home” is designed with tighter targeting than its predecessor, but the structural dynamic is identical: new-build demand pulled forward, supported by government balance sheet risk, with housebuilder margins tied to the scheme’s longevity.
Wall Street Priced These Two Companies Backwards
Company A: almost no revenue, zero plants running, valued near $10 billion in the biggest clean-energy IPO in history. Company B: sixty years of operations, nearly $1 billion in annual revenue, two decades of uninterrupted dividends, a 15-year Google contract – still priced like a utility. One of those prices is wrong. With a federal land auction on October 20th and solar and wind’s tax credits terminating while geothermal’s run through 2033, the correction may not wait long.
Is It Cheap?
Before today’s rally, yes, emphatically. After a 14-15% single-session move, the math tightens. Build-cost inflation is expected to be low to mid-single digits in 2026 at Taylor Wimpey. And planning permissions in England for the year to June 2026 came in at a provisional 212,000, down 12% year-on-year, which means the pipeline is shrinking even as demand policy improves.
Bull / Base / Bear
- Bull: Budget confirms generous scheme terms, mortgage rates fall further in 2027, completions recover to 2022 levels, and margins follow. Persimmon’s in-house materials operation gives it an extra margin buffer.
- Base: Scheme launches with tighter caps than hoped, demand improves modestly, sector margins trough at 8-9% before recovering. Today’s pop partially gives back over the next month as budget detail disappoints versus morning expectations.
- Bear: Budget waters down the scheme, UK borrowing pressures force further cuts elsewhere, and Vistry, which has issued multiple profit warnings since 2024, faces another downgrade. Specific broker targets move fast, so focus less on any single 180p-style number and more on the direction of estimates after the Budget details.
Action Plan
Do not chase at today’s open prices. If you wanted exposure before this morning, the moment to have bought was last week. Now you wait. The October 28, 2026 Budget is the next hard catalyst. If Healey’s detail is generous on income caps and property price limits, the pop has legs. If the caps are punitive and the scheme is small in funding scope, the sector retraces half this move by November.
Among the names, Persimmon and Barratt Redrow remain the most defensible on land bank depth and balance sheet. Berkeley’s smaller move today reflects its higher-price-point exposure, which makes it less directly addressable by a scheme with local price caps. Vistry remains the highest-risk name in the group.
Cheap Investor Checklist
- Budget detail on October 28, 2026: income caps and property price caps confirmed?
- Funding size disclosed: how many purchases does the government actually expect to support per year?
- Developer fee structure: how much of the scheme’s running cost falls on housebuilder margins?
- Taylor Wimpey build-cost inflation trajectory in H2 2026 update
- Persimmon reservation rates at next trading statement
- Vistry: any further profit warning risk before year-end?
- Planning permission volumes for Q3 2026: is the pipeline recovering or still falling?
Bottom Line
If the October 28, 2026 Budget delivers a well-funded scheme with workable price caps, today’s move is the start of a re-rating. If it arrives with tight fiscal constraints and small volume targets, you have just watched the sector lend itself a day’s worth of future returns. The history of Help to Buy is instructive: builders that rode the scheme up also absorbed the correction when it ended. Buy on budget confirmation, not on conference announcements.