September 24, 2026
Bonus Content: Worthington Enterprises Beat Every Number. Is It Still Cheap?
Editor’s Note: We’re delighted to bring you the latest stock pick from our colleague, Wall Street legend Marc Chaikin. You may recognize Chaikin’s name from frequent appearances on CNBC, Bloomberg or Fox Business. His client list has included billionaires such as Paul Tudor Jones, Steve Cohen, and George Soros. His Power Gauge system flashed bullish on Nvidia right before it rose 50,001%. And it just flashed bullish on another off-the-radar AI stock poised to trigger a $248 trillion “White Swan” event as soon as Sept. 29. See below for Marc’s research and free recommendation.
Dear Reader,
I’ve uncovered the single best AI stock in the world.
And it could explode in value on or before Sept. 29.
That’s the date I anticipate a major announcement.
It relates to a brand-new technology this company just launched.
A technology so powerful…
It could speed up AI breakthroughs 360 times over.
Breakthroughs in medicine, energy, quantum computing and AI itself…
Breakthroughs that were five years away…
Could come in just FIVE DAYS once this technology launches.
I’m talking about something I call AI “micro clusters.”
These are clusters of AI compute that will soon replace the massive data centers blotting the American landscape right now.
Micro cluster technology uses 99% less energy than data centers.
It takes up 99% less real estate.
Yet it’s more than 1 trillion times more powerful than today’s data centers.
Micro clusters are about to trigger this $248 trillion AI “White Swan” event.
Those who understand what’s coming could get very rich.
Those who ignore what’s coming could see their AI portfolios wiped out.
The good news?
One company has engineered the special chips that will power this breakthrough.
The U.S. government is pouring billions into this company’s account ahead of the launch.
And when this story breaks into the mainstream…
I believe billions, even trillions more dollars will flow into this stock.
→ It’s not Nvidia.
→ It’s not Apple.
→ It’s not SpaceX.
It’s an off-the-radar AI play that could explode on or before Sept. 29.
The time to get in is right now.
So, I created this urgent presentation detailing the whole opportunity.
I explain the technology.
I take you “inside” the secretive lab where it’s being finalized.
And I even give you the name and ticker of the company behind the coming technology revolution.
Fair warning: This presentation contains time-sensitive information.
I may have to take it offline as soon as 12 midnight, tonight.
Good investing,
Marc Chaikin
Founder, Chaikin Analytics
P.S. The company I name in this presentation represents the future of AI. Its new technology is about to replace AI data centers when it comes to major AI breakthroughs. And it will, I predict, trigger a $248 TRILLION reboot of the AI markets… and one of the biggest moneymaking opportunities we’ll ever see… about 50 times bigger than the whole AI boom to date, in fact. Go here for full details, including the company’s name and ticker. And if interested, I urge you to get in on or before Sept. 29, when this company presents its latest findings at a major tech conference in Europe.
Worthington Enterprises Beat Every Number. Is It Still Cheap?
Hey there, bargain hunter. Worthington Enterprises (NYSE: WOR) posted its fiscal Q1 2027 results after the close on September 22, then held its conference call before the open on September 23. It cleared the bar on every line. The stock had already jumped roughly 10% in the prior week on expectations; it surged another 15% on September 23. Now it sits around $59. The question is whether the move has finally priced in the story, or whether the market is still sleeping on what this business is becoming.
Scoreboard
- Revenue: $343.9 million, up 13% year over year, beating the $331.3 million consensus
- Adjusted EPS: $0.82, ahead of $0.75 expected (prior year: $0.78)
- Adjusted EBITDA: $74.0 million, up 10%, topping $69.6 million estimates; margin 21.5%
- Free cash flow: $54.0 million, nearly double the prior-year quarter
- Operating cash flow: $66.7 million, up $25.7 million year over year
- Buybacks: 335,000 shares repurchased for $18.2 million
- Dividend: $0.20 per share declared, payable December 29, 2026
What the Business Actually Does
Worthington makes pressurized containment products, ceiling suspension systems, light-gauge metal framing, and specialty tools sold through two segments. Building Performance Solutions (BPS) accounts for the larger share of revenue and covers products like HVAC and cooling tanks, data center thermal management vessels, and building construction components through joint ventures WAVE and ClarkDietrich. Trade and Specialty Solutions handles handheld torches, propane cylinders, balloon kits, and drywall tools sold through mass retailers.
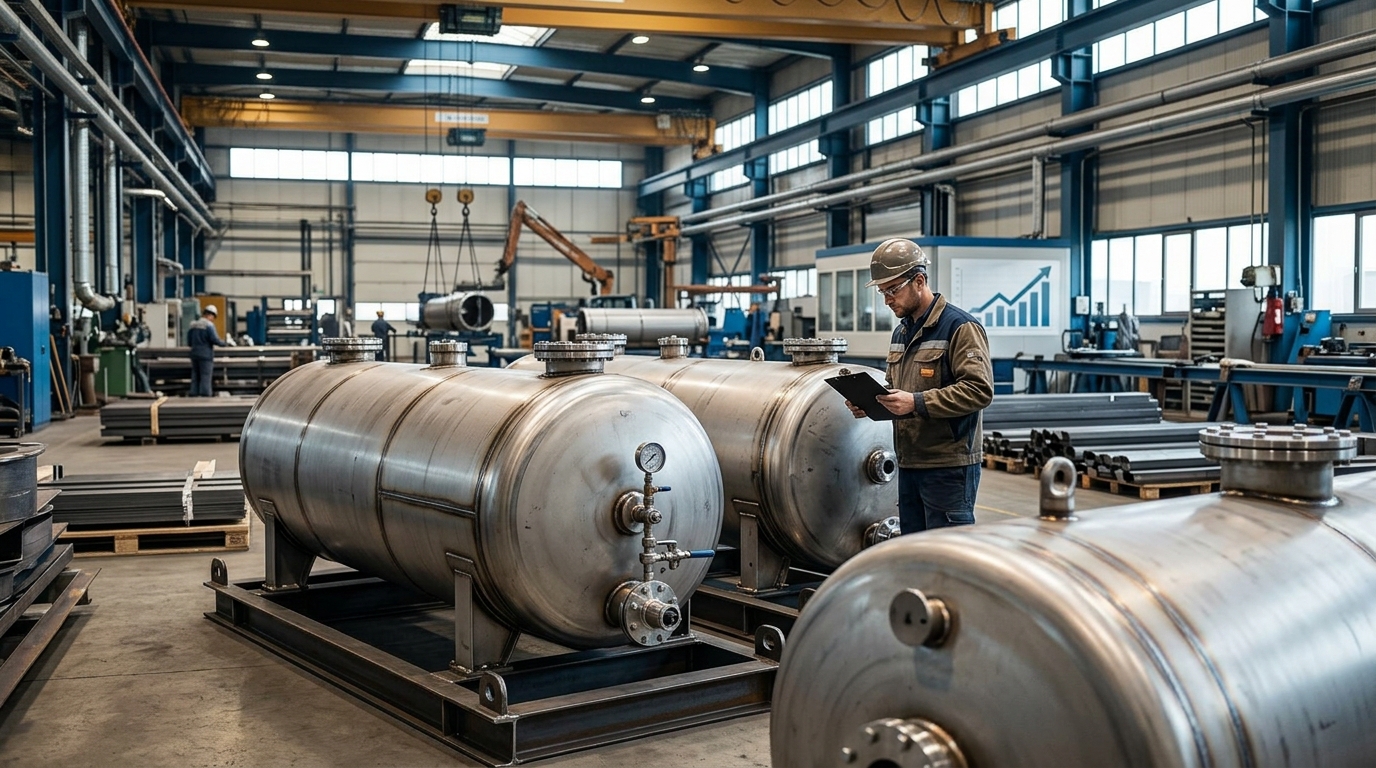
The sleeper inside BPS is ASME tanks, the pressure vessels Worthington engineers for liquid-cooling systems inside data centers. Management said ASME tank revenue was $13 million in Q1 and expects it to grow sequentially in each remaining quarter of fiscal 2027, weighted to the back half. CEO Joe Hayek said industry sources suggest the liquid-cooling and thermal-management market for ASME tanks could be more than 10 times the size of the legacy market in the next few years, while flagging that a pipeline is not revenue and conversions can take time.
The Numbers That Matter
- BPS revenue: $215.1 million, up 16.4% year over year; organic growth 6%, acquisitions added $19.2 million
- BPS adjusted EBITDA margin: 27.8%, down from 32.4% a year ago
- Trade and Specialty revenue: $128.8 million, up 8.3%; EBITDA margin expanded to 18.6% from 13.6% a year ago
- WAVE equity income: $35.1 million, up $2.7 million year over year
- Net debt: about $251 million (total debt $305.6 million less $55.1 million cash); 4.23 million shares remain under the repurchase authorization
Steel availability tightened during the quarter. Management said extended lead times created production and scheduling disruptions across construction and balloon product lines, and that the A2L refrigerant transition created an estimated $7 million year-over-year headwind to adjusted EBITDA as demand normalized after earlier inventory building.
Is It Cheap?
At roughly $59, WOR trades around 14x to 16x forward earnings depending on the data source and estimate set. On an EV/EBITDA basis, using Q1 fiscal 2027 net debt of about $251 million and a market cap around $2.9 billion, you get an enterprise value a little over $3.1 billion. That can look like roughly 10x on a trailing adjusted EBITDA figure in the low $300 millions, but that EBITDA figure varies by definition and period, so treat the multiple as a range rather than a single point.
GurFocus puts GF Value near $58.33 on the stock, flagging a slight overvaluation at current prices. Consensus price targets and rating mixes move around with the tape, but the basic debate is stable: the gap between WOR’s multiple and higher-multiple building-products peers leaves room, but only if ASME tank revenue actually scales as projected.
Bull / Base / Bear
Bull: ASME tank revenue doubles or triples in fiscal 2027’s second half, BPS margins recover as steel normalizes, and WAVE JV earnings hold up. On that path, $4.00 in adjusted EPS is achievable and 16x that gets you to $64.
Base: ASME tanks grow sequentially but modestly; steel headwinds ease by Q3; Trade and Specialty margins hold their new 18% floor. Adjusted EPS comes in around $3.50, and the stock settles in the $52 to $58 range.
Bear: Data center project timelines slip, steel stays tight, A2L normalization takes longer than guided. Free cash flow compresses, buybacks slow, and the premium for the data center angle deflates. Back to low $40s.
Action Plan
The 15% single-day move means you are not buying a secret. If you do not own it, a starter position in the $56 to $59 range makes sense, sizing up on any pullback toward $52. Trim if it runs past $65 without a corresponding revision to ASME revenue expectations. Watch the Q2 results for sequential ASME tank revenue confirmation.
Cheap Investor Checklist
- Does ASME tank revenue grow sequentially in Q2 fiscal 2027? (management said it expects this)
- Does BPS EBITDA margin recover above 28% as steel availability improves?
- Do WAVE and ClarkDietrich JV earnings hold near current levels?
- Is net debt trending toward $200 million or below by fiscal year end?
- Does buyback pace continue at $15 million or more per quarter?
- Does Trade and Specialty margin hold above 17% after Q2 seasonality?
- Are data center pipeline conversions accelerating into the Investor and Analyst Day on November 10, 2026?
Bottom Line
Worthington beat cleanly, free cash flow nearly doubled, and the data center ASME tank opportunity is real enough to have management talking about sequential growth through fiscal 2027. If ASME revenue scales as expected and steel headwinds ease by mid-year, the stock looks cheap relative to slower-growing building-products peers. If the pipeline stalls and steel constraints persist, you are paying a fair price for a solid but ordinary industrial. Position size accordingly.