September 14, 2026
Bonus Content: Coal Demand Hits a Record. The Stocks Are Still Priced for Decline.
Editor’s Note: Our friend Louis Navellier has been a guest at Mar-a-Lago, President Trump’s private residence in Palm Beach, Florida. He’s one of America’s top tech investors, managing a $1.1 billion portfolio – including $358 million in AI stocks. He called Nvidia before it went up 44,000%. He predicted the dot-com crash and the 2020 Covid rally. And now he’s revealing what he calls the biggest prediction of his 40-year career.
Dear Reader,
Deep in the Appalachian Mountains of Tennessee…
Behind a triple layer of razor wire and a security clearance most Americans will never hold…
Something extraordinary is being built.
You won’t hear about it on CNBC.
The Wall Street Journal hasn’t touched it.
And yet, according to my research, what’s happening inside this facility will trigger one of the most dramatic wealth transfers in American history.
I know this place well.
It’s the same “secret city” that gave America the atom bomb.
The same lab that turned the tide of World War II.
And now – under a directive from President Trump himself – America’s top scientists and engineers have returned to this site for one purpose:
To build a new category of AI computer so powerful…
Trump himself compared it to a Manhattan Project – but for AI.
And I believe – based on months of exhaustive research – this device is going online very soon.
When it does, it won’t just leapfrog ChatGPT, Gemini, and even Elon’s Grok…
It will accelerate AI breakthroughs by 360-fold.
Breakthroughs that used to take five years? They’ll happen in five days.
And that will trigger a $100 trillion reset of the AI markets – the biggest disruption I’ve seen in my 40-year career.
I called Nvidia before it went up 44,000%. Apple before it went up 36,000%. Microsoft before its 60,800% rise.
But nothing in four decades has looked quite like this opportunity.
I’ve prepared a full presentation with the details – including the name and ticker of the one company I believe is best positioned to profit.
Click here to watch it now, free of charge.
Regards,
Louis Navellier
Senior Quantitative Investment Analyst, InvestorPlace
P.S. The “secret city” in Tennessee has been off-limits to the public for decades. But what’s being built there right now is about to become impossible to ignore. When Trump flips the “on switch,” I expect it to trigger a $100 trillion shock to the AI markets. Go here for full details – including the ticker symbol – before this video comes down.
Coal Demand Hits a Record. The Stocks Are Still Priced for Decline.
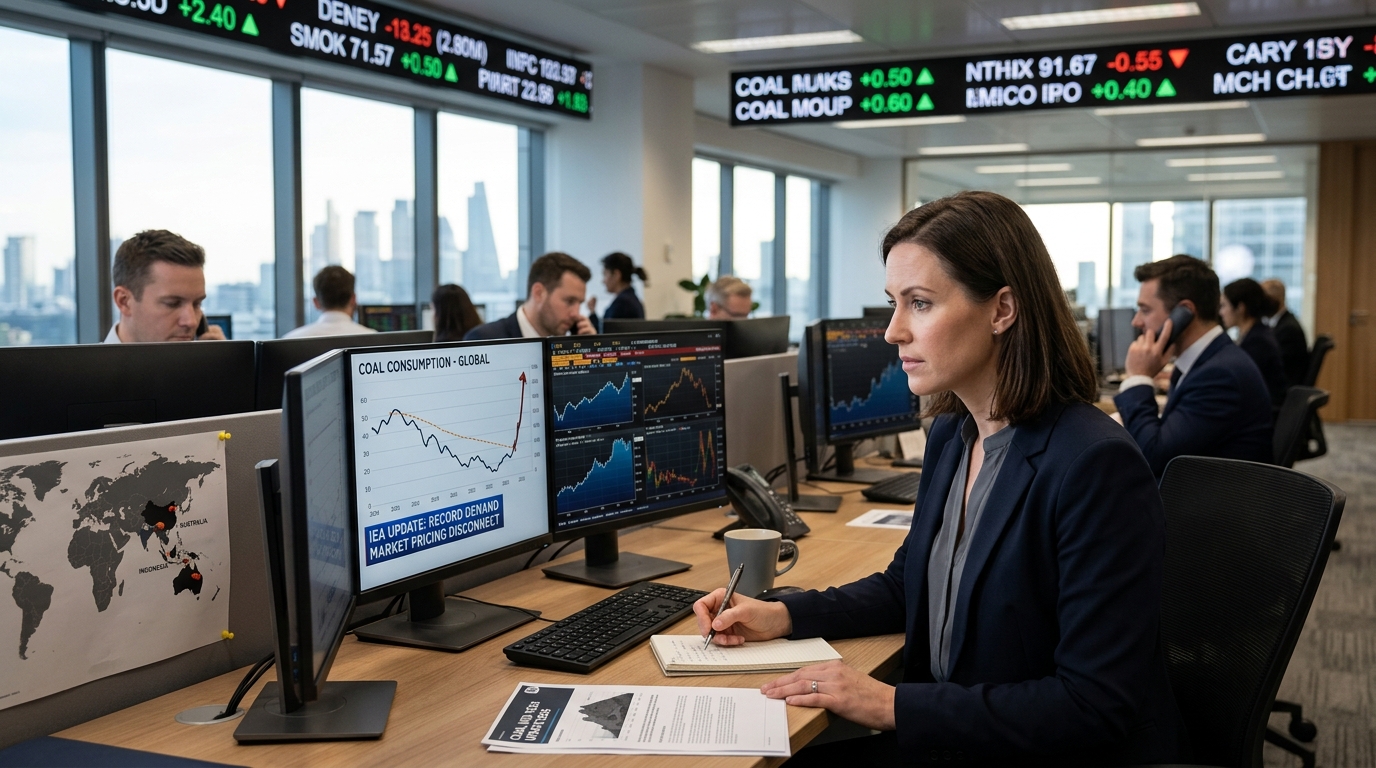
Hey there, bargain hunter. A chokepoint that carries almost no coal just sent global coal demand to a record high. That is the cleanest second-order trade of the Hormuz war, and it landed in an IEA report on September 10, 2026 that most equity investors have not yet digested.
Scoreboard
The IEA’s Coal Mid-Year Update 2026 reversed a forecasted decline and now sees global demand rising 1.2% to 8.94 billion tonnes this year, a new all-time high. Newcastle thermal coal, the seaborne benchmark, was trading around $146.75 per metric ton as of September 11, 2026. The IEA had expected coal consumption to slip slightly entering 2026. That call is now in the bin.
The Real Reason
No coal moves through the Strait of Hormuz. The conflict’s direct impact on coal supply was zero. The indirect impact has been enormous. From late February 2026, LNG loadings from Qatar and the UAE collapsed as tanker traffic through the strait seized up. Those two exporters had accounted for almost 20% of global LNG trade in 2025. Delivered gas prices rose. In every power system that held both a gas fleet and idle coal capacity, operators moved down the merit order toward coal.
The IEA named the switchers explicitly: Europe, Japan, South Korea, China, and other markets. Japan’s METI temporarily suspended utilization caps on inefficient coal-fired power plants for fiscal year 2026 after an announcement on March 27, 2026, with some estimates targeting about 0.5 million tonnes of LNG savings per year. Korea lifted seasonal caps. Because electricity accounts for about two thirds of global coal use, a shift in dispatch math ripples through the entire market fast.
China’s demand is set for a 1% increase to 5 billion tonnes. India’s rises 4.2% to 1.353 billion tonnes, reversing last year’s brief dip. If the strait stays largely closed into 2027, the IEA says another record is possible.
Deep Dive
Thermal coal producers are simple businesses. They dig coal, put it on ships or trains, and sell it to utilities under long-term contracts or on the spot market. The upside is enormous operating leverage when prices run; the downside is that the assets depreciate, regulations tighten, and most institutional capital has been told not to own them.
That last point is the opportunity. Peabody Energy (BTU) trades at roughly 3x forward EV/EBITDA and has described itself this year as having zero net debt. Alpha Metallurgical Resources (AMR) is a purer met coal play, but its thermal byproduct volumes are being guided higher as spot economics improve. Arch Resources (ARCH), diversified across met and thermal, trades at a discount to its met coal peers despite comparable margins.
Data
- Newcastle benchmark: $146.75/tonne as of September 11, 2026
- Thermal coal prices reached $150/tonne at points in H1 2026, per IEA data
- BTU: ~3x forward EV/EBITDA; the company has described itself as having zero net debt
- AMR: 52-week range $133.64 to $253.82; FY2025 revenue about $2.1 billion
- Global coal production is expected to remain above 9 billion tonnes for a third consecutive year
- IEA downside scenario: if the Strait of Hormuz situation eases, the pullback risk is tied to lower gas prices and less gas-to-coal switching
Is It Cheap?
BTU at roughly 3x EBITDA is priced as a runoff asset in managed decline. The IEA just said demand is at a record. That is a mismatch worth examining. AMR carried a 52-week low of $133 against a high above $253; the stock has been punished by a Dominion Terminal Associates equipment issue and softer met coal prices, neither of which changes the thermal demand picture. ARCH trades at a substantial discount to pure-play met coal peers, even though its Leer Complex remains a low-cost operation.
The sector’s structural discount exists because most long-only funds cannot hold it and most ESG screens exclude it. That forced selling created the opportunity. The IEA’s 2026 record demand figure is the first hard quantification of how large that opportunity became.
Bull / Base / Bear
Bull: Hormuz stays restricted well into 2027, gas prices remain elevated, and coal demand hits a second consecutive record. BTU and ARCH re-rate from 3 to 4x EBITDA toward 6 to 7x as cash returns compound.
Base: Hormuz partially reopens, demand slips modestly from the 8.94 billion tonne peak but holds above 2025 levels. Prices consolidate near $130/tonne. Producers generate solid free cash flow and continue buybacks at depressed valuations.
Bear: A Hormuz peace deal, a mild winter, and accelerated renewable buildout in China combine to collapse spot prices below $100/tonne. Contract coverage provides a cushion but earnings compress sharply.
Action Plan
For a conservative posture: BTU is the starting point. A strong balance sheet and a low valuation multiple among large U.S. producers limit the downside. Scale in over two to three weeks rather than buying the news spike whole.
For a more aggressive posture: ARCH’s Leer Complex exposure gives you leverage to both thermal and met coal markets simultaneously. AMR is a higher-volatility expression of the same thesis; the Dominion terminal issue is operational, not structural.
Glencore (OTC: GLNCY) offers commodity-trading optionality on top of its coal production, though the diversified business means coal is only part of the story.
Cheap Investor Checklist
- Newcastle benchmark: watch for sustained hold above $130/tonne as base case confirmation
- Hormuz LNG traffic data: any recovery back toward pre-war flow is a demand headwind
- BTU Centurion ramp: met coal volumes from this mine are a separate upside catalyst to track quarterly
- AMR Dominion Terminal: restoration timeline determines when volume guidance improves
- China coal safety inspections: easing of post-accident domestic output restrictions supports import demand
- IEA 2027 update (expected Q1): will confirm or reverse the record demand thesis
- FCF yield on BTU: at about 3x EBITDA, the cash-return story depends heavily on realized pricing and contract coverage
- XLU utility sector: weaker utility earnings can signal coal substitution continuing; watch as a read-through
Bottom Line
If the Strait of Hormuz stays largely closed and gas prices hold above 2025 averages, thermal coal producers priced as sunset businesses are sitting on a demand record. If Hormuz reopens quickly and LNG flows normalize, the trade compresses, and the magnitude depends on how much gas-to-coal switching unwinds. BTU at roughly 3x EBITDA is one of the cleaner, lower-multiple ways to express the theme. The market priced these stocks for permanent decline. The IEA just said demand has never been higher.