Back in the 1860s, settlers from France, Italy, and Germany built grand Parisian boulevards…
…neoclassical facades…
… and cobblestone Bavarian villages halfway across the globe.
Then the rest of the world largely forgot about them.
Today, expats are uncovering a European standard of living…
… Lakefront rental homes for $721 a month…
… private chauffeur service…
… and elite healthcare – completely free from tourist crowds and inflated European price tags.
UniCredit Is Set to Control Commerzbank. Worth the Price?
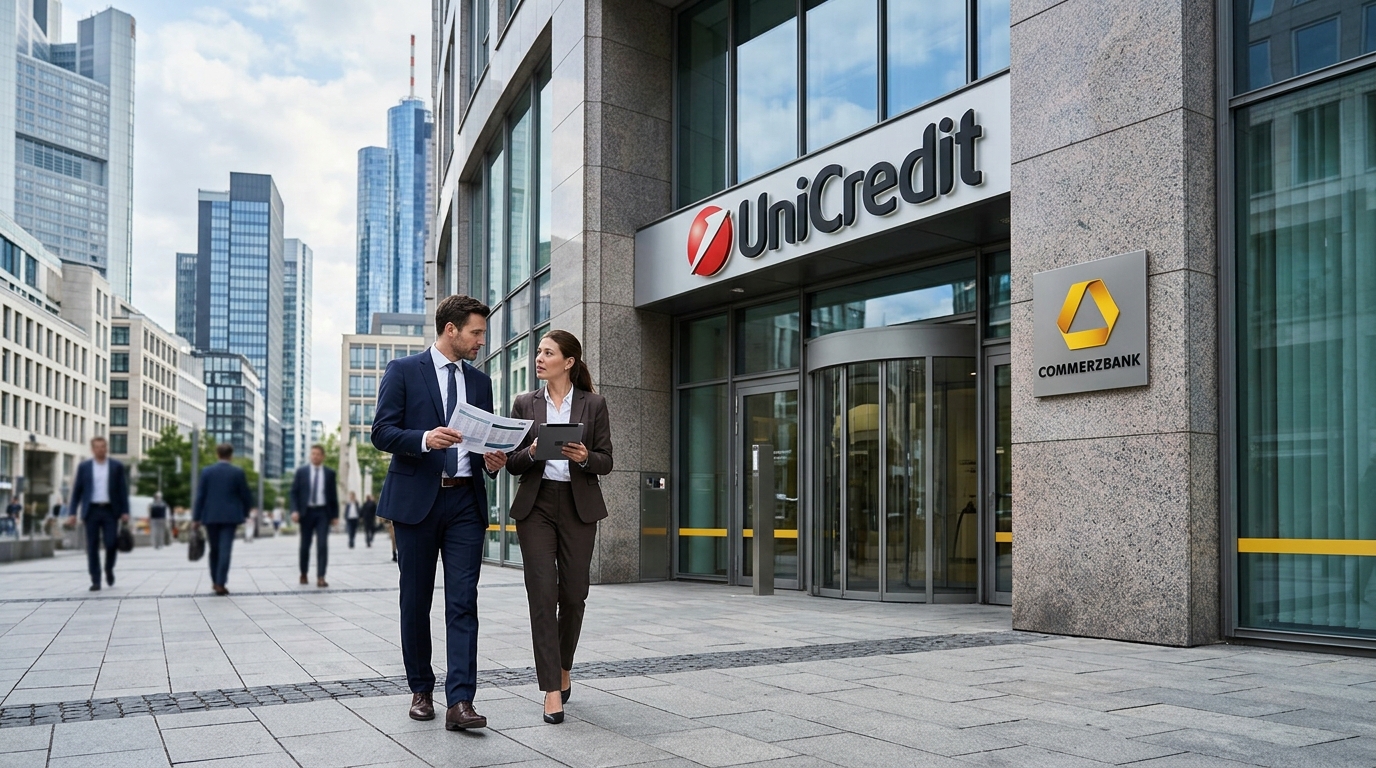
Hey there, bargain hunter. Germany’s second-largest bank is about to lose its independence, and the market is pricing in the win before the ink is dry.
Scoreboard
Commerzbank (CBK.DE) jumped roughly 5% this week after Reuters, citing three people with direct knowledge, reported that UniCredit (UCG.MI) is set to receive unconditional European Commission antitrust clearance for its takeover. The formal decision is due by November 16. The ECB already signed off in October. UniCredit CEO Andrea Orcel says all remaining regulatory approvals will arrive before the end of November, faster than anyone expected.
The stock now trades around €40, up from a 52-week low of €29.32. That is a 36% move off the floor in roughly eight months.
What Actually Happened
UniCredit launched a voluntary share-swap offer in March 2026, offering 0.485 of its own shares for each Commerzbank share, implying roughly €30.80 per share at launch, a 4% premium to the closing price that day. Commerzbank’s board rejected the offer in May, calling the premium inadequate and noting the implied offer value had fallen to a discount versus the market price on the day the offer document was published. Since the offer closed in the summer, UniCredit has accumulated 48% of Commerzbank through direct holdings and derivatives.
Berlin still objects. The German government holds 13.3% of Commerzbank and is demanding two supervisory board seats. UniCredit wants all ten shareholder-appointed seats and has challenged that demand. EU reviewers flagged the arrangement as a potential legal problem but expect the issue to be resolved alongside, or just after, the mid-November clearance.
The Business and the Numbers
Here is what UniCredit is absorbing. Commerzbank posted Q3 2026 net profit of €859 million, up 45% year on year. Revenue climbed 8.9% to €3.199 billion. For the first nine months of 2026, net profit reached €2.669 billion, a 41% increase and a record for any nine-month period in the bank’s history. Full-year guidance sits at a minimum of €3.4 billion in net profit and around €13.2 billion in revenues.
Commerzbank is not the only European bank posting record profits while the market debates whether the numbers are sustainable. Lloyds doubled its statutory profit yet still trades off its highs, raising the same question about whether strong earnings translate into shareholder value.
One wrinkle: Commerzbank trimmed its 2026 net interest income outlook to around €8.5 billion from around €8.6 billion, citing tougher competition for deposits. The profit target held. That is the crux of the case.
Commerzbank also plans total capital returns of around €3.2 billion for 2026 through buybacks and dividends, including a share buyback of up to €1.2 billion. Return on tangible equity hit 12.5% in Q2, a record.
Is It Cheap?
At €40 per share and a market cap near €43 billion, Commerzbank trades around 1.33x tangible book value. That is a premium to Deutsche Bank (about 0.73x) but well below what a business delivering a 12%+ return on tangible equity should theoretically command. When Commerzbank rejected UniCredit’s offer, independent equity analysts placed the median target price at approximately €42.00. The stock is now getting close to that level on its own. UniCredit itself, the acquiring currency, trades around 1.58x book.
The takeover was structured as a share swap at 0.485 UniCredit shares per Commerzbank share. With UniCredit in the low-€80s range recently, that ratio now implies a materially richer consideration than the €30.80 originally flagged. UniCredit is paying more in economic terms than it initially appeared to offer, because its own stock has risen sharply.
Bull / Base / Bear
- Bull: EU clears the deal unconditionally by November 16. UniCredit installs its board nominees, launches integration, and extracts cost synergies from two overlapping German retail and SME networks. Commerzbank’s €3.4 billion profit target holds. The combined entity becomes a genuine pan-European bank with pricing power Deutsche Bank cannot easily match.
- Base: Clearance arrives on schedule but the Berlin board-seat dispute drags into early 2027. Integration is slower than Orcel promises. Deposit margin pressure weighs on Commerzbank’s standalone earnings, partially offsetting synergy gains.
- Bear: Germany’s government escalates the governance fight. Integration costs and potential job cut provisions, with one union estimating up to 10,000 roles at risk, dent near-term earnings. UniCredit’s own shares correct, reducing the implied consideration value just as Commerzbank investors are locked in.
Action Plan
If you do not own CBK.DE, the arbitrage has largely closed. The stock is trading close to analyst median targets and the deal is essentially priced in. Chasing here means betting on a synergy story that will take years to materialise, not on a catalyst that hasn’t happened.
If you own UniCredit, the more interesting question is whether Orcel is buying well. He is acquiring a business at above tangible book, using his own appreciated currency. The deal creates European scale. Whether it creates value at this price depends entirely on whether a combined entity can hold the deposit margin, sustain a double-digit return on tangible equity, and absorb restructuring charges without burning the capital returns that make UCG attractive in the first place.
Cheap Investor Checklist
- EU Commission decision by November 16: unconditional or not?
- Berlin board-seat dispute: resolved before or after clearance?
- Commerzbank full-year net profit: does it hit the €3.4 billion floor?
- Net interest income: does the around-€8.5 billion revised guide hold through Q4?
- UniCredit share price: the swap ratio means CBK holders are exposed to UCG moves until settlement.
- Integration timeline: watch for an extraordinary shareholder meeting date as the first concrete signal.
- German government stake: 13.3% is enough to complicate a board vote. Track any government signals on selling down.
Bottom Line
If the EU clears this unconditionally by November 16 and Orcel installs his board nominees before year-end, UniCredit’s German footprint becomes the largest cross-border banking combination Europe has seen since the financial crisis. That is a genuine strategic win. But CBK.DE at around €40 is not a bargain. It is a fair price for a well-run bank that is about to lose the ability to set its own strategy. The cheap entry was the €29.32 low in March 2026. Right now, you are paying for the story that everyone else already knows.