Dear Reader,
Want a debt-free retirement…?
It’s possible in Western Europe.
Eric and Debbie (both in their 60s) realized they’d need to keep working well into their 80s just to afford a normal life, they knew they’d never afford to retire…
Until they found out about what we call the “Social Security Swap.”
It’s way for Americans to swap the U.S. for a life in Europe.
Eric and Debbie swapped Burbank, California for an early retirement in Western Europe…
Today, they live in a charming chalet on a country club resort…
…with a golf course, tennis courts, pools, and a hotel for when family and friends visit…
The price?
This country club home cost only $81,000.
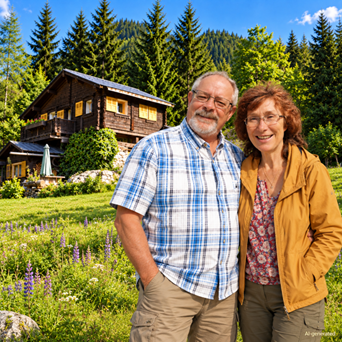
This couple went from “absolutely broke” to a debt-free retirement in Europe.
I’m Jennifer Stevens, Executive Editor of International Living, the #1 resource for overseas living…
Eric and Debbie are just one of the endless stories of Americans who’ve discovered a better life overseas…so could you…
Sincerely,
Jennifer Stevens
Executive Editor, International Living
Vertex Has 5 Revenue Pillars. The Market Prices One.
Hey there, bargain hunter. Vertex Pharmaceuticals just handed you a Q3 that most biotech CEOs would tattoo on their forearms, and the stock is sitting around $547. The question worth asking right now is not whether the business is good. It is whether the market has fully caught up to how many businesses Vertex has actually become.
Scoreboard
Q3 2026: $3.44 billion in revenue, up 12% year over year. Full-year guidance raised again, now $13.15 billion to $13.25 billion. Adjusted operating margin at 41%. Cash on hand: $9.8 billion, even after spending roughly $9 billion on the Crinetics acquisition and buybacks, offset by $4.5 billion in term loan proceeds.
What Actually Happened
Cystic fibrosis still runs the engine. ALYFTREK posted $706 million in Q3 alone, now reimbursed in 32 countries. CF accounts for roughly 95% of total product revenue, which is the number bears keep circling. Fair enough. But the non-CF lines are now moving fast enough to matter.
JOURNAVX, the first new class of pain medicine approved in the U.S. in over 20 years, generated $58 million in Q3, up 18% sequentially and nearly triple its Q3 2025 revenue. As of August, it became the most prescribed branded oral pain medicine in the U.S. More than 1.6 million patients treated since launch. Over 750,000 prescriptions filled in Q3 alone. CASGEVY, the gene-edited cell therapy for sickle cell disease and beta thalassemia, added $99 million, up 30% sequentially.
The Real Reason This Matters Now
The fifth franchise is 24 days away from an FDA decision. Povetacicept, a dual BAFF and APRIL inhibitor for IgA nephropathy, carries a PDUFA date of November 30. It holds FDA Breakthrough Therapy Designation. Phase 3 RAINIER data, published in the New England Journal of Medicine last month, showed a 49.8% proteinuria reduction versus placebo. If approved, it would be Vertex’s first commercialized therapy in its emerging nephrology franchise, and the company has said it plans to build and launch this business itself.
An FDA approval is only the first test. Rare-disease launches have repeatedly shown that commercial execution after approval is where platform valuations are won or lost.
Is It Cheap?
- Forward P/E: roughly 30x on a company growing revenue 12% annually
- Price/Sales: 10.7x, premium but not irrational for a business with 41% operating margins
- $9.8 billion in cash, with CF generating enough operating cash flow to rebuild that pile quarter by quarter
- Five commercial pillars: CF, sickle cell/TDT, acute pain, rare endocrine disease, and nephrology pending
At 30x, you are not getting this cheap. But you are potentially paying a single-franchise multiple for a company that is quietly becoming a rare-disease platform.
Bull / Base / Bear
Bull: Povetacicept approval November 30, JOURNAVX gross-to-net normalization in mid-2027 drives revenue conversion, NaV1.7 pain asset enters trials and extends the pain franchise into neuropathic pain.
Base: CF holds, JOURNAVX grows 3x in annual prescriptions as guided, nephrology launches modestly. Revenue hits $14 billion in 2027.
Bear: JOURNAVX failed its sciatica study last summer. Its chronic pain future now depends entirely on a diabetic peripheral neuropathy trial reporting in 2027. A second miss resets pain franchise expectations materially. CF concentration remains a structural ceiling on the multiple.
Action Plan
If you have no position, the November 30 povetacicept decision is a live binary. A clean approval expands the addressable market and validates the platform argument. Consider a starter position now with the intent to add post-decision if approved, since launch execution will be the real test. If the FDA defers, the core CF and pain business still supports current levels.
Cheap Investor Checklist
- Povetacicept FDA decision: November 30, 2026
- JOURNAVX quarterly revenue trajectory: watch for $80 million-plus in Q4
- CASGEVY patient initiations: four consecutive quarters above 100; watch for acceleration
- CF concentration: target below 90% of product revenue within 18 months
- Operating cash flow vs. term loan repayment pace
- Diabetic peripheral neuropathy trial interim data, expected late 2026 or early 2027
- ALYFTREK reimbursement count: currently 32 countries, watch for EU expansion
Bottom Line
If povetacicept wins approval November 30 and JOURNAVX continues its prescription ramp through mid-2027, Vertex at 30x forward earnings starts to look like a platform being priced as a single product. If the kidney drug stumbles and chronic pain data disappoints in 2027, the CF dependency argument comes back hard. The position is not riskless. The business, right now, is better than the valuation debate suggests.