September 17, 2026
Bonus Content: Private Equity Is Circling Ashland. Can It Pay What the Activist Says It’s Worth?
Quick, honest heads-up.
My Simple Options Trading For Beginners book sells for $29.97 on my site. That’s its normal price most of the year.
Right now it’s free. That part doesn’t last.
I open these windows on purpose to bring in new readers, then close them back up and the price returns. No drama, no fake clock – just two prices this book bounces between, and you’re seeing the lower one.
Here’s why it’s worth the two minutes:
If you think options are something only the math-heavy crowd can do, this book quietly proves otherwise. It’s the plain-English walkthrough – calls, puts, strikes, all of it – explained the way you’d explain it to a friend over coffee.
Start from zero and you’ll still follow every page.
When the window closes, $29.97 comes back. While it’s open, it doesn’t.
Pull your copy down while it’s still on the open side.
Good Trading,
Bill Poulos
P.S. If you see this book again later, check the price. Today’s the version without one.
Private Equity Is Circling Ashland. Can It Pay What the Activist Says It’s Worth?
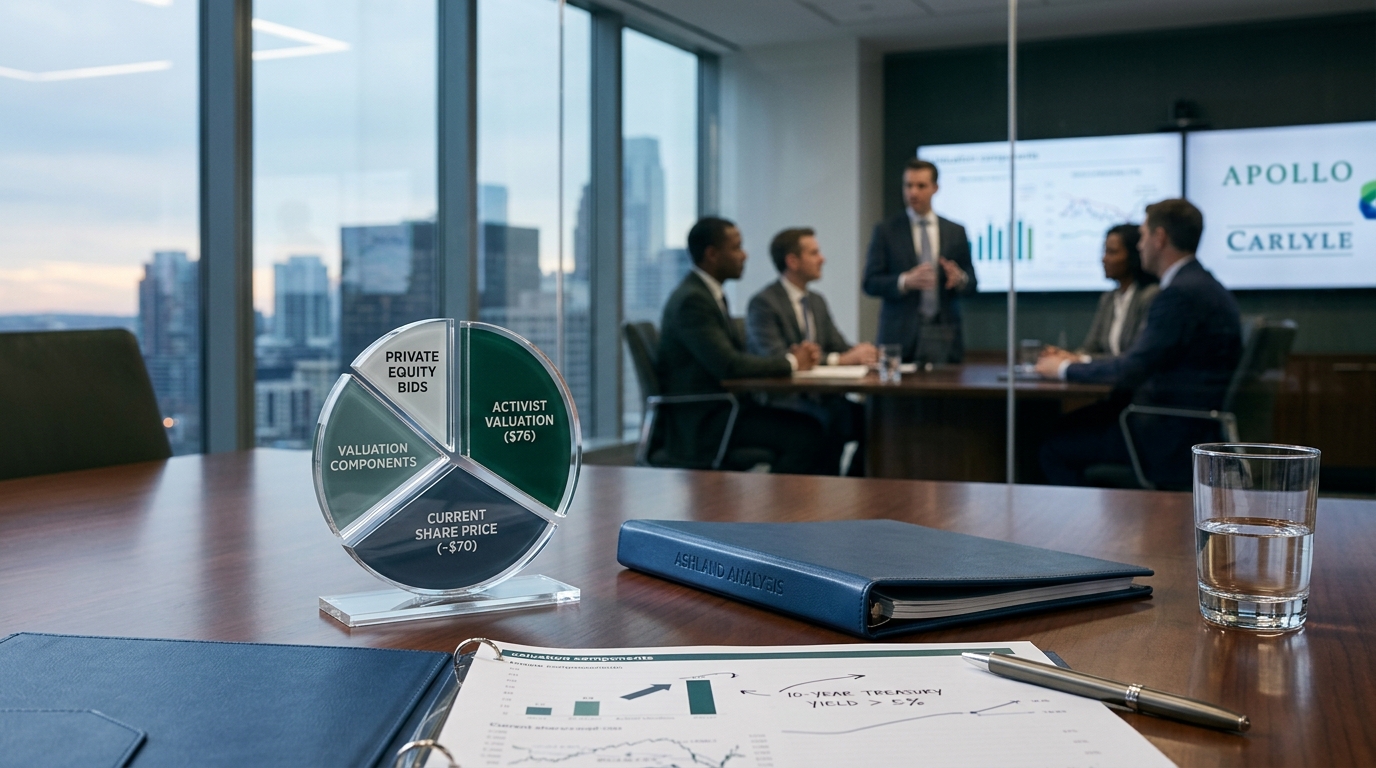
Hey there, bargain hunter. The auction everyone expected is now real. Ashland is running a sales process and collecting bids in September, with Citigroup and Lazard advising as it engages both strategic and financial suitors, including Apollo Global Management and Carlyle Group. On the initial Bloomberg report, the stock jumped about 6%. The shares trade around $70 today. That gap between here and the activist’s target is exactly where your analysis starts.
Scoreboard
Ashland supplies specialty ingredients and additives to industries including personal care and pharmaceuticals, with a market value of roughly $3.3 to $3.5 billion. The 52-week range runs from $46.30 to $78.25. Shares currently trade at roughly 9.6x EBITDA, compared with a historical median of about 11.0x, which is what makes this story live. The public market has stubbornly refused to close that gap on its own.
What Actually Happened
Ancora disclosed its stake in Ashland in June and began pushing for a sale. Ancora Alternatives, led by Jim Chadwick, said at a conference in June that a sale could boost Ashland’s share price by at least 30%. In July, Ashland settled with Ancora, adding two directors and creating a capital allocation advisory committee that runs through the 2027 annual meeting. By August, the formal process was underway. Standard Industries, already one of Ashland’s biggest shareholders, has also expressed interest.
Deep Dive
Cellulosics account for about 41% of total sales, while polyvinylpyrrolidones represent about 23%, used in pharmaceuticals and personal care. Customers include major consumer groups such as L’Oréal and Estée Lauder. That customer roster is defensible. The concern is execution: the stock dropped 24% during CEO Guillermo Novo’s tenure despite years of portfolio pruning.
The Numbers
- Q3 fiscal 2026 revenue rose 7% year over year, driven by Life Sciences and Personal Care.
- Net leverage returned to 2.4x, within the long-term target range.
- Full-year fiscal 2026 sales guidance: $1.835 to $1.870 billion.
- Full-year adjusted EBITDA guidance: $385 to $400 million.
- Total available liquidity: approximately $936 million.
Is It Cheap?
Ancora’s presentation suggested a competitive process could support a take-out valuation around 11.5x EBITDA, implying roughly $76 per share, a premium of about 33% over then-current levels, with a sum-of-the-parts case above $80 per share.
Here is where it gets complicated. The 10-year Treasury yield moved above 5% this week after the Federal Reserve hiked rates. A leveraged buyout of a $4.5 billion enterprise at 11.5x EBITDA requires a lot of borrowed money at a cost that was materially lower two years ago. Private equity can sometimes offer a higher price because it can use borrowed money and then make changes faster than public markets tend to credit upfront. But the math is tighter now. At 5% on the ten-year, every turn of leverage added to this deal costs more to service. Apollo and Carlyle are not paying $76 a share out of generosity; they need the EBITDA to grow or margins to expand to make the return work.
Bull / Base / Bear
Bull: A bidding war between Apollo, Carlyle, and strategic buyer Standard Industries drives the price toward Ancora’s $76 target or beyond. Life Sciences and Personal Care momentum gives buyers a credible growth case.
Base: One credible bid clears at $68 to $72 per share, roughly 10 to 11x EBITDA. Shareholders get a modest premium; the deal closes but leaves money on the table relative to the activist’s pitch.
Bear: Deliberations remain ongoing and there is no certainty they will lead to a transaction. Rising debt costs force bidders below current trading levels. Process collapses, shares give back the post-leak gains and retrace toward $55.
Action Plan
If you own ASH, hold. The process is live, bids are being collected this month, and multiple named parties have touched the company. Selling here means gifting your upside to the next owner. If you are looking to enter, size the position knowing the spread between $70 and $76 is not guaranteed, and a deal collapse carries real downside. Scale in at current levels with a defined stop near $60, where the stock sat before any activist involvement.
Cheap Investor Checklist
- Bid deadline: watch for any September process update or exclusivity announcement
- 10-year Treasury: a move above 5.25% materially pressures LBO math
- EBITDA trajectory: does fiscal Q4 hold the $385 to $400 million full-year range?
- Standard Industries role: strategic buyer or silent partner in a PE consortium?
- Net leverage: stays at 2.4x or better, giving buyers a cleaner balance sheet to work with
- Life Sciences sales: sustained double-digit growth is the growth story PE needs to underwrite
- No-deal scenario: does ASH trade back to the mid-$50s without a transaction?
Bottom Line
If the process produces a real bid at 11x EBITDA, ASH is worth roughly $73 to $76. If rising borrowing costs force buyers to 9.5x, you are looking at $63 to $65, below today’s price. The auction is live and the activist did its job getting everyone in the room. Whether Apollo or Carlyle can make the arithmetic work at 5% on the ten-year is the only question that matters now.