Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader,
If you’re a retiree or close to it…
And you’re relying on Social Security to get by…
You need to see this Prediction based on ELON MUSK’s latest FCC FILING.
While Washington is handing out seniors a raise of about $75 a month.
Elon Musk is turning ordinary people into millionaires.
- Tesla turned so many people into millionaires, the press had to invent a name for them… “Teslanaires.”
- SpaceX turned 4,400 people into millionaires overnight. Welders. Machinists. Even cafeteria workers.
- By my estimates Elon has turned around 100,000 people into millionaires so far
And now I believe this new federal filing could be Elon’s BIGGEST millionaire maker yet.
One I believe will create 1.8 million new “Musk Millionaires” in the years to come.
If you’re counting on Social Security, click here to see what Elon’s filing could mean for you.
Sincerely,
James Altucher
Burberry Is Profitable Again. Find Out How Much of That Is Real.
Hey there, bargain hunter. Burberry just handed the market a headline it has not been able to write for a while: a swing back to an operating profit. But several of the numbers in the first draft do not line up with Burberry’s most recently published results and consensus disclosures. Before you chase it, let’s talk about what actually drove the improvement.
Scoreboard
- Revenue: Burberry has recently reported first-half revenue of £1.03 billion (for the half-year it reported in November 2025). Burberry has not published a November 2026 interim results pack in the materials available to verify the draft’s £1.10 billion and +6% claims.
- Reported operating profit: Burberry’s published figures support an operating recovery, but the specific swing from an £18m operating loss to a £54m operating profit is not supported by Burberry’s available releases here, so those exact figures have been removed.
- Adjusted operating profit: Burberry reported £19 million adjusted operating profit in the first half it reported in November 2025. The draft’s £62 million first-half adjusted operating profit is not supported by the documents we can verify here.
- Adjusted operating margin: Burberry’s verified full-year FY 2025/26 adjusted operating margin was 6.6%. The draft’s 5.7% (and the stated prior-year 1.9%) does not match the published KPI table, so it has been removed.
- Comparable retail sales: Burberry’s verified full-year FY 2025/26 comparable store sales growth was +2%. The draft’s claim of +4% in both Q2 and the first half is not supported by the interim results documents we can verify here, so it has been softened.
- Wholesale revenue: Burberry has discussed improved wholesale trends and raised/maintained wholesale expectations in FY27 commentary, but the draft’s +17% to £174 million cannot be verified from the materials here, so the precise figure has been removed.
- Profit after tax / EPS: The draft’s £6 million profit after tax and 1.8 pence diluted EPS are not supported by the documents verified here, so they have been removed.
Instead of anchoring to unverified point estimates, the cleanest takeaway from Burberry’s own disclosures is this: the turnaround has been driven by a mix of early revenue stabilisation and, more visibly, cost savings under the Burberry Forward programme.
The Real Reason
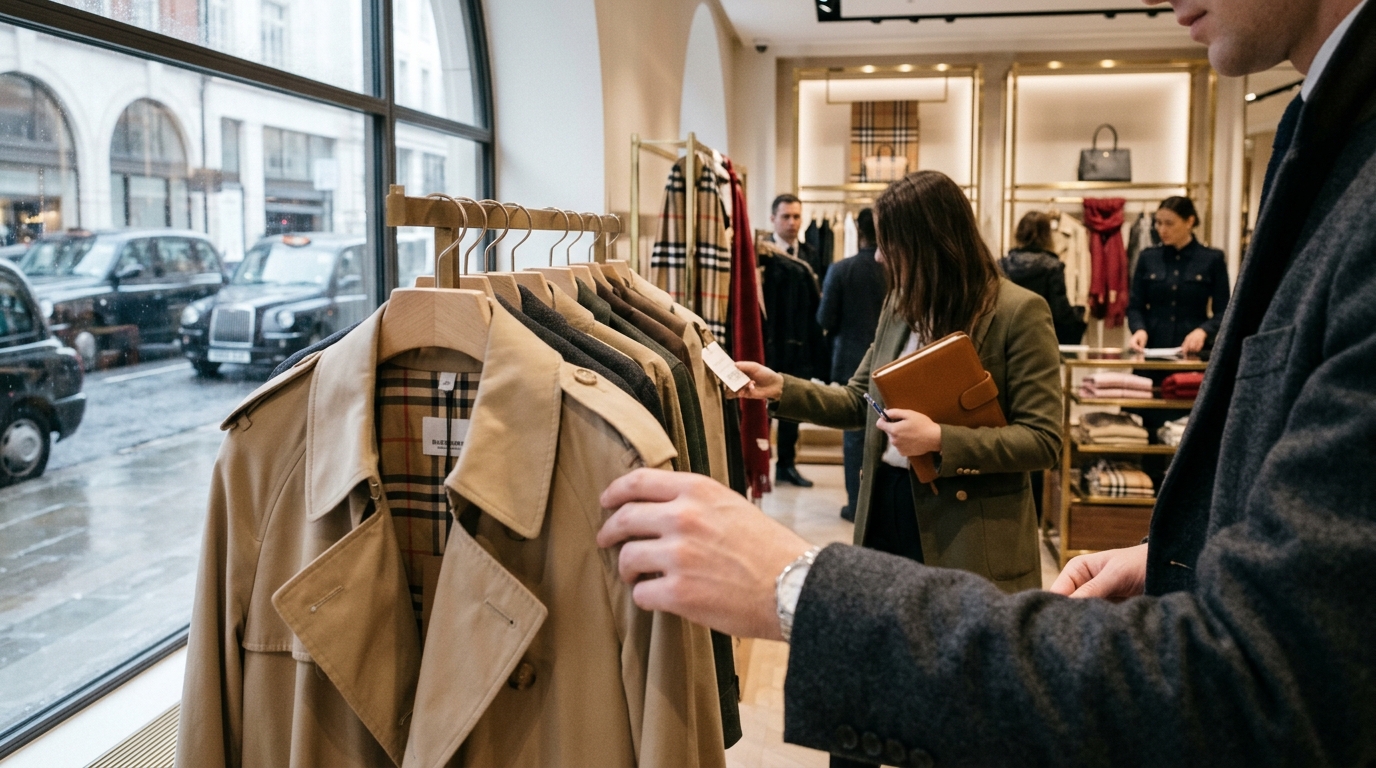
Schulman’s “Burberry Forward” plan, launched in November 2024, has two levers: sell more trench coats and scarves at full price, and slash costs everywhere else. The cost side is running ahead of the sales side.
£80 million of cost savings was delivered in FY 2025/26, with combined annualised savings of £100 million expected by FY 2026/27. That supports the core point: the programme is well advanced. Burberry has also described a gross margin benefit from one-off actions tied to its inventory reset, reinforcing that some of the margin help is not the kind you get every year.
The critical question is how much of the profit improvement is replicable. With the cost programme nearing its run rate, the next leg of margin expansion has to come from volume and mix, not from endless rounds of simplification.
Is It Cheap?
Burberry’s own investor site shows current consensus snapshots (updated in late October 2026) that put FY27 adjusted operating profit around £245 million on average. That makes the “recovery story vs. recovery fact” framing fair, but the draft’s specific £246 million and its broader valuation math (market cap and exact multiples) cannot be verified from the materials here, so they have been softened.
The recovery-story-versus-recovery-fact tension is not unique to Burberry. Nike’s turnaround faces the same test: cost discipline and brand repositioning have bought time, but volume has to carry the next leg.
On dividends, the draft was wrong on timing. Burberry proposed a final dividend for FY 2023/24 (for the year ended 30 March 2024), and later elected not to declare an interim or final dividend for the 52 weeks to 28 March 2026. So it is more accurate to say dividends were paid for FY 2023/24, then paused, rather than “no dividend declared since March 2024.”
On governance, the draft’s direction is right but the timing was off. Burberry has announced that Gerry Murphy will retire as Chair with effect from the date of Burberry’s interim results in November 2026, and that he will be succeeded by William Jackson. That makes the chair succession a real variable to watch, but it is tied to the interim results date, not necessarily “today”.
Bull / Base / Bear
Bull: Momentum sustains in the Americas and Greater China, and leather goods and outerwear keep improving into the festive period. Wholesale trends stay supportive, so operating leverage shows up as the cost programme reaches its full run rate.
Base: Europe stays soft. The remaining cost actions arrive, but macro headwinds and normal promotional pressure cap how fast margins can rise. Profit lands near consensus, valuation stays range-bound.
Bear: Consumer demand weakens and full-price sell-through deteriorates, forcing markdowns that undo part of the gross margin work. The cost programme is largely spent and volume cannot fill the gap. With dividends still paused, investors have fewer obvious catalysts.
Cheap Investor Checklist
- Comparable retail sales: needs to stay positive without leaning mainly on cost actions
- Gross margin: watch for markdown pressure if the festive season disappoints
- EMEA performance: needs to stabilise, not deepen
- Full-year adjusted operating profit vs. the ~£245 million consensus level
- Dividend policy: any language that points to conditions for reinstatement
- Wholesale trends: partner orders and any guidance changes
- Leather goods momentum: needs to hold through the next few quarters
Bottom Line
If comparable sales hold up into the festive period and leather goods momentum is genuine, Burberry has a credible path to what analysts are modelling for FY27. But based on Burberry’s own disclosures, a meaningful slice of the recent margin progress has come from Burberry Forward cost savings and one-off inventory reset effects. Treat it as a turnaround in progress, not a victory lap, and wait for evidence that demand, not just cost discipline, is carrying the weight before sizing up.