The ticker is only the beginning. Here is what comes next.
You finally find a stock you like.
Then you open the options chain.
Which expiration? Which strikes? What entry price? How much is at risk?
Suddenly, finding the stock feels like the easy part.
Matt, the trader behind Income Blueprint, knows that bottleneck.
He describes going through 40 or 50 stocks, sometimes finding one he liked only to discover the options didn’t fit.
That’s the problem he built the tool to help solve.
Income Blueprint ranks stocks with a five-part scorecard, then evaluates the options for pricing, liquidity, and potential return.
It surfaces three top-ranked stock signals, with the available approaches for each.
Open a setup and you can review the proposed options, entry price, expiration, and estimated risk and reward together.
Now you have something concrete to evaluate before deciding whether to trade.
Matt walks through the process in a free presentation.
He also explains how to get 30 days of tool access and options training at no cost, with no credit card required.
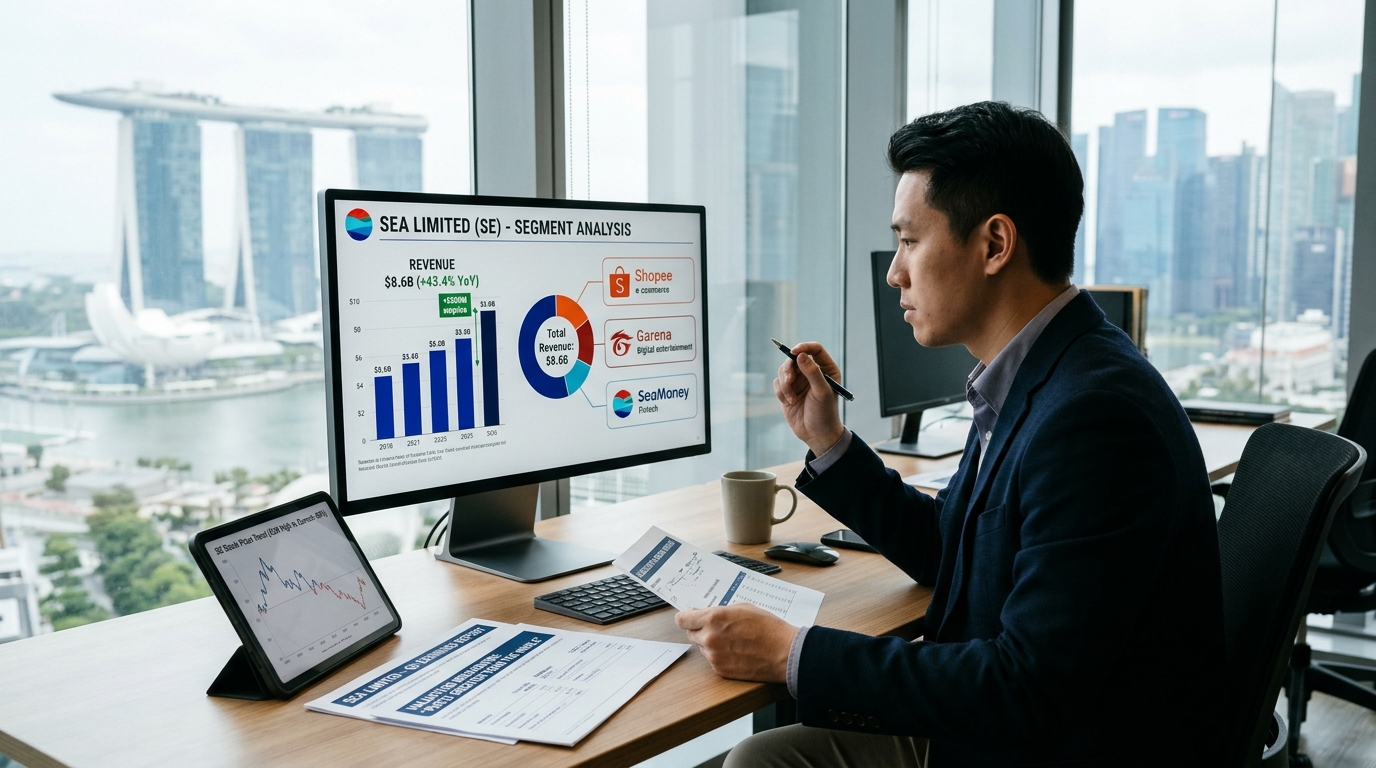
Sea Limited Beat Revenue by $500M. Its Three Businesses Are Worth More Than the Stock Price Suggests.
Hey there, bargain hunter. Sea Limited handed Wall Street a roughly $500 million revenue surprise on Tuesday morning, and the stock still fell in premarket trading. That is the kind of situation that deserves a closer look rather than a quick sell click.
Scoreboard
Revenue surged to $8.6 billion, beating estimates by roughly $500 million and marking a 43.4% year-over-year increase. EPS came in at $0.78, missing expectations, even as adjusted EBITDA climbed to $931.3 million. Operating income stood at $664.2 million, up from $475.9 million a year ago, and net income reached $502.5 million, up 34.0% year-over-year. The company said it has almost fully completed its prior $1 billion share repurchase program and announced an additional $1 billion in buybacks.
What Actually Happened
The earnings shortfall traced primarily to Monee’s rapidly expanding loan book, where the company said provisions for credit losses rose 82.3% year-over-year as Monee extended credit into more everyday spending scenarios. This is the critical distinction. The revenue engine is firing. The EPS miss is a function of Monee aggressively building a fintech franchise, not a sign the core business is weakening.
The EPS miss extends a pattern visible across recent quarters: Sea has fallen short of earnings expectations in five of the past eight periods, while revenue has generally held up. The market knows this pattern. The market is still selling. That gap between what the numbers say and what the price implies is where the opportunity sits.
The Three Businesses, Priced Separately
Sea runs three distinct franchises under one ticker. Here is what each did in Q3:
- Shopee (e-commerce): Revenue surged to $6.1 billion, gross orders rose 25.5% to 4.5 billion, GMV climbed 23.3% to $39.7 billion, and adjusted EBITDA increased 44.7% to $269.2 million, making it the most profitable quarter in Shopee’s history.
- Monee (fintech): Revenue was up 63.9% year-over-year to $1.6 billion. Adjusted EBITDA reached $298.3 million. The credit loss provisions are the cost of growing a loan book fast, not evidence of deteriorating asset quality.
- Garena (gaming): Bookings grew 5.9% year-over-year and 16.6% quarter-over-quarter to $890.0 million, with GAAP revenue climbing 28.6% to $840.1 million and adjusted EBITDA reaching $458.2 million.
Add the three EBITDA lines together and you get roughly $1.03 billion in a single quarter from operations that were hemorrhaging cash just two years ago.
Is It Cheap?
On Wednesday, November 11, 2026, SE traded around $77, so it is not accurate to call it “roughly $80” today. With the stock in the high $70s, the broad point still holds: the market is valuing a fast-growing, cash-generating platform well below where it traded at prior peaks, while peers like MercadoLibre still command much richer valuation multiples.
Now test the new $1 billion buyback against reality. Sea said it has almost fully completed the prior $1 billion repurchase authorization and has approved an additional $1 billion authorization with no expiration. That is meaningful, but the specific free cash flow figures in the draft were not supported by Sea’s Q3 2026 release materials, so they have been removed here rather than leaving stale or unverified numbers standing.
Bull / Base / Bear
- Bull: Monee’s credit provisioning stabilizes as the loan book matures, EPS re-accelerates, and the stock re-rates as investors get more comfortable underwriting the credit cycle.
- Base: Revenue growth stays strong, Shopee continues posting record EBITDA quarters, and the buyback provides a steady bid under the shares. The stock drifts higher as the EPS overhang clears.
- Bear: Competition from TikTok Shop, Lazada, and Shein pressures Shopee pricing. Monee credit losses worsen in a Southeast Asian slowdown. The stock retests prior lows.
Action Plan
The premarket dip is not a verdict on the business. It is a reaction to a headline EPS number that obscures what is actually happening inside three fast-growing franchises. For a scale-in approach: a starter position near current levels in the high $70s, a second tranche on further weakness, and a full position only once Monee’s provision growth rate shows signs of flattening.
Cheap Investor Scorecard
- Revenue growth rate: 43.4% year-over-year. Watch for deceleration below 30%.
- Shopee EBITDA: $269.2 million this quarter. Target: sustained positive and expanding.
- Monee credit loss provision growth: 82.3% this quarter. The number to watch next quarter.
- Garena bookings trajectory: Up 5.9% annually and 16.6% sequentially. Stabilization confirmed.
- Buyback execution: almost all of the prior $1 billion deployed, and another $1 billion authorized. Watch quarterly share count.
- Analyst consensus: treat targets as a sentiment gauge, not a catalyst.
Bottom Line
If Monee’s credit loss provisions peak within the next two quarters and EPS resumes tracking revenue growth, Sea in the high $70s looks like a business the market is still discounting for a messier credit story than it may ultimately deliver. If the loan book keeps generating outsized provisions and Southeast Asian competition clips Shopee’s margin, the story drags longer. The revenue line is not in question. The question is when the bottom line catches up. Watch Q4 Monee provisions closely, and size accordingly.