October 23, 2026
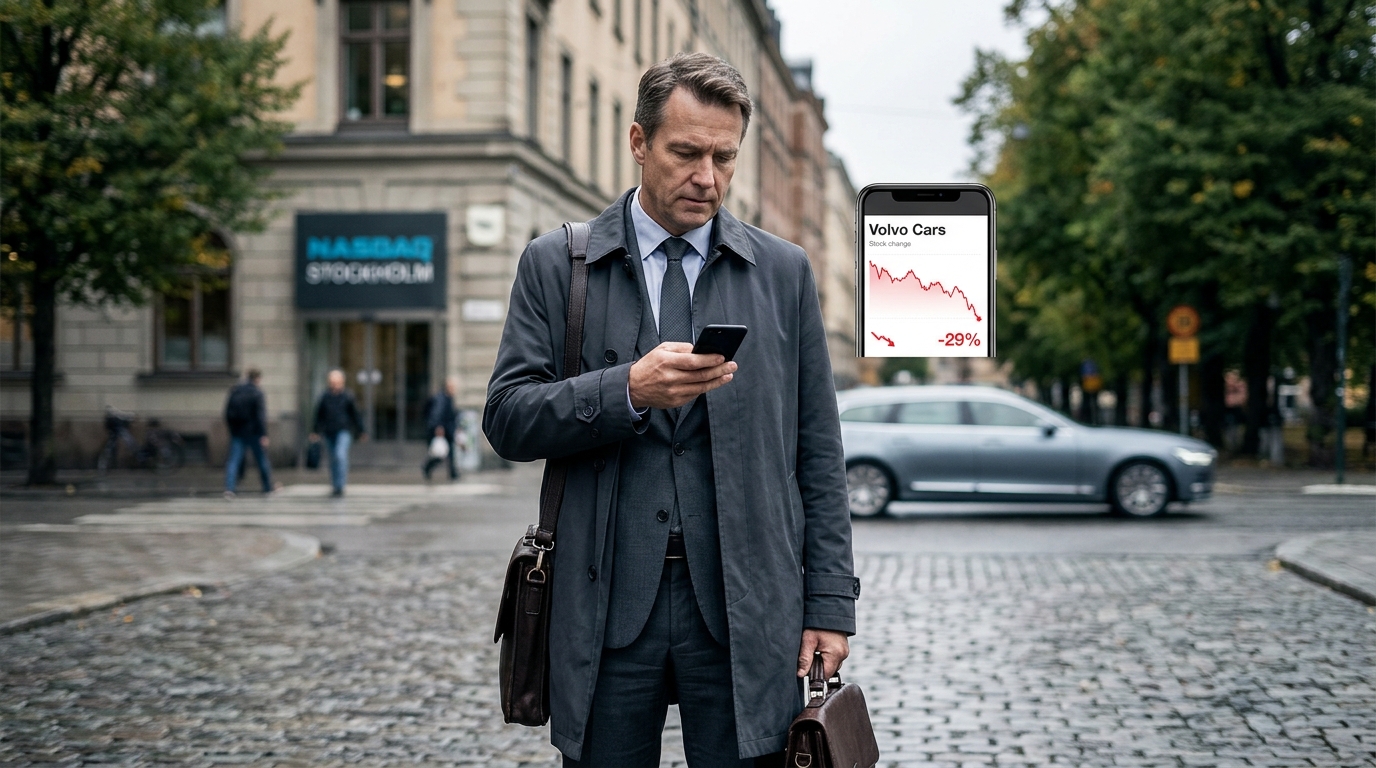
Bonus Content: Volvo Cars Lost Half Its China Revenue. Is a 29% Drop Enough of a Discount?
Dear Reader,
According to Wall Street legend Dr. Martin D. Weiss, there’s a $3 trillion disaster in the making in the markets, and it could have a sizable impact on your wealth.
“The crisis that’s emerging now is just the tip of the iceberg,” says Dr. Weiss, who has made shocking and accurate predictions for 55 years, including predicting the Dot-Com collapse and the implosion of Fannie Mae, Bear Stearns and Lehman Brothers in the 2000s.
 |
The New York Times has credited Weiss as being “the first to see the dangers.” Forbes called him “Mr. Independence.” His contributions have been recognized by the U.S. Government Accountability Office.
“The biggest danger is not just another stock market crash,” he continues. “The biggest danger is not only a major bank failure. Rather, it’s a chain reaction of crashes and failures that could cause a global freeze in the financial markets,” adds Weiss.
The tip of this iceberg? It’s already emerging and impacting perhaps thousands of investment accounts across America.
Weiss, who has testified in front of Congress, says there are five specific steps every American must consider making with their money, before it’s too late.
“When the system freezes, nothing works. Virtually everything shuts down. Companies cannot make payroll. Banks cannot meet their daily obligations. Even the Federal Reserve cannot fix it without massive, Herculean efforts.”
Weiss is doing everything he can to warn the public while there’s still time to prepare, including issuing press releases and reaching out to media outlets.
In fact, Dr. Weiss has urged us to post a brand-new, urgent warning on our public website …
You can access his video message – free of charge – when you click here.
Sincerely,
Eliza Lasky
Weiss Advocate
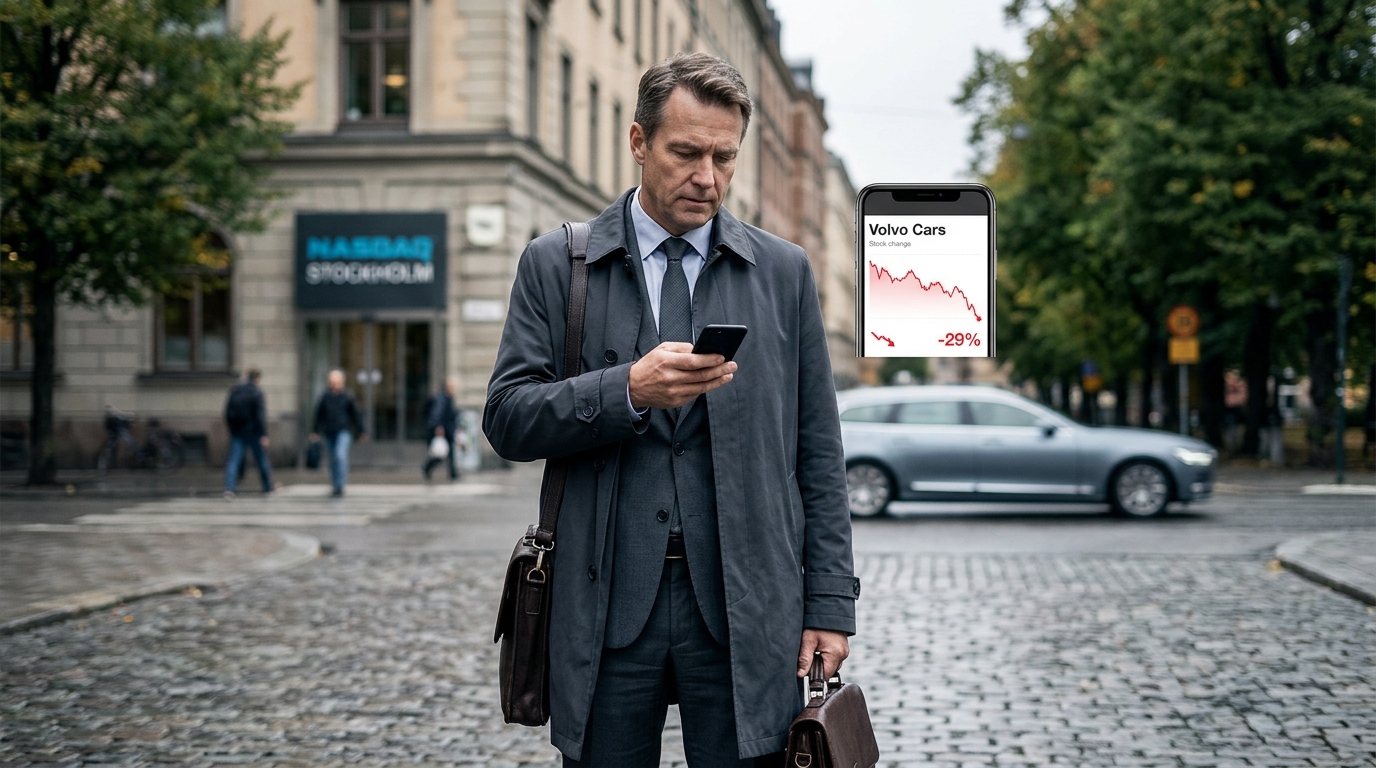
Volvo Cars Lost Half Its China Revenue. Is a 29% Drop Enough of a Discount?
Hey there, bargain hunter. Before you go bottom-fishing in Scandinavia this morning, make sure you know exactly what is sitting at the bottom of this particular lake.
Scoreboard
Volvo Cars swung to a core EBIT loss of SEK 3.7 billion in Q3 2026, against a profit of SEK 5.8 billion a year earlier, and the market did not take it quietly. Shares on the Stockholm exchange fell roughly 29% on the day, trading at about SEK 10 versus a prior close of SEK 14.12. That puts the stock near a fresh 52-week low.
What Actually Happened
Revenue was SEK 66.9 billion versus SEK 86.4 billion a year earlier, a drop of roughly 23%. Two markets drove most of the damage. In China, revenue fell by about 50% year-on-year as Volvo Cars and other legacy premium brands faced fierce competition from new Chinese rivals and severe pricing pressure. In the United States, tariffs and weaker demand continued to squeeze margins.
Including joint ventures and items affecting comparability, the operating loss widened to SEK 5.6 billion, against a profit of SEK 6.4 billion a year ago, with a margin of -8.4% versus +7.4% previously. Free cash flow was negative SEK 8.9 billion versus negative SEK 4.3 billion a year earlier. That cash bleed is not a rounding error.
5 Options Basics Every New Trader Should Know
1) The core vocabulary. 2) How calls and puts work. 3) The risk factors to check before trading. 4) A step-by-step way to evaluate an idea. 5) Practical examples to follow at your own pace. It’s all inside Options Trading Made Easy, a free guide for anyone who wants to learn options the simple way. Download it today.
The Polestar Problem
One item bargain hunters tend to overlook: a roughly SEK 0.9 billion negative hit tied to Volvo Cars recognising Polestar-related losses landed inside these numbers earlier this year. Volvo is not just fighting its own fires. It is also subsidising the turnaround of an EV brand that has not yet found stable footing. That is a recurring drag with no clear expiry date attached.
The Response Plan
- Management announced an additional SEK 5 billion in cost cuts and 2,500 job reductions.
- The 2,500 job reductions are global, with approximately 2,000 in Sweden.
- Capital expenditure will be cut 30% from 2024 levels.
- The full effect of the cuts will not arrive until the end of 2027, when indirect spending is expected to be almost 25% lower than in 2024.
The company said its EX60 has drawn more than 50,000 orders, but production is ramping up more slowly than planned. The product pipeline is not empty. The execution timetable is the problem.
The contrast with a Detroit rival is instructive. GM raised full-year guidance twice while facing the same China-and-tariff environment Volvo cannot escape.
Is It Cheap?
At current prices, Volvo Cars trades at a price-to-book of about 0.28 and a price-to-sales of about 0.13. Those are distressed multiples, not bargain multiples. The distinction matters. A stock is only cheap if the business can recover. Volvo needs China to stop deteriorating, the EX60 ramp to accelerate, and Polestar losses to stop compounding inside its own income statement, all before 2027 cost savings kick in.
Bull / Base / Bear
Bull: EX60 orders convert into deliveries, China stabilises from a very low base, cost cuts land ahead of schedule, and the stock doubles from a starting point near a 52-week low.
Base: Restructuring drags through 2027, free cash flow stays negative for several more quarters, and the shares trade sideways in the SEK 10-15 range while the market waits for evidence the plan is working.
Bear: China volumes keep falling, Polestar losses grow, and a balance sheet already strained by SEK 8.9 billion of negative free cash flow forces a capital raise. Investor concern about profitability, China exposure, and near-term execution risk stays elevated.
The cash-flow trajectory is the mechanism that separates a distressed recovery from a value trap. Boeing’s turnaround only became investable once free cash flow turned positive.
Action Plan
Do not chase the dip today. The stock is down about 29% on unusually heavy volume. That is panic, and panic sometimes overshoots. But the fundamental problem, weak profitability and a negative cash cycle that is getting worse, is not resolved by a lower share price alone. If you want exposure, wait for Q4 free cash flow data and early EX60 delivery numbers before sizing in. A small starter position for the genuinely patient is defensible. A full position today is speculation.
Skip the noise. Get one idea.
Most market news is noise. The Street Sheet sends one trade idea a day, sourced from top Wall Street analysts for self-directed investors. Free, and trusted by over 130,000 readers.
Cheap Investor Scorecard
- Core EBIT: SEK -3.7bn (vs. +5.8bn a year ago) — red
- Free cash flow: SEK -8.9bn — red
- China revenue: down ~50% year-on-year — red
- Polestar drag: roughly SEK -0.9bn recognised earlier in 2026 — watch
- EX60 orders: 50,000+ booked, ramp delayed — amber
- Job cuts: 2,500 announced, savings back-loaded to 2027 — amber
- CapEx reduction: 30% below 2024 levels — green
- Price-to-book: ~0.28 — distressed, not proven cheap
- Guidance: withdrawn for 2026 volume and cash flow — red
- 52-week range: near SEK 10 to SEK 36.54 — near low end
Bottom Line
If China revenue stabilises and the EX60 ramp accelerates in the next two quarters, Volvo Cars at these prices will look like an obvious buy in hindsight. If neither happens, a price-to-book of about 0.28 can go lower. The stock is statistically cheap. The business is not yet provably fixable. Wait for at least one data point that says the cash bleed is narrowing before committing real capital.